Browsed by
Category: Economics

Dispelling Popular Great Depression Myths: Robert Murphy’s “The Politically Incorrect Guide to the Great Depression and the New Deal” (2009) – Article by G. Stolyarov II

Dispelling Popular Great Depression Myths: Robert Murphy’s “The Politically Incorrect Guide to the Great Depression and the New Deal” (2009) – Article by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
Originally Published November 25, 2009
as Part of Issue CCXIX of The Rational Argumentator
Republished July 23, 2014
******************************
Note from the Author: This essay was originally published as part of Issue CCXIX of The Rational Argumentator on November 25, 2009, using the Yahoo! Voices publishing platform. Because of the imminent closure of Yahoo! Voices, the essay is now being made directly available on The Rational Argumentator.
~ G. Stolyarov II, July 23, 2014
***

Download a free audio recording of this essay here.

We live in times when fact and propaganda are all too easily – and often deliberately – conflated. I recall, a long time ago, sitting in my public high school’s Advanced Placement US History course, when the instructor explicitly mentioned “lack of government regulation” as one of the causes of the Great Depression. The odd aspect was that he prefaced this explanation with an explicit warning to me that I would not like what he was about to say.

It was as if he knew that he was presenting an ideologically charged position as fact – and he did it anyway, because, in his mind, no other interpretation of the Great Depression was possible. He and millions like him would benefit immensely from reading Robert P. Murphy’s The Politically Incorrect Guide to the Great Depression and the New Deal.

The myth of the Great Depression being caused by laissez-faire capitalism – and being solved by either the New Deal, World War II, or both – is so prevalent that in popular-opinion surveys, Franklin Delano Roosevelt routinely appears in the top five of all US presidents, while the name of Herbert Hoover has become synonymous with government inaction during an economic crisis. Hundreds of books, essays, and even works of fiction have been published to challenge these notions – but somehow the fallacies have prevailed; and they have been eagerly exploited by the would-be FDRs of the past seven decades.

For millions of Americans who have not studied Austrian economics and the Mises/Hayek theory of the business cycle, or read the brilliant critiques of the New Deal by H.L. Mencken, Isabel Paterson, Albert Jay Nock, Garet Garrett, and John T. Flynn, the commonplace myth of laissez-faire as ruinous and FDR as savior appears true, self-evident, and incontestable. Unfortunately, many of these same people vote for politicians and policies that promise a “New New Deal.” Such a plan would further exacerbate the current economic crisis, which is fueled by hyperregulation, Federal Reserve manipulation of the money supply, and the unforeseen consequences of prior interventions, including the original New Deal.

Murphy’s work seeks to correct popular misunderstandings of the Great Depression by attacking them directly. Virtually every single commonly encountered assertion – that the Depression was caused by the excesses of capitalism, that Hoover exacerbated the Depression by “doing nothing,” that the New Deal revitalized economic activity and mitigated unemployment, and that World War II energized the United States into recovery – is refuted at length. In the course of this debunking, the reader is treated to concise, elegant explanations of the Austrian theory of the business cycle, the economics of tax reduction, the virtues of the gold standard and the dangers of fiat currencies, and to discussions of the errors both in Keynesian prescriptions for deficit spending and in the Chicago School’s suggestion that the Federal Reserve triggered the Great Depression by failing to inflate sufficiently.

To add flavor to the book and enable readers to identify with more concrete aspects of the policies it criticizes, Murphy discusses many of the follies and corruptions of the New Deal: FDR’s use of “lucky numbers” to set the price of gold, the persecution of the Schechter brothers for defying the National Recovery Administration’s restrictions on poultry production, FDR’s attempt to pack the Supreme Court with his supporters after the court ruled in favor of the Schechter brothers, the confiscation of private citizens’ gold holdings, and the New Dealers’ pervasive use of government funding to bribe and intimidate constituencies into supporting FDR’s policies.

Murphy skillfully reminds us that the politicians who seek to suppress our economic and political liberties in favor of a central plan are neither omniscient nor benevolent; they quite frequently pull policy prescriptions out of thin air and they are anything but evenhanded, tolerant, or concerned for objective human wellbeing. Behind the lofty rhetoric and faux amiability of men like FDR stands the harsh, impatient, implacable, and often indiscriminate enforcer, in the mold of those thugs who broke into peaceful men’s homes to ensure that they were not violating the National Industrial Recovery Act by sewing clothes at night.

If there is any hope for an intellectual rejection of New Deal ideology in the United States, Murphy’s book will be one of the crucial elements motivating it. Murphy bridges the gulf between high theory and the concerns accessible to the majority of readers. While it is unfortunate that, given the state of education in our time, most Americans would not be able to immunize themselves against common economic fallacies by directly reading Menger, Mises, Hayek, and Rothbard, Murphy helps bring some of the key ideas of these thinkers into a format more accessible to a layman with no formal economic training.

Murphy also incorporates the work of such historians as Burton Folsom and Paul Johnson, and he draws on biographical information to shed light on the lives, motivations, and personalities of Calvin Coolidge, Herbert Hoover, and other key figures of the 1920s and 1930s. Murphy does for the popular understanding of the Great Depression in the early 21st century what Frederic Bastiat did for free trade in the mid-19th and what Leonard Read and Henry Hazlitt did for basic economic principles in the 20th.

I am a former student of Murphy, and I can credit his instruction for enabling me to advance from a basic understanding of Austrian economics to the publication of a paper in the Quarterly Journal of Austrian Economics. From personal experience, I know him to be well-read, cosmopolitan, sophisticated, and capable of articulating the arguments – and recognizing the strengths and weaknesses – of an immense variety of theories and worldviews. At the same time, he possesses a talent for communicating complex and challenging ideas, connecting them to concrete phenomena, and even joking about them.

As such, he is eminently suited to bringing some of the most important economic and historical insights of the 20th century to a mass audience. Indeed, it might reasonably be hoped that thousands of readers of this book will use it as a gateway to discovering the works of the many free-market thinkers cited therein. The lists of suggested readings (“Books You’re Not Supposed to Read”) peppered throughout the text make it a worthwhile purchase by themselves.

Perhaps someday my old US history teacher, and men like him, will use The Politically Incorrect Guide to the Great Depression in their courses to balance the many explicitly pro-New Deal and prointerventionist texts and presentations that dominate public-school curricula today. If this is too much to hope for, then at least this book has the potential to appeal to many young students and be sought out by them on their own initiative – as an antidote to the fallacies they encounter from “mainstream” sources.

Read other articles in The Rational Argumentator’s Issue CCXIX.

Incentives Matter… On the Margin (2010) – Article by G. Stolyarov II

Incentives Matter… On the Margin (2010) – Article by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
Originally Published January 10, 2010
as Part of Issue CCXXXI of The Rational Argumentator
Republished July 22, 2014
******************************
Note from the Author: This essay was previously published as part of Issue CCXXXI of The Rational Argumentator on January 10, 2010, using the Yahoo! Voices publishing platform. Because of the imminent closure of Yahoo! Voices, the essay is now being made directly available on The Rational Argumentator.
***
~ G. Stolyarov II, July 22, 2014
***

One of the favorite expressions of economists is “Incentives matter.” There is much truth to this idea, but it is instructive to examine how it works a bit more closely.

An incentive is a set of conditions that favors one course of action and/or disfavors its opposite. A positive incentive increases the reward or decreases the cost associated with a decision, while a negative incentive increases the cost or decreases the reward associated with it. An incentive can be a condition of the natural environment, a conscious human choice, or an emergent outcome – a characteristic of what Friedrich Hayek called a “spontaneous order.”

But it is not the case that all human beings are moved by the same incentives to a particular course of action or inaction. For instance, an increase in the cost of gasoline might lead some people to drive less – but a wealthy car enthusiast might just take the hit and pay the higher price; for him, a negative incentive was not a sufficient deterrent to his behavior of choice. On the other hand, ample information and culture available virtually for free on the Internet might motivate more people to become computer-literate, but for certain individuals with a strong visceral fear of electronic technology, this might not be enough; the positive incentive has failed to overcome the psychological barriers within them.

We can best see how incentives matter by examining large-scale changes in behavior. Crime statistics in an area might fall, for instance, if people were allowed to carry concealed weapons in public, where a previous law might have prohibited this. But there would still be some individual acts of crime, just as there would still be some people who would never think of committing a crime, no matter how easy it would be to perpetrate one or to get away with it. If the government raised the minimum wage, the unemployment rate would increase over what it would have been otherwise, but it is not the case that all workers – or even all workers previously earning less than the minimum wage – would suffer or lose their jobs. Some low-income workers might even get a pay raise, but likely at the expense of others being laid off or never being hired in the first place. Yet some generous employers might choose to personally absorb the cost increase and refuse to lay off any workers – but this might mean fewer other investments in their businesses or a lower standard of living for these business owners.

We can summarize this insight by stating that incentives matter on the margin. If a person’s other characteristics – including ideas held, material position, and skills – strongly favor one course of action over another, then an incentive to the contrary is unlikely to change that person’s behavior. On the other hand, if a person is barely inclined one way or another, then an incentive might result in a shift of behavior.

Once made explicit, all of this might appear self-evident to someone who paid attention in a basic economics course. Why is it important, and why does it bear emphasizing? There are several reasons.

Recognizing the marginal importance of incentives prevents individuals from looking for panaceas or overnight revolutions, of which our world yields extremely few, if any. On the other hand, it also inculcates one against despair. Any sufficiently strong incentive will result in a desirable or undesirable statistical shift, but it is unlikely to completely solve a problem. On the other hand, it is also unlikely to completely doom the state of affairs, either. Human beings are remarkably resilient and intricately complex. Crimes, disasters, bad laws, and health defects will destroy some and keep down others – but human innovation and creativity will not completely die; it will flourish somewhere, in some way or another, where the negative incentives are not strong enough to thwart the civilizing desires of the best among us. But it is also important to recognize that human existence is a continual struggle against both natural perils and the follies and even the evils committed by our fellow men. We will need more than one incentive to be favorably arranged if we are to keep these enemies of civilization at bay.

The marginal functioning of incentives is also a cause for hope. If a destructive policy were to completely cripple some facet of human life, then there might not be a way to resist it effectively. But because some individuals are sufficiently strong internally so as not to be diverted from their course by the policy, they can amass the will and the resources to resist it. Moreover, people can condition themselves to respond more or less strongly to certain incentives. The more a person can train himself to persevere in the face of significant externally imposed costs, the more likely that person is to succeed despite such obstacles. Such successes are the building blocks upon which all human civilization has been built.

It is instructive to remember that there has never been an even tolerably calm and safe environment for innovators to flourish; at every time and place in history, some force – deliberate or not, more severe or less so, but never particularly mild – stood in the way of the thinkers and creators to whom we owe our progress. Where the carriers of civilization overcame these forces, they created a more favorable environment for us. We must, likewise, strive against the challenges of our time. By overcoming existing negative incentives, we can create positive ones for the future, through the examples we set and the work we bring forth.

Click here to read more articles in Issue CCXXXI of The Rational Argumentator.

Writers Can Prosper Without Intellectual Property (2010) – Article by G. Stolyarov II

Writers Can Prosper Without Intellectual Property (2010) – Article by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
Originally Published January 13, 2010
as Part of Issue CCXXXI of The Rational Argumentator
Republished July 22, 2014
******************************
Note from the Author: This essay was previously published as part of Issue CCXXXI of The Rational Argumentator on January 13, 2010, using the Yahoo! Voices publishing platform. Because of the imminent closure of Yahoo! Voices, the essay is now being made directly available on The Rational Argumentator. The fundamental concepts in this article remain sound, but the specific references to content sites – such as Associated Content, Helium.com, and Today.com – which previously allowed writers to monetize their works, are now obsolete, due to the closures of these sites. This should be a lesson to writers: utilize external sites for revenue generation if you need to, but always keep all of your writings hosted on sites you control as well!
***
~ G. Stolyarov II, July 22, 2014
***
(This article was originally published by the Ludwig von Mises Institute. A free MP3 audio file of this article, read by the author, is available for download.)
***

It is commonly supposed that, whatever its moral and theoretical standing, intellectual property is necessary for creators of written works to make a living and – even more importantly – to continue to create. Here, I will set aside the theoretical status of copyright, which is amply discussed in Stephan Kinsella’s Against Intellectual Property and Michele Boldrin and David Levine’s Against Intellectual Monopoly. I will focus on existing and emerging possibilities for writers to earn a living in a world where no copyrights exist.

By way of real-world examples and suggestions based on observations of existing and historical practices, I seek to assure writers and other intelligent laymen of all persuasions that writers would not starve, and writing would continue to flourish, if copyrights disappeared off the face of the Earth tomorrow. I hope to foster an appreciation of the breadth of human creativity and the multitude of possibilities for innovative endeavors.

The popular, copyright-inspired model of revenue generation for writers entails contracting with a publishing company for a combination of payments: (1) a modest initial advance on the written work, typically paid at or prior to publication, and (2) a continual stream of royalties, typically paid as a proportion of the written work’s earnings. The royalties comprise the greatest share of revenue for most “traditionally” published writers under the copyright system; most authors and publishers within this system perceive copyright as necessary to ensure that the royalties continue for a prolonged period of time.

Even without copyright, there is a first-mover advantage to simply having released a work to market before anyone else could. Moreover, if the work is reasonably priced and attractively presented, there would be little reason for potential buyers to feel dissatisfied with it in a manner that would render it lucrative for competitors to enter the market.

For competitors, the investment of publishing the book and the considerable risk in competing with an established producer would cause them to think twice before undertaking this venture. Unless the original publisher has failed significantly in packaging, marketing, and pricing the book, its first-mover advantage is likely to last far into the future.

As for digital downloads of the book, considerable evidence exists that these do not cannibalize hard-copy sales. Indeed, book sales have skyrocketed since the emergence of easy copying possibilities on the Internet. Downloads likely also furnish a marginal gain to the author’s reputation in excess of the marginal costs of any revenue foregone directly due to a download – especially if those who download a book today would likely not have purchased it if it were not available for free online.

But suppose that the defenders of copyright are correct in their assumption that the first-mover advantage is ephemeral. Suppose that this advantage could not be relied on as the competition seized on a good work and began to market it at equally advantageous, or more-advantageous terms than the initial publisher. What other recourse could writers have?

1. More Frequent Publication of New Works

If there is a first-mover advantage that lasts several months or years, irrespective of whether intellectual property exists, then a given author who chooses to adhere to the “traditional” publishing system could pursue the strategy of writing and publishing a new work every time the first-mover advantage of the previous work has been exhausted. This would lead to a necessary change in expectations: an author could not expect to live off the royalties from a single work – even a widely popular work – forever but would need to keep creating in order to maintain his revenue stream.

Nonetheless, this is not far off from the current situation; after all, most published books do not sell nearly well enough to assure the authors even a modest stream of lifetime earnings. Moreover, such a system would incentivize creation of further works.

Indeed, prior to the introduction of copyright, European classical composers found it necessary to continually create music, as their older and already-famous pieces were often performed internationally without any compensation given to them. Even so, some of these composers managed to be phenomenally prosperous as well as prolific.

The most famous composer of the early 18th century, and one of the most prosperous, was Georg Philipp Telemann (1681-1767), who is thought by some to be the most prolific composer in human history, with over 3000 works to his name. Telemann’s status is rivaled by Simon Sechter (1788-1867), who wrote over 8000 works, many of them short fugues, and who endeavored to create at least one short composition every day. Neither composer lived under a copyright regime.

Indeed, virtually all of the big names of classical music – Bach, Vivaldi, Haydn, Mozart, Beethoven, Schubert, Chopin, Brahms, Berlioz – composed without copyright and were not dismayed when their works were performed without their participation or consent. Composers through the Romantic era would often borrow passages from their peers and predecessors and develop creative orchestrations and variations thereof. This was not considered to be theft but rather the ultimate compliment: a demonstration that a composer had been able to cultivate a musical idea that could now thrive independently of his efforts.

If composers could set still-unmatched records of productivity without copyrights while managing to earn a living, imagine what writers could do in an environment that did not give them the hope of forever subsisting off past accomplishments.

2. Larger Initial Advances

Writers seeking to publish their works via the “traditional” system could come, in an environment of no copyright, to expect larger initial advances from publishers as a tradeoff for smaller, less stable, and generally diminishing royalty streams. There is no reason why this could not be lucrative for publishers. The publisher could pay the writer a larger one-time fee, getting in exchange the first-mover advantage over the competition.

When the competition catches up and resorts to publishing a book that has been well received by the public, the original publisher has at least the potential of competing on even terms with regard to expenses; the competitors would not need to pay a substantial fraction of their earnings to the author, and neither would the original publisher.

The tremendous proliferation of British novels in the United States during the 19th century can give us a glimpse of what such a world might be like. British authors had copyright on their works in Britain since the enactment of the Statute of Anne in 1710, and American authors had copyright on their works in the United States since the passage of the Copyright Act of 1790.

However, as the era of international copyright had yet to be inaugurated (via the Berne Convention of 1886), British authors did not have copyright on their works in the United States; instead, they typically sold the rights to a first printing of their work in the United States. Thereafter, the original US publishers of these authors would not owe them royalties and would therefore not be obligated to pay this additional expense, putting them on par with potential later publishers of the same works. The British authors made more money selling their works in the US in this manner than they did under the copyright and royalty system in Britain. Moreover, their works became significantly more popular in the United States than those of their American contemporaries.

3. Patronage 2.0

Some of the greatest works in history have been created by writers and artists working under the patronage system, in which wealthy and influential individuals supported creators in exchange for a consistent and high-quality output, often used to advance the patrons’ interests and public image. The historical patronage system also exhibited numerous genuine flaws, including significant restrictions on the creativity of artists by overbearing patrons. Yet the flaws of the system were due not to the institution of patronage per se, but to the structure of preliberal, preindustrial Western societies.

Patrons were extremely scarce, and most of them had financial resources not due to personal merits or economic achievements, but due to political power. For writing in particular, this was a hindrance, as writing for a patron typically meant avoiding the expression of ideas that would upset the established political order, on which the patron built his wealth and power. On the other hand, if one’s patron was subversive of the established order, like the Earl of Shaftesbury (1621-1683), the patron and sole patient of John Locke, some radically provocative work could result.

Some creators were fortunate to find reasonable and enlightened patrons, but even these had idiosyncrasies that needed to be catered to. This bred extensive resentment of the patronage system and inspired a reaction and shift to its polar opposite: mass marketing to as broad a consumer base as possible. Yet this approach, too, has numerous evident shortcomings.

In our time, the fundamental flaws of the historical patronage system need no longer persist, because the distribution of potential patrons is so much greater. Indeed, most people who are established in “white-collar” occupations can afford to become patrons of the arts today. In addition, because of computers and the Internet, writing and publication cost very little except for the time and effort spent actually putting the words and ideas together. Not only has the capacity of most people to fund writers increased dramatically, but the exertions and materials required for writing have diminished considerably as well.

Any patronage system would necessitate some manner of creator compliance with the patron’s wishes; that is what the patron is paying for. However, with a large number of potential patrons on the market, a given writer does not need to feel dependent on financial arrangements with a particularly disagreeable patron; he is free to find another patron – or even to work for a multitude of patrons simultaneously.

Patronage can be expressed monetarily, but it need not be. In-kind patronage – such as that performed by numerous online magazines that publish essays by contributing authors – is another mechanism by which writers can find resources to support their endeavors.

4. Self-Patronage

“Self-patronage” is a concise way of expressing the concept of writing during one’s leisure time while pursuing another occupation as a primary income generator. If another person with an above-average income can serve as a patron for a writer, then it is just as easy for the writer himself to earn an above-average income in a profession of his choice and then use it to subsidize his writing.

This is a promising option for many writers today, myself included, and it should not be dismissed as a viable long-term model for the creation of quality output. Self-patronage is tremendously efficient; it frees the writer from having to get clearance from any external entity to write or publish what he pleases. Moreover, it frees the writer from needing to satisfy a mass audience; he can make his works as sophisticated, specialized, or controversial as he pleases. If they gain notice and admiration, this can result in some added bonuses for the writer; if they fail to catch on, he is not endangered in his livelihood and can always try again.

With the ability to publish for free on the Internet, writers no longer require access to large institutions or wealthy individuals in order to spread their ideas to a large audience. They do, of course, need to compete with a much larger pool of creators than has ever existed – and this may result in difficulties for quality work in getting notice commensurate with its merits. However, because self-patronage eliminates the costs of getting external clearance, a writer can be as productive as he is motivated to be. By releasing vast quantities of works, he greatly enhances the probability that one of these will be noticed and will motivate some readers to explore his other works.

5. Online-Content Sites

A remarkable development on the Internet in recent years has enabled hundreds of thousands of writers to earn modest income streams from advertisements that appear on the pages where their work is published. (In reading this section, some might wonder about the frequent mentions of my activity on the various sites to which I refer. This is done in part to comply with the Federal Trade Commission’s recent guidelines on the disclosure of writers’ institutional affiliations. Thank you, FTC, for requiring me to boast of my work more than I otherwise would have.) Large commercial websites typically contract with numerous advertisers and establish an infrastructure for writers to conveniently publish a variety of works. Associated Content, where I have been publishing my writings for over three years [2007-2010], [formerly paid] contributors both initial small advances for articles that pass editorial review and performance payments on the basis of how many page views contributors’ content receives. The performance payment is not enough to earn a living – $2.00 per 1000 page views – but several hundred articles can provide a decent supplement to one’s monthly income.

Helium.com, another site where I have published, [formerly invited] authors to write competing articles under a given title and then to rank other authors’ contributions. The authors who regularly participate [formerly received] a bonus based on the page views their articles receive. Yet another site, Today.com, the [former] host of my blog, The Progress of Liberty, [formerly paid] some bloggers a dollar for one post on any given day and supplements this with a performance payment based on visitation. Other commercial enterprises with a variety of compensation mechanisms have evolved over the last several years to enable layman writers to earn small revenues from their work without needing to have expertise in marketing or salesmanship.

The above methods of income generation, too, have their shortcomings in terms of which kinds of writing are most rewarded. But they are still in their infancy, and six years ago they did not exist at all. Within several decades at most, it will surely be possible for large numbers of authors to earn a living by writing and publishing their works on the Internet without being members of any syndicate or media organization’s staff – unless, that is, established interests successfully lobby governments for restrictions on creative Internet activities.

6. The Best Option

The best option for promoting a writer’s creativity while assuring him a stable and adequate income is a combination of the approaches above. Each approach, like most techniques in life, has its strengths and its shortcomings. For instance, patronage might result in the need to meet idiosyncratic tastes, while online-content sites that pay on the basis of unique visitors might incentivize writers to focus on breadth of appeal rather than depth. Self-patronage, on the other hand, is limited by the writer’s existing resources and technical training in other fields.

In a relatively advanced, quasi-market economy with widely available, remarkable publishing technologies, it is possible to viably combine these approaches for an overall strategy that keeps one both fed and writing. Moreover, as the marketplace continues to evolve, and technological possibilities combine with human creativity to render new options available, writers should be willing to experiment with yet more ways of delivering their content to audiences and receiving corresponding compensation.

As is typical with markets, it is virtually impossible to exactly predict the way in which patterns of behavior will emerge, especially as one looks out into the long-term future. But this should not discourage writers; indeed, it should highlight to them the importance of being open to new possibilities. They should not simply expect that existing business models – such as the copyright-based, royalty-heavy compensation system of “traditionally” published authors – will continue in perpetuity as a matter of right for the parties involved.

It is never necessary to cling to a single legal mechanism or institution as the sole path for any given peaceful and productive human activity. Human beings are much more inventive and resilient than the defenders of copyright would suggest.

Click here to read more articles in Issue CCXXXI of The Rational Argumentator.

Putting Randomness in Its Place (2010) – Article by G. Stolyarov II

Putting Randomness in Its Place (2010) – Article by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
Originally Published February 11, 2010
as Part of Issue CCXXXV of The Rational Argumentator
Republished July 22, 2014
******************************
Note from the Author: This essay was originally published as part of Issue CCXXXV of The Rational Argumentator on February 11, 2010, using the Yahoo! Voices publishing platform. Because of the imminent closure of Yahoo! Voices, the essay is now being made directly available on The Rational Argumentator.
~ G. Stolyarov II, July 22, 2014
***

A widespread misunderstanding of the meaning of the term “randomness” often results in false generalizations made regarding reality. In particular, the view of randomness as metaphysical, rather than epistemological, is responsible for numerous commonplace fallacies.

To see randomness as metaphysical is to see it as an inherent aspect of reality as such – as embedded inextricably in “the way things are.” Typically, people holding this view will take it in one of two directions. Some of them will see randomness pejoratively – thinking that there is no way reality could be like that: chaotic, undefined, unpredictable. Such individuals will typically posit that, because reality cannot be random, it must therefore be centrally planned by a super-intelligent entity, such as a deity.

Others, however, will use the metaphysical perception of randomness to deny evident and ubiquitously observable truths about our world: the facts that all entities obey certain natural laws, that these laws are accessible to human beings, and that they can inform our decision-making and actions. These individuals typically espouse metaphysical subjectivism – the idea that the nature of reality depends on the person observing it, or that all of existence is in such a chaotic flux that we cannot ever possibly make sense of it, so we might as well “construct” our own personal or cultural “reality.”

But it is the very metaphysical perception of randomness that is in error. Randomness is, rather, epistemological – a description of our state of knowledge of external reality, and not of external reality itself. To say that a phenomenon is random simply means that we do not (yet) have adequate knowledge to be able to explain it causally. Based on past observational experience or some knowledge of aspects inherent to that phenomenon, we might be able to assign probabilities – estimates of the likelihood that a particular event will occur, in the absence of more detailed knowledge about the specifics of the circumstances that might give rise to that event. In some areas of life, this is presently as far as humans can venture. Indeed, probabilistic thinking can be conceptually quite powerful – although imprecise – in analyzing large classes of phenomena which, individually, exhibit too many specific details for any single mind to grasp. Entire industries, such as insurance and investment, are founded on this premise. But we must not mistake a conceptual tool for an external fact; the probabilities are not “out there.” They are, rather, an attempt by human beings to interpret and anticipate external phenomena.

The recognition of randomness as epistemological can be of great aid both to those who believe in biological evolution and to advocates of the free market. Neither the laws of evolution, nor the laws of economics, of course, would fit any definition of “randomness.” Rather, they are impersonal, abstract principles that definitively describe the general outcomes of particular highly complex sets of interactions. They are unable to account for every fact of those interactions, however, and they are also not always able to predict precisely how or when the general outcome they anticipate will ensue. For instance, biological evolution cannot precisely predict which complex life forms will evolve and at what times, or which animals in a current ecosystem will ultimately proliferate, although traits that might enhance an animal’s survival and reproduction and traits that might hinder them can be identified. Likewise, economics – despite the protestations of some economists to the contrary – cannot predict the movements of stock prices or prices in general, although particular directional effects on prices from known technological breakthroughs or policy decisions can be anticipated.

Evolution is often accused of being incapable of producing intelligent life and speciation because of its “randomness.” For many advocates of “intelligent design,” it does not appear feasible that the complexity of life today could have arisen as a result of “chance” occurrences – such as genetic mutations – that nobody planned and for whose outcomes nobody vouched. However, each of these mutations – and the natural selection pressures to which they were subject – can only be described as random to the extent that we cannot precisely describe the circumstances under which they occurred. The more knowledge we have of the circumstances surrounding a particular mutation, the more it becomes perfectly sensible to us, and explicable as a product of causal, natural laws, not “sheer chance.” Such natural laws work both at the microscopic, molecular level where the proximate cause of the mutation occurred, and at the macroscopic, species-wide level, where organisms with the mutation interact with other organisms and with the inanimate environment to bring about a certain episode in the history of life.

So it is with economics; the interactions of the free market seem chaotic and unpredictable to many – who therefore disparage them as “random” and agitate for centralized power over all aspects of human life. But, in fact, the free market consists of millions of human actors in billions of situations, and each actor has definite purposes and motivations, as well as definite constraints against which he or she must make decisions. The “randomness” of behaviors on the market is only perceived because of the observer’s limited knowledge of the billions of circumstances that generate such behaviors. We can fathom our own lives and immediate environments, and it may become easier to understand the general principles behind complex economies when we recognize that each individual life has its own purposes and orders, although they may be orders which we find mistaken or purposes of which we disapprove. But the interaction of these individual microcosms is the free market; the more we understand about it, the more sensible it becomes to us, and the more valid conclusions we can draw regarding it.

The reason why evolution and economies cannot be predicted at a concrete level, although they can be understood, is the sheer complexity of the events and interactions involved – with each event or interaction possibly being of immense significance. Qualitative generalizations, analyses of attributes, and probabilistic thinking can answer some questions pertaining to these complex systems and can enable us to navigate them with some success. But these comprise our arsenal of tools for interpreting reality; they do not even begin to approach being the reality itself.

When we come to see randomness as a product of our limited knowledge, rather than of reality per se, we can begin to appreciate how much there is about reality that can be understood – rather than dismissed as impossible or inherently chaotic – and can broaden our knowledge and mastery of phenomena we might otherwise have seen as beyond our grasp.

Click here to read more articles in Issue CCXXXV of The Rational Argumentator.

When Zero’s Too High: Time Preference versus Central Bankers – Article by Douglas French

When Zero’s Too High: Time Preference versus Central Bankers – Article by Douglas French

The New Renaissance Hat
Douglas French
July 20, 2014
******************************

Central banking has taken interest rate reduction to its absurd conclusion. If observers thought the European Central Bank (ECB) had run out of room by holding its deposit rate at zero, Mario Draghi proved he is creative, cutting the ECB’s deposit rate to minus 0.10 percent, making it the first major central bank to institute a negative rate.

Can a central-bank edict force present goods to no longer have a premium over future goods?

Armed with high-powered math and models dancing in their heads, modern central bankers believe they are only limited by their imaginations. In a 2009 article for The New York Times, Harvard economist and former adviser to President George W. Bush, N. Gregory Mankiw, wrote, “Early mathematicians thought that the idea of negative numbers was absurd. Today, these numbers are commonplace.”

While this sounds clever, Ludwig von Mises undid Mankiw’s analogy long ago. “If he were not to prefer satisfaction in a nearer period of the future to that in a remote period,” Mises wrote of the individual, “he would never consume and enjoy.”

Carl Menger explained that it is “deeply imbedded in human nature” to have present desires satisfied over future desires. And long before Menger, A. R. J. Turgot wrote of the premium of present money over future money, “Is not this difference well known, and is not the commonplace proverb, ‘a bird in the hand is better than two in the bush,’ a simple expression of this notoriety?”

Central bankers can set a certain interest rate, but human nature cannot be eased away, quantitatively or otherwise. But the godfather of all central bankers, John Maynard Keynes, ignored time preference and focused on liquidity preference. He believed it was investments that yielded returns, and wrote, “Why should anyone outside a lunatic asylum wish to use money as a store of wealth?”

If liquidity preference determined the rate of interest, rates would be lowest during a recovery, and at the peak of booms, with confidence high, everyone would be seeking to trade their liquidity for investments in things. “But it is precisely in a recovery and at the peak of a boom that short-term interest rates are highest,” Henry Hazlitt explained.

Keynes believed that those who held cash for the speculative motive were wicked and central bankers must stop this evil. However, as Hazlitt explained in The Failure of the “New Economics,” holding cash balances “is usually most indulged in after a boom has cracked. The best way to prevent it is not to have a Monetary Authority so manipulate things as to force the purchase of investments or of goods, but to prevent an inflationary boom in the first place.”

Keynesian central bankers leave time out of their calculus. While they think they are lending money, they are really lending time. Borrowers purchase the use of time. Hazlitt reminds us that the old word for interest was usury, “etymologically more descriptive than its modern substitute.”

And as Mises explained above, time can’t have a negative value, which is what a negative interest rate implies.

Borrowers pay interest in order to buy present assets. Most importantly, this ratio is outside the reach of the monetary authorities. It is determined subjectively by the actions of millions of market participants.

Deep down, Mankiw must recognize this, writing, “The problem with negative interest rates, however, is quickly apparent: nobody would lend on those terms. Rather than giving your money to a borrower who promises a negative return, it would be better to stick the cash in your mattress. Because holding money promises a return of exactly zero, lenders cannot offer less.”

But still, he approvingly cites German economist Silvio Gesell’s argument for a tax on holding money, an idea Keynes himself approved of.

Keynesian central bankers are now central planners maintaining the unshakable belief that low interest rates put people back to work and solve every economic woe. “But in reality,” writes Robert Murphy, “interest rates coordinate production and consumption decisions over time. They do a lot more than simply regulate how much people spend in the present.”

Murphy points out that low rates stimulate some sectors more than others. Lower rates generally boost housing and car sales, for instance, while not doing much for consumer goods.

More than half a decade of zero interest rates has not lifted anyone from poverty or created any jobs—it has simply caused more malinvestment. It is impossible for the monetary authorities to dictate the proper interest rate, because interest rates determined by command and control bear no relation to the collective time preference of economic actors. The result of central bank intervention can only be distortions and chaos.

Draghi and Mankiw don’t seem to understand what interest is or how the rate of interest is determined. While it’s bad when academics promote their thought experiments, the foolish turns tragic when policymakers use the power of government to act on these experiments.

Douglas E. French is senior editor of the Laissez Faire Club and the author of Early Speculative Bubbles and Increases in the Supply of Money, written under the direction of Murray Rothbard at UNLV, and The Failure of Common Knowledge, which takes on many common economic fallacies.

This article was originally published by The Foundation for Economic Education.

Free Study Guide on Public-Choice Economics – Third Edition – by G. Stolyarov II

Free Study Guide on Public-Choice Economics – Third Edition – by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
July 3, 2014
******************************

The Third Edition of the popular Free Study Guide on Public-Choice Economics, prior editions of which have received over 31,000 views, is now available for download. Click here to download a free PDF copy of the Third Edition of this study guide.

This study guide covers 20 areas of public-choice theory and related topics in a question-and-answer format, with questions developed by Mr. Stolyarov on the basis on his notes taken in Stolyarovian Shorthand during the 2008 session of the Public Choice Economics course at Hillsdale College, taught by the renowned economist and professor, Dr. Gary Wolfram.

See more educational offerings in The Rational Argumentator’s section of Free Tools for Rational Education.

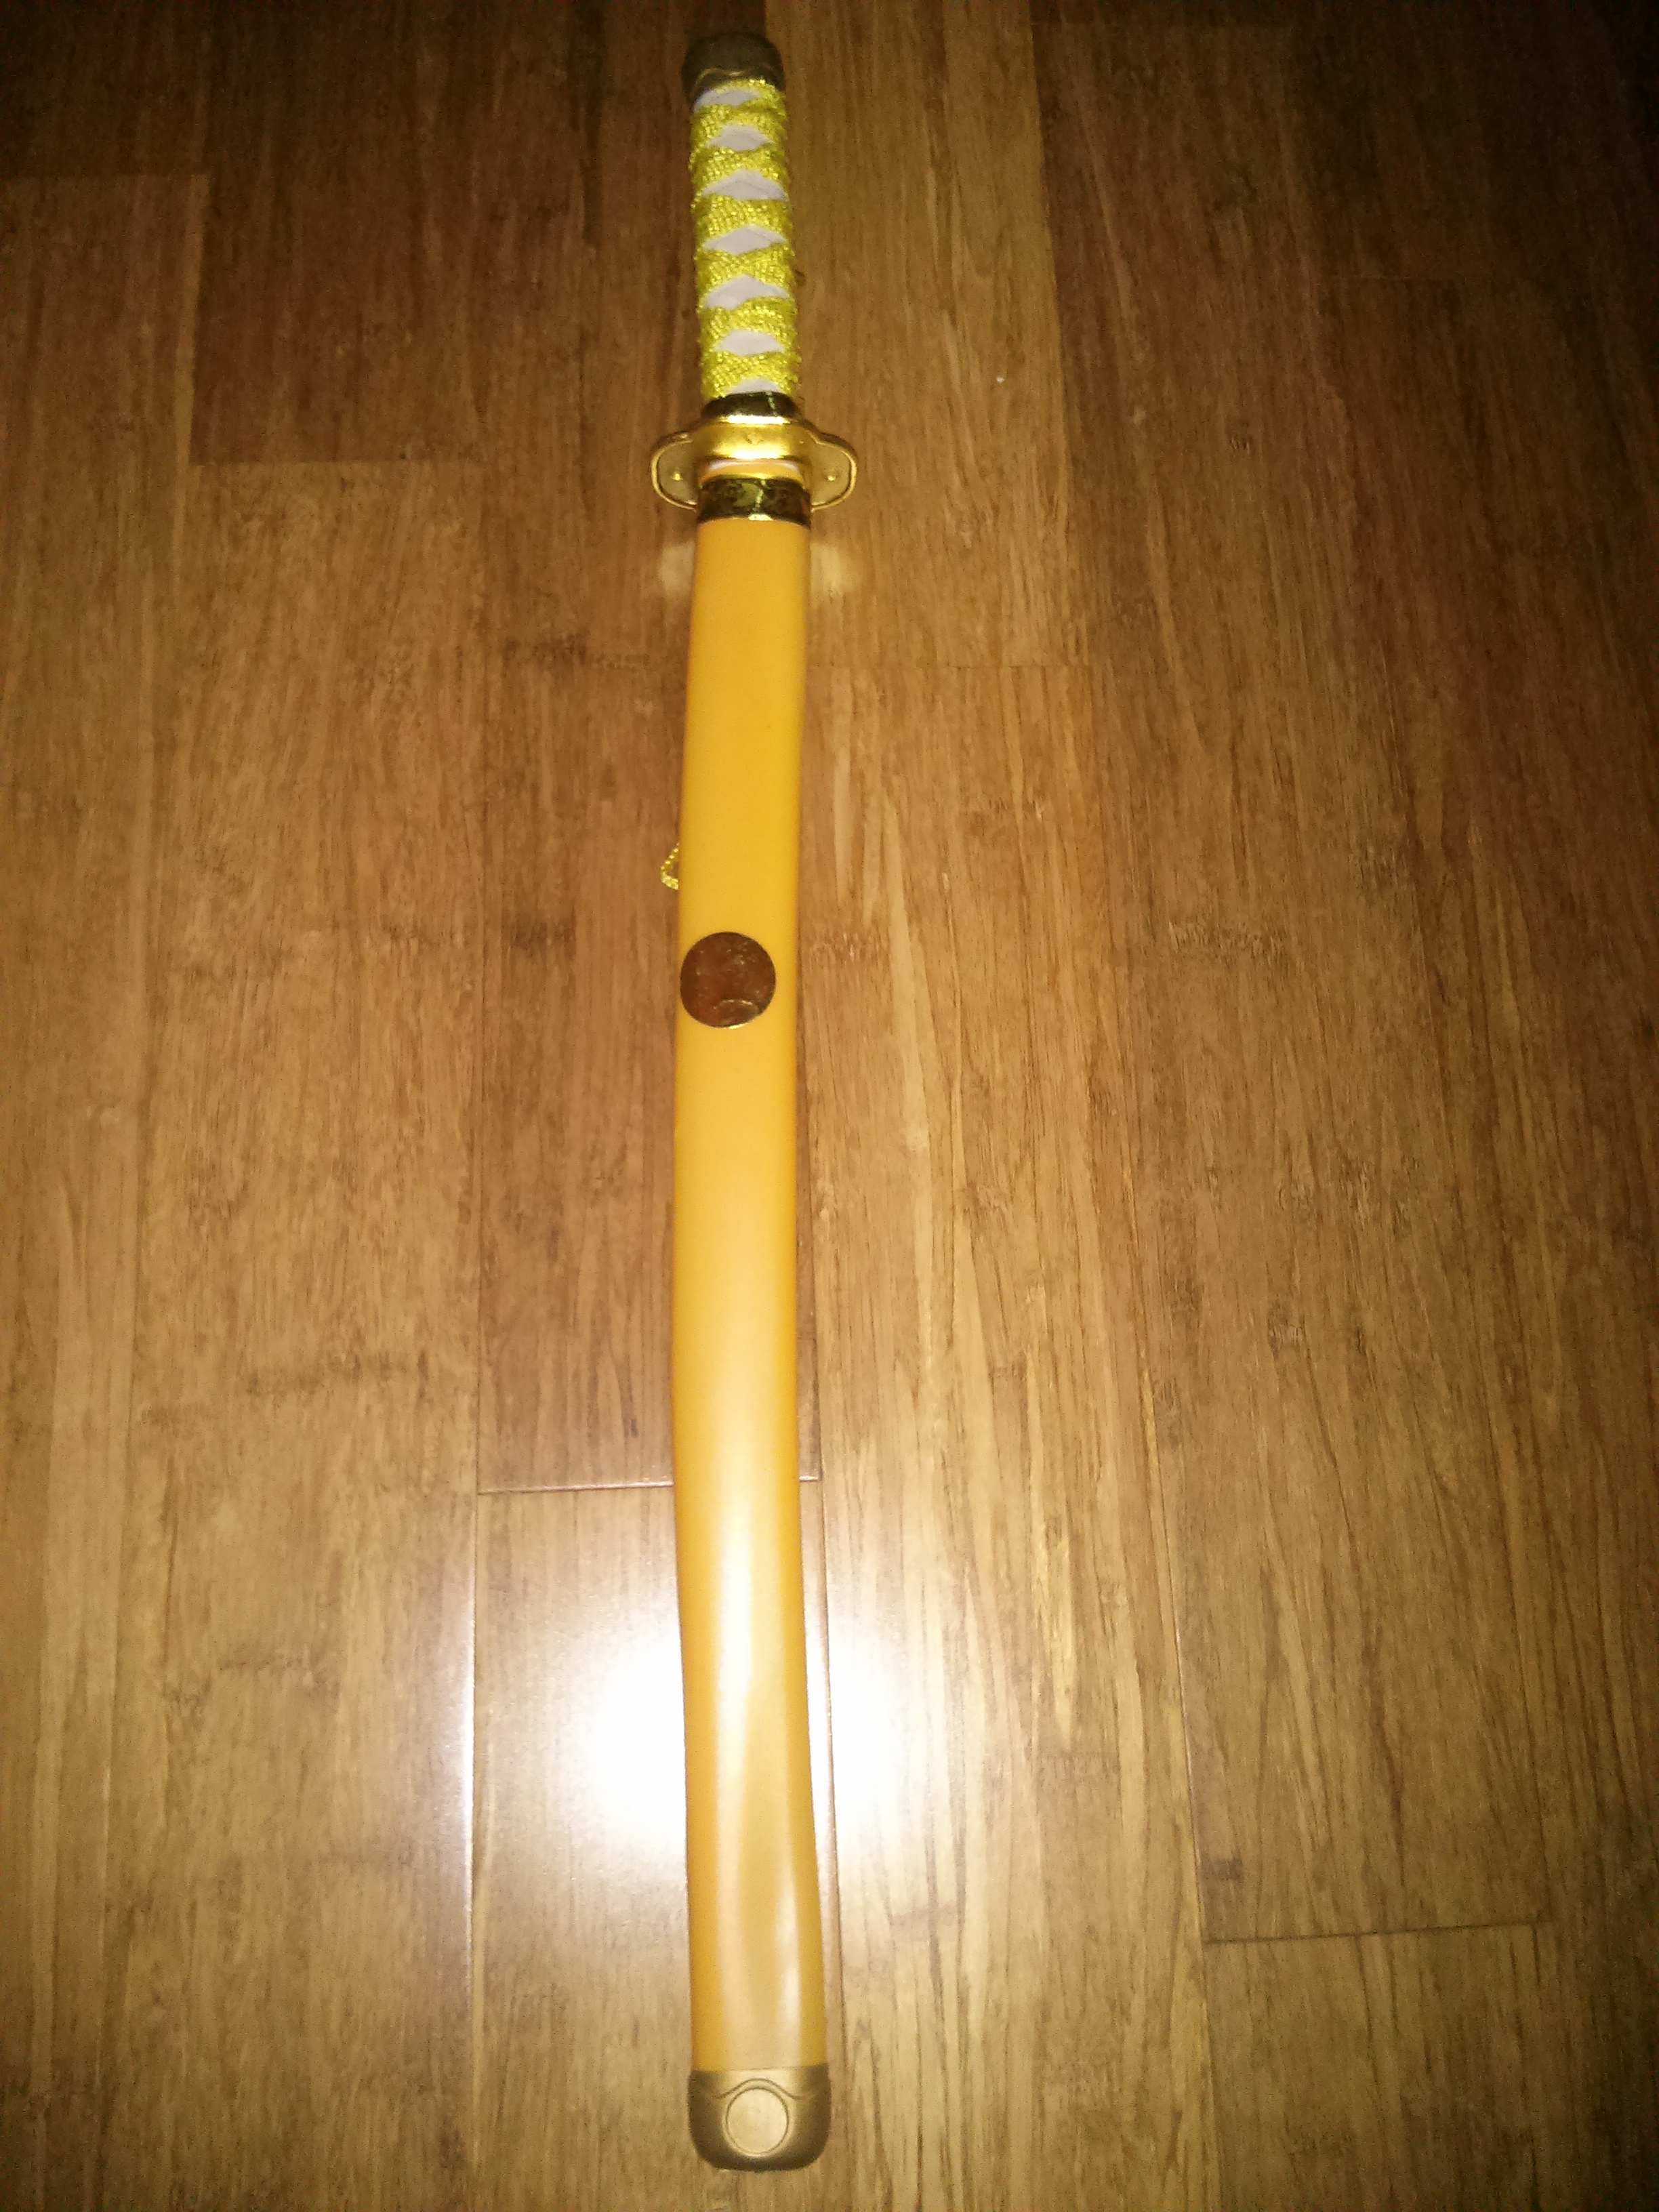
Ceremonial plastic sword, awarded to Mr. Stolyarov in 2008 for receiving the highest grade in Professor Gary Wolfram’s Public Choice Economics course at Hillsdale College.

Ceremonial plastic sword, awarded to Mr. Stolyarov in 2008 for receiving the highest grade in Professor Gary Wolfram’s Public Choice Economics course at Hillsdale College.

Heterogeneity: A Capital Idea! – Article by Sanford Ikeda

Heterogeneity: A Capital Idea! – Article by Sanford Ikeda

The New Renaissance Hat
Sanford Ikeda
June 26, 2014
******************************

When Thomas Piketty’s Capital in the 21st Century was released in English earlier this year it sparked vigorous debate on the issue of wealth inequality. Despite the prominence of the word in the title, however, capital has not itself become a hot topic. Apparently none of his defenders have taken the opportunity to explore capital theory, and, with a few exceptions, neither have his critics.

To prepare to read Mr. Piketty’s book I’ve been studying Ludwig Lachmann’s Capital and Its Structure, which, along with Israel M. Kirzner’s Essay on Capital, is among the clearest expositions of Austrian capital theory around. A hundred years ago the “Austrian economists”—i.e. scholars such as Eugen von Böhm-Bawerk who worked in the tradition of Carl Menger—were renowned for their contributions to the theory of capital. Today capital theory is still an essential part of modern Austrian economics, but few others delve into its complexities. Why bother?

Capital is Heterogeneous


Among the Austrians, Böhm-Bawerk viewed capital as “produced means of production” and for Ludwig von Mises “capital goods are intermediary steps on the way toward a definite goal.” (Israel Kirzner uses the metaphor of a “half-baked cake.”)  Lachmann then places capital goods in the context of a person’s plan: “production plans are the primary object of the theory of capital.” You can combine capital goods in only a limited number of ways within a particular plan. Capital goods then aren’t perfect substitutes for one another. Capital is heterogeneous.

Now, mainstream economics treats capital as a homogenous glob. For instance, both micro- and macroeconomists typically assume Output (Q) is a mathematical function of several factor inputs, e.g. Labor (L) and Capital (K) or

Q = f(L,K).

In this function, not only is output homogenous (whether we’re talking about ball-bearings produced by one firm or all the goods produced by all firms in an economy) but so are all labor inputs and all capital inputs used to produce them. In particular, any capital good can substitute perfectly for any other capital good in a firm or across all firms. A hammer can perfectly replace, say, a helicopter or even a harbor.

On the other hand, capital heterogeneity implies several things.

First, according to Mises, heterogeneity means that, “All capital goods have a more or less specific character.” A capital good can’t be used for just any purpose:  A hammer generally can’t be used as a harbor. Second, to make a capital good productive a person needs to combine it with other capital goods in ways that are complementary within her plan: Hammers and harbors could be used together to help repair a boat. And third, heterogeneity means that capital goods have no common unit of measurement, which poses a problem if you want to add up how much capital you have:  One tractor plus two computers plus three nails doesn’t give you “six units” of capital.

Isn’t “money capital” homogeneous? The monetary equivalent of one’s stock of capital, say $50,000, may be useful for accounting purposes, but that sum isn’t itself a combination of capital goods in a production process. If you want to buy $50,000 worth of capital you don’t go to the store and order “Six units of capital please!” Instead, you buy specific units of capital according to your business plan.

At first blush it might seem that labor is also heterogeneous. After all, you can’t substitute a chemical engineer for a pediatrician, can you? But in economics we differentiate between pure “labor” from the specific skills and know-how a person possesses. Take those away—what we call “human capital”—and then indeed one unit of labor could substitute for any other. The same goes for other inputs such as land. What prevents an input from substituting for another, other than distance in time and space, is precisely its capital character.

One more thing. We’re talking about the subjective not the objective properties of a capital good. That is, what makes an object a hammer and not something else is the use to which you put it. That means that physical heterogeneity is not the point, but rather heterogeneity in use. As Lachmann puts it, “Even in a building which consisted of stones completely alike these stones would have different functions.” Some stones serve as wall elements, others as foundation, etc. By the same token, physically dissimilar capital goods might be substitutes for each other. A chair might sometimes also make a good stepladder.

But, again, what practical difference does it make whether we treat capital as heterogeneous or homogenous? Here, briefly, are a few consequences.

Investment Capital and Income Flows


When economists talk about “returns to capital” they often do so as if income “flows” automatically from an investment in capital goods. As Lachmann says:

In most of the theories currently in fashion economic progress is apparently regarded as the automatic outcome of capital investment, “autonomous” or otherwise. Perhaps we should not be surprised at this fact: mechanistic theories are bound to produce results that look automatic.

But if capital goods are heterogeneous, then whether or not you earn an income from them depends crucially on what kinds of capital goods you buy and exactly how you combine them, and in turn how that combination has to complement the combinations that others have put together. You build an office-cleaning business in the hopes that someone else has built an office to clean.

There’s nothing automatic about it; error is always a possibility. Which brings up another implication.

Entrepreneurship


Lachmann:

We are living in a world of unexpected change; hence capital combinations, and with them the capital structure, will be ever changing, will be dissolved and re-formed. In this activity we find the real function of the entrepreneur.

We don’t invest blindly. We combine capital goods using, among other things, the prices of inputs and outputs that we note from the past and the prices of those things we expect to see in the future. Again, it’s not automatic. It takes entrepreneurship, including awareness and vision. But in the real world—a world very different from the models of too many economists—unexpected change happens. And when it happens the entrepreneur has to adjust appropriately, otherwise the usefulness of her capital combinations evaporates. But that’s the strength of the market process.

A progressive economy is not an economy in which no capital is ever lost, but an economy which can afford to lose capital because the productive opportunities revealed by the loss are vigorously exploited.

In a dynamic economy, entrepreneurs are able to recombine capital goods to create value faster than it disappears.

Stimulus Spending


As the economist Roger Garrison notes, Keynes’s macroeconomics is based on labor, not capital. And when capital does enter his analysis Keynes regarded it the same way as mainstream economics: as a homogeneous glob.

Thus modern Keynesians, such as Paul Krugman, want to cure recessions by government “stimulus” spending, without much or any regard to what it is spent on, whether hammers or harbors. (Here is just one example.)  But the solution to a recession is not to indiscriminately increase overall spending. The solution is to enable people to use their local knowledge to invest in capital goods that complement existing capital combinations, within what Lachmann calls the capital structure, in a way that will satisfy actual demand. (That is why economist Robert Higgs emphasizes “real net private business investment” as an important indicator of economic activity.)  The government doesn’t know what those combinations are, only local entrepreneurs know, but its spending patterns certainly can and do prevent the right capital structures from emerging.

Finally, no one can usefully analyze the real world without abstracting from it. It’s a necessary tradeoff. For some purposes smoothing the heterogeneity out of capital may be helpful. Too often though the cost is just too high.

Sanford Ikeda is an associate professor of economics at Purchase College, SUNY, and the author of The Dynamics of the Mixed Economy: Toward a Theory of Interventionism.
***
This article was originally published by The Foundation for Economic Education.
Natural Disasters Don’t Increase Economic Growth – Article by Frank Hollenbeck

Natural Disasters Don’t Increase Economic Growth – Article by Frank Hollenbeck

The New Renaissance Hat
Frank Hollenbeck
May 27, 2014
******************************

Hurricane season is nearly upon us, and every time a hurricane strikes, television and radio commentators and would-be economists are quick to proclaim the growth-boosting consequences of the vicissitudes of nature. Of course, if this were true, why wait for the next calamity? Let’s create one by bulldozing New York City and marvel at the growth-boosting activity engendered. Destroying homes, buildings, and capital equipment will undoubtedly help parts of the construction industry and possibly regional economies, but it is a mistake to conclude it will boost overall growth.

Every year, this popular misconception is trotted out although Frédéric Bastiat in 1848 clearly put it to rest with his parable of the broken window. Suppose we break a window. We will call up the window repairman, and pay him $100 for the repair. People watching will say this is a good thing. What would happen to the repairman if no windows were broken? Also, the $100 will allow the repairman to buy other goods and services creating income for others. This is “what is seen.”

If instead, the window had not been broken, the $100 may have purchased a new pair of shoes. The shoemaker would have made a sale and spent the money differently. This is “what is not seen.”

Society (in this case these three members) is better off if the window had not been broken, since we are left with an intact window and a pair of shoes, instead of just a window. Destruction does not lead to more goods and services or growth. This is what should be foreseen.

One of the first attempts to quantify the economic impact of a catastrophe was a 1969 book, The Economics of Natural Disasters. The authors, Howard Kunreuther and Douglas Dacy, largely did a case study on the Alaskan earthquake of 1964, the most powerful ever recorded in North America. They, unsurprisingly, concluded that Alaskans were better off after the quake, since money flooded in from private sources and generous grants and loans from the federal government. Again, this was “what is seen.”

While construction companies benefit from the rebuilding after a disaster, we must always ask, where does the money come from? If the funds come from FEMA or the National Flood Insurance Program (NFIP), the federal government had to tax, borrow, or print the money. Taxpayers are left with less money to spend elsewhere.

The economics of disasters remains a small field of study. There have been a limited number of empirical studies examining the link between growth and natural disasters. They can be divided into studies examining the short-term and long-term impact of disasters. The short-term studies, in general, found a negative relationship between disasters and growth while a lesser number of long-run studies have had mixed results.

The most cited long-run study is “Do Natural Disasters Promote Long-Run Growth?” by Mark Skidmore and Hideki Toya who examined the frequency of disasters in 89 countries against their economic growth rates over a 30-year period. They tried to control for a variety of factors that might skew the findings, including country size, size of government, distance from the equator and openness to trade. They found a positive relationship between climate disasters (e.g., hurricanes and cyclones), and growth. The authors explain this finding by invoking what might be called Mother Nature’s contribution to what economist Joseph Schumpeter famously called capitalism’s “creative destruction.” By destroying old factories and roads, airports, and bridges, disasters allow new and more efficient infrastructure to be rebuilt, forcing the transition to a sleeker, more productive economy. Disasters perform the economic service of clearing out outdated infrastructure to make way for more efficient replacements.

There are three major problems with these empirical studies. The first is counterfactual. We cannot measure what growth would have been had the disaster never occurred. The second is association versus causation. We cannot say whether the disaster caused the growth or was simply associated with it.

The third problem is what economists call “ceteris paribus.” It is impossible to hold other factors constant and measure the exclusive impact of a disaster on growth. There are no laboratories to test macroeconomics concepts. This is the same limitation to Rogoff’s and Reinhart’s work on debt and growth, and many other bilateral relationships in economics. Using historical data from the early 1900s, researchers found that as the price of wheat increased, the consumption of wheat also increased. They triumphantly proclaimed that the demand curve was upward sloping. Of course, this relationship is not a demand curve, but the intersection points between supply and demand. The “holding everything else constant” assumption had been violated. In economics, empirical data can support a theoretical argument, but it cannot prove or disprove it.

So what do we do if the empirical studies have serious limitations? We go back to theory. We know a demand curve is downward sloping because of substitution and income effects. Wal-Mart does not run a clearance to sell less output! Theory also holds that natural disasters reduce growth (i.e., the more capital destroyed, the greater the negative impact on growth).

More capital means more growth. Robinson Crusoe will catch more fish if he sacrifices time fishing with his hands to build a net. Now, suppose a hurricane hits the island and destroys all of his nets. Robinson could go back to fishing with his bare hands and his output would have been permanently reduced. He could suffer an even greater decline in output by taking time to make new nets. The Skidmore-Toya explanation is to have him apply new methods and technologies to build even better nets, allowing him to catch more fish than before the hurricane. Of course, we may ask, if he had this knowledge, why didn’t Robinson build those better nets before the hurricane? This is where the Skidmore-Toya logic falls apart. Robinson did not build better nets before the hurricane because it was not optimal for him to do so.

If a company decides to replace an old machine with a new one, among the primary considerations are the initial price of the new machine, the applicable interest rate, and the reduced yearly costs of operation of the new machine. Using net present value analysis, the company determines the optimum time to make the switch (a real option). A hurricane forces a switch to occur earlier than would have been optimal under a price and profit motive. The hurricane therefore created a different path for growth. The creative destruction would have occurred, but on a different, more optimal, timeline.

The same conclusions can also be drawn from manmade disasters. Contrary to what many Keynesian economists would have you believe, WWII did not grow the US out of the great depression. Capitalism did!

Frank Hollenbeck teaches finance and economics at the International University of Geneva. He has previously held positions as a Senior Economist at the State Department, Chief Economist at Caterpillar Overseas, and as an Associate Director of a Swiss private bank. See Frank Hollenbeck’s article archives.

This article was published on Mises.org and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.

Slogans or Science? – Article by Sanford Ikeda

Slogans or Science? – Article by Sanford Ikeda

The New Renaissance Hat
Sanford Ikeda
May 20, 2014
******************************

The debate over raising the legal minimum wage (LMW) to $10 an hour has people on both sides saying things they should know better than to say. For example, a friend recently posted the following meme (which isn’t the worst I’ve seen) on Facebook:

One year ago this week, San Jose decided to raise its minimum wage to $10/hour.

Any jobs disappear?

The number of minimum wage jobs has grown.

Any businesses collapse?

The number of businesses has grown.

Any questions?

Yes, several, but I’ll get to those in a bit.

Memes like these are just as silly and misleading as the simplistic arguments they’re probably attacking. In fact, the economic analysis of significantly raising the minimum wage says that, other things equal, it will reduce employment below the level where it would otherwise have been. It doesn’t say that that employment will fall absolutely or businesses will collapse.

A little thinking can go a long way

Have a look at this chart published in the Wall Street Journal. At first, it seems to support the simplistic slogans. But it’s important to compare similar periods, such as March–November 2012 (before the increase was passed) versus March–November 2013, (just after it went into effect). The LMW increase wasn’t a surprise, so in the months before it was passed, businesses would have been preparing for it, shaking things up. Comparing those two periods, which makes the strongest case for the meme’s assertions, the total percentage increase in employment (the area under the red line) looks pretty close, going just by my eyeballs and a calculator. In fact, the post-hike increase might actually be smaller, but you’d need more data to be sure. So if you compare similar periods, the rate of employment growth seems not to have been affected very much by the hike. So is the meme right?

According to that same chart and other sources, hiring in the rest of California and the country, where for the most part there was no dramatic increase in the LMW, was also on the rise at pretty much the same time. Why? Apparently, the growth rate of the U.S. economy jumped in 2012, especially in California. So the demand for inputs, including labor, probably also increased. I’m certainly not saying this correlation is conclusive, but you could infer that while hiring in San Jose was rising, it wasn’t rising as fast as it might have otherwise, given the generally improving economy.

That’s a more ambiguous result, and of course harder to flit into a meme.

You are stupid and evil and a liar!

Those strongly in favor of raising the LMW cast opponents as Republican apologists for big business. Take this post from DailyKos, which apparently is the source of the above meme. The author writes, “Empirically, there’s no clear negative effect that can be discerned. The concerns of Teahadists like Paul Ryan and Marco Rubio is [sic] rather unfounded in academic literature and in international assessments of natural experiments.”

Now, the overwhelming conclusion of years of economic research on the effects of a minimum wage on employment is that it tends to increase, not lower, unemployment. As this article from Forbes summarizes, “In a comprehensive, 182-page summary of the research on this subject from the last two decades, economists David Neumark (UC-Irvine) and William Wascher (Federal Reserve Board) determined that 85 percent of the best research points to a loss of jobs following a minimum wage increase.”

So, saying there is “no clear negative effect” is an outrageously ignorant claim. And there’s not one mention of the economic evidence that significantly raising the LMW will hurt the very people you wish to help: the relatively poor. But why address solid scientific research when there’s sloppy sloganeering by politicos to shoot down?

Attacking easy targets is understandable if you want to vilify your opponents or win an easy one for the cause. In that case, you take the dumbest statement by your rival as the basis of your attack. Such is the way of politics. In intellectual discourse, however, you may win the battle but you’ll lose the war. That is, if your goal is to learn from fruitful intellectual discussion, you must engage your opponent’s best arguments, not her weakest ones.

Let me use a counterexample. The sloganeering approach to attacking those who oppose raising the LMW is the equivalent of someone saying: “Well, this past winter was one of the coldest on record in the Midwest. So much then for global warming!” That may be “evidence” in a mud-slinging contest, but it’s not science.

What’s the theory?

While weather is complex and unpredictable, economic systems are even more so. Does that mean there are no principles of economics? Of course not. In fact, it’s because of such complexity that we need whatever help economic theory can offer to organize our thinking. And it doesn’t get any more basic than this: The demand curve for goods slopes downward.

That is, other things equal, the costlier something is, the less of it you’ll want to buy.

Note that the caveat—other things equal—is as important as the inverse relation between price and quantity demanded. That’s why my earlier back-of-the-envelope analysis had to be conditional on more data. Unfortunately, those data are often very hard to get. Does that mean we abandon the theory? Well, that would be like letting go of the rope you’re hanging on to for dear life because you’re afraid it might break.

So what exactly is the theory behind the idea that raising the LMW will increase hiring low-wage workers and boost business? If raising wages will actually increase employment and output, then why not also mandate a rise in interest rates, rents, electricity rates, oil prices, or the price of any of the other myriad factors of production that businesses ordinarily have to pay for? I would hope that this idea would give even the meme promoters pause.

As far as I know, the only situation in which forcing people to pay a higher wage rate will increase employment is when there is a dominant employer and there are barriers to competition. Economists term this “monopsony,” a situation that might occur in a so-called “factory town.” There, the dominant employer (of labor, capital, land, or whatever) can lower what she pays for inputs below the revenue that an additional unit of input earns the company. I would love to hear that argument and challenge it, because it’s the strongest one that standard economics can offer in favor of coercing businesses to raise wages. But so far I’ve not come across it, let alone any discussion of the economic literature on monopsony in the labor market, most of which questions its relevance. Some almost random examples are here and here.

Margins of analysis

Finally, economics teaches us that we can adjust to a particular change in different ways. In a thoughtful article on the effect of the LMW increase in San Jose that all sides of the debate should read, we get the following anecdote:

For his San Jose stores to make the same profit as before the wage increase, the same combo meal would be $6.75. “That would chase off a large percentage of my customers,” Mr. DeMayo said. He hasn’t laid off San Jose workers but has reduced their hours, along with some maintenance such as the drive-through lane’s daily hosing, and may close two unprofitable stores.

Employers can adjust to higher costs in one area by cutting back on spending in others. That might mean less unemployment than otherwise, but it doesn’t mean that raising the LMW has no negative employment effect at all. It means that the effects are harder to see. There’s that darn “other things being equal” again!

Slogans and memes are no substitute for science, or even clear thinking.

Sanford Ikeda is an associate professor of economics at Purchase College, SUNY, and the author of The Dynamics of the Mixed Economy: Toward a Theory of Interventionism.
***
This article was originally published by The Foundation for Economic Education.
Europe and Deflation Paranoia – Article by Frank Hollenbeck

Europe and Deflation Paranoia – Article by Frank Hollenbeck

The New Renaissance Hat
Frank Hollenbeck
April 30, 2014
******************************

There is a current incessant flow of articles warning us of the certain economic calamity if deflation is allowed to show its nose for even the briefest period of time. This ogre of deflation, we are told, must be defeated with the printing presses at all costs. Of course, the real objective of this fear mongering is to enable continued national-government theft through debasement. Every dollar printed is a government tax on cash balances.

There are two main sources of deflation. The first comes from a general increase in the amount of goods and services available. In this type of deflation, a reduction in costs, in a competitive environment, leads to lower prices. The high technology sector has thrived in this type of deflation for decades as technical progress (e.g., the effect of Moore’s Law) has powered innovations and computing power at ever-decreasing costs. The same was true for most industries during much of the nineteenth century, as the living standard increased considerably. Every man benefited from the increase in real wages resulting from lower prices.

The second source of deflation is from a reduction in the money supply that comes from an increase in the desire of the public or banking sectors to hold cash (i.e., hoarding).[1] An uncomplicated example will make this point clearer. Suppose we have 10 pencils and $10. Only at an equilibrium price of $1 will there be no excess output or excess money.

Suppose the production cost of a pencil is 80 cents. The rate of return is 25 percent. Now suppose people hoard $5 and stuff money in their mattress instead of saving it. The price of a pencil will be cut in half, falling from $1 to 50 cents, since we now have a money supply of $5 chasing 10 pencils. If input prices also fall to 40 cents per pencil then there is no problem since the rate of return is still 25 percent. In this example, a drop in output prices forced an adjustment in input prices.

The Keynesian fear is that input prices will not adjust fast enough to a drop in output prices so that the economy will fall into a deflation-depression spiral. The Keynesian-monetarist solution is to have the government print $5 to avoid this deflation.

Yet, this money creation is distortive and will cause a misallocation of resources since the new money will not be spent in the same areas or proportions as the money that is now being “hoarded” (as defined by Keynesians). Furthermore, even if the government could find the right areas or proportions, it would still lead to misallocations, since the hoarding reflects a desire to realign relative prices closer to what society really wants to be produced. The printing of money may actually increase the desire to hold cash, as we see today. Holding cash may be the preferred choice over consumption or investment (savings) when relative and absolute prices have been distorted by the printing press.

Of course, no one is really asking the critical questions. Why does holding more cash change the money supply, and why did the public and banks decide to increase their cash holdings in the first place?[2] Without fractional reserve banking, neither the public nor the banks could significantly change the money supply by holding more cash, nor could banks extend credit faster than slow-moving savings. The boom and ensuing malinvestments would be a thing of the past and, thus, so would the desire to hold more cash during the bust phase of the business cycle. If central banks are really concerned about this type of deflation, they should be addressing the cause — fractional reserve banking — and not the result. Telling a drunk that he can avoid the hangover by drinking even more whiskey is simply making the situation worse.[3] The real solution is to have him stop drinking.

According to the European Central Bank’s Mario Draghi,

The second drawback of low inflation … is that it makes the adjustment of imbalances much more difficult. It is one thing to have to adjust relative prices with an inflation rate which is around 2%, another thing is to adjust relative prices with an inflation rate which is around 0.5%. That means that the change in certain prices, in order to readjust, will have to become negative. And you know that prices and wages have a certain nominal rigidity which makes these adjustments more complex.

Draghi is confusing the first source of deflation with the second. The recent low inflation in the Euro zone can be attributed primarily to a strengthening of the Euro, and a drop in food and energy prices.

Economists at the Bundesbank must be quietly seething. They are obviously not blind to the ECB’s excuses to indirectly monetize the southern bloc’s debt. Draghi’s “whatever it takes” comment gave southern bloc countries extra time. Yet, little has been done to reign in the size of bloated public sectors. Debt-to-GDP ratios continue to rise and higher taxes in southern bloc countries have caused an even greater contraction of the private sector. Many banks in southern Europe are technically bankrupt. Non-performing loans in Italy have gone from about 5.8 percent in 2007 to over 15 percent today. And, the situation is getting worse.

Greece recently placed a five-year bond at under 5 percent which was eight times oversubscribed. This highlights the degree to which the financial sector in Europe is now dependent on the “Draghi put.” As elsewhere in the world, interest rates in Europe are totally distorted and no longer serve the critical function of allocating resources according to society’s time preference of consumption, or even reflect any real risk of default.

The ECB will likely impose negative rates shortly but will discover, as the Fed and others did before it, that you can bring a horse to water but cannot make him drink. QE will then be on the table, but unlike the Fed, the ECB is limited in the choice of assets it can purchase since direct purchase of Euro government bonds violates the German constitution. One day, Germany and the southern bloc countries, including France, will clash on what is the appropriate role of monetary policy.

Germany would be wise to plan, today, for a possible Euro exit.

Notes

[1] Keynesians view holding cash, and even holding savings in banks as “hoarding,” but properly understood, only the equivalent of stuffing money in a mattress is hoarding.

[2] Fractional-reserve lending is inflationary, thus contributing to inflationary booms. In turn, banks hold more cash when they fear a confidence crisis, which is also a result of the boom.

[3] Since inflationary fractional-reserve lending is a source of the problem, additional lending of the same sort is not the solution.

Frank Hollenbeck teaches finance and economics at the International University of Geneva. He has previously held positions as a Senior Economist at the State Department, Chief Economist at Caterpillar Overseas, and as an Associate Director of a Swiss private bank. See Frank Hollenbeck’s article archives.

This article was published on Mises.org and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.