Browsed by
Category: Economics

That Cold-Hearted Discipline – Article by David J. Hebert

That Cold-Hearted Discipline – Article by David J. Hebert

The New Renaissance Hat
David J. Hebert
November 6, 2013
******************************

But of all the duties of beneficence, those which gratitude recommends to us approach nearest to what is called a perfect and complete obligation. What friendship, what generosity, what charity, would prompt us to do with universal approbation, is still more free, and can still less be extorted by force than the duties of gratitude. —Adam Smith, The Theory of Moral Sentiments

A recent article by Wharton Professor Adam Grant has been popping up here and there, most recently in Psychology Today. Grant suggests that studying economics breeds greed, and he cites several studies to support his claim. The studies conclude economics professors give less money to charity than other professions, economics students are more likely to deceive others for personal gain, and people who study economics have less of a concern for fairness and tend to think that “greed” is okay.

To his credit, Grant does consider the alternative: that maybe economics actually attracts greedy people or that greedy people tend to thrive by studying economics. He dismisses these possibilities by noting that “there is evidence for selection . . . but this doesn’t rule out the possibility that studying economics pushes people further toward the selfish extreme.” He goes on to chide practitioners of the discipline for teaching self-interest in the classroom.

Finally, he concludes with four points that are meant to provide evidence of the social harm in studying economics, which can be summarized in two overarching points:

1) Economics justifies greedy behavior, and

2) Studying economics makes people less altruistic.

I want briefly to discuss these two points here.

Economics Justifies Greedy Behavior?

Studying economics, and specifically the role of incentives, teaches us that relying on altruism is a brave assumption that has but limited applicability. For example, among people we know, we can rely on a certain degree of altruism or benevolence. I know, for example, that my family and friends will be there for me not because I pay them to do so, but because they care about me. Similarly, they know I will be there for them. However, I don’t know the same thing about random people I encounter on the street.

And yet in order to enjoy the immense wealth that the division of labor affords us, society demands that we have interactions both with people we know well and people we do not know at all. These two distinct spheres of activity require two distinct forms of cooperation, which one might get from reading Adam Smith’s twin pillars of economics: The Theory of Moral Sentiments and The Wealth of Nations.

More tidily, perhaps, F. A. Hayek describes this situation in The Fatal Conceit by noting the difference between the macroeconomy and the microeconomy. Macro, in this context, refers to society as a whole, while micro refers to just the people to whom we are close. Hayek says that if we were to apply the same rules of the family unit to the macro, as would be the case if we were to allocate resources altruistically, we would destroy the macro. This is because there would be a complete lack of economic calculation, resources would be misallocated, and plans would fail to be coordinated (see these articles for more on economic calculation).

Hayek also notes that the reverse is true: If we were to apply the rules of the market to the family, we would destroy it as well. We don’t need prices and incomes at the dinner table to allocate the food. Even the most ardent defender of markets would agree that having prices and such as the means of allocating food at the dinner table would be wrong, just like paying your friends to help you move across town would be strange. (Beer and pizza don’t count.)

Instead, students of economics recognize not that greed is good, as the saying goes, but that greed can be transformed into the service of others given the proper institutional setting. That institutional setting, which has been thoroughly discussed elsewhere, is one that celebrates the role of property rights, prices, and profits (and losses) and recognizes their role in creating the incentives to properly husband resources, generates the information about the relative scarcities of various goods and transmits this information to consumers and producers in a quick and efficient manner, all of which provides a feedback mechanism to drive continued innovation.

Economics Makes People Less Altruistic?

Grant cites a 2005 article by Neil Gandal et. al. as concluding that “students who planned to study economics rated helpfulness, honesty, loyalty, and responsibility as just as important as students who were studying communications, political science, and sociology,” but that by the third year, economics students rated these values “significantly less important than first-year economics students.”

While the Gandal study does include such conclusions, it also includes much more. For example, economics students attribute less importance to fairness. Evidencing this, Gandal points out that, when questioned about the allocation of radio frequencies to different mobile-phone service providers, students who study economics are more likely to advocate selling the rights to the highest bidder while students of other disciplines are more likely to advocate for allocating the rights to “anybody who meets some minimal eligibility criteria.”

Students of economics do not advocate for property rights because we are greedy; we advocate for property rights because we understand and take seriously potential incentive problems in politics. The notion of minimal eligibility requirements may sound nice, for example, but problems may lie in who gets to draw that line, by what process that line gets drawn, and the incentives faced by the line-drawers. As Madison points out in Federalist 51, “If men were angels, no government would be necessary. If angels were to govern men, neither external nor internal controls on government would be necessary.”

Economics students know men are no angels. And as Nobel laureate James Buchanan points out, government officials are human beings, too, with their own hopes, dreams, and aspirations—and yes, forms of avarice. Supporting the allocation of resources to the highest bidder sidesteps the issues raised by these potential incentive problems. This means that the choice of how to allocate resources fundamentally comes down to a choice of institutions.

We can have a central authority establish guidelines by which anyone who wants can use the radio frequencies, or we can let the market decide. The former leads to a standard tragedy of the commons problem, whereby the radio frequency gets overused. In the case of cell phones, this means that the frequency would be crowded with multiple conversations simultaneously; imagine trying to shout to your friend across a crowded bar. The latter leads to the frequencies being allocated to the person who is best able to utilize them to serve the general population. So AT&T, for example, gets exclusive rights to a certain bandwidth and then tries to figure out how to best serve its customers. In this case, the customer gets to enjoy a clear phone call without the distraction of several other conversations in their ear simultaneously.

In any case, these are not examples of quelling altruism, but of keeping it in its place.

Less Greed, More Cooperation

Viewed in this light, economics does not so much teach greed but rather the beauty of cooperation. How else could we explain how a woolen coat gets made, how Paris gets fed, or how a pencil gets made? And if allocating, say, radio frequencies based on highest valued use makes people learn to discard fairness, well, how exactly is that a bad thing?

David Hebert is a Ph.D. student in economics at George Mason University. His research interests include public finance and property rights.

This article was originally published by The Foundation for Economic Education.

***

Editor’s Note by Gennady Stolyarov II: Mr. Hebert’s article is excellent in focusing on the true significance of economics and the need for private property rights. In one important respect, though, my position differs from his when it comes to the allocation of radio frequency to highest bidders such as AT&T and other entities exercising similar coercively granted monopoly and quasi-monopoly powers.

My position, arising out of similar libertarian principles, is that the allocation of radio frequencies to AT&T (and similar local/regional telecommunications monopolies) through the political process would not result in an economically optimal allocation, even if AT&T were the highest bidder. The reason for this is that AT&T’s very bidding ability arises out of (1) its decades-long history as the telephone monopoly in the United States and (2) the protections from competition that it enjoys in certain jurisdictions as a local or regional monopoly provider of certain services wrongly considered “natural monopolies” – such as high-speed cable services. In a pure free-market system, there would likely need to be some sort of allocation process for radio frequencies, so long as the use of radio frequencies by some parties has the physical ability to interfere with the use of the same frequencies by other parties. However, the outcome of such a free-market allocation process would differ considerably from the outcome of a bidding process in today’s status quo, conditioned by decades of deleterious path-dependency arising out of the privileges granted to AT&T and similar local/regional monopolists. Probably, an auction of radio spectrum on a purely free market would result in many smaller firms buying up many smaller ranges of spectrum and competing with one another more vigorously to provide superior customer service than do a handful of large, politically privileged telecommunications companies (AT&T, Comcast, Verizon, et al.) today. In this path-dependent, partially unfree environment it may be, in some cases, that allocations to lower bidders would result in better uses of resources and improved consumer outcomes, as long as institutional political privilege (e.g., enforced monopolies or historical insulation from competition) of the higher bidders can be incorporated into the bidding process in the form of some reasonable handicap used in considering their bids.

Inflation Has Not Cured Iceland’s Economic Woes – Article by David Howden

Inflation Has Not Cured Iceland’s Economic Woes – Article by David Howden

The New Renaissance Hat
David Howden
November 6, 2013
******************************

No two countries’ responses have polarized commentators over the past five years more than the contrasting post-crisis policies in Iceland and Ireland.

In a paper published in Economic Affairs (available here as a PDF) I contrast the policies enacted by Iceland and Ireland, perhaps the two countries most affected by the liquidity freeze of 2008. A common conclusion has been that one country did everything right and the other did everything wrong, however, I take a more pragmatic approach. There are some positive aspects in each case, and other aspects we can do without.

At the risk of over-simplifying their situations, the key policy differences are:

  1. Iceland allowed substantial swaths of its financial sector to collapse (mostly foreign-domiciled subsidiaries) while Ireland enacted blanket guarantees to keep its financial sector afloat.
  2. Iceland quickly inflated its krona in a bid to regain international competitiveness through depreciation. By being locked in the euro, Ireland was unable to pursue a similar path and instead had to become more attractive to foreigners by lowering its domestic prices (i.e., disinflation or outright deflation).
  3. Iceland stymied a capital flight by enacting monetary controls aimed at keeping investment within the country. By being part of the European Union, Ireland maintained its commitment to free capital markets, and investors were able to enter or exit as they pleased.

The evidence is mixed as to which solution was more effective. Iceland seems to have softened the immediate blow of its recession, but present growth in Ireland is stronger. In a similar way, unemployment in Iceland was less and still remains lower today.

For our purposes here, I want to focus just on the effects of their respective monetary policies, and how the short-term gains from Iceland’s inflationary response now pale in comparison to Ireland’s more subdued response.

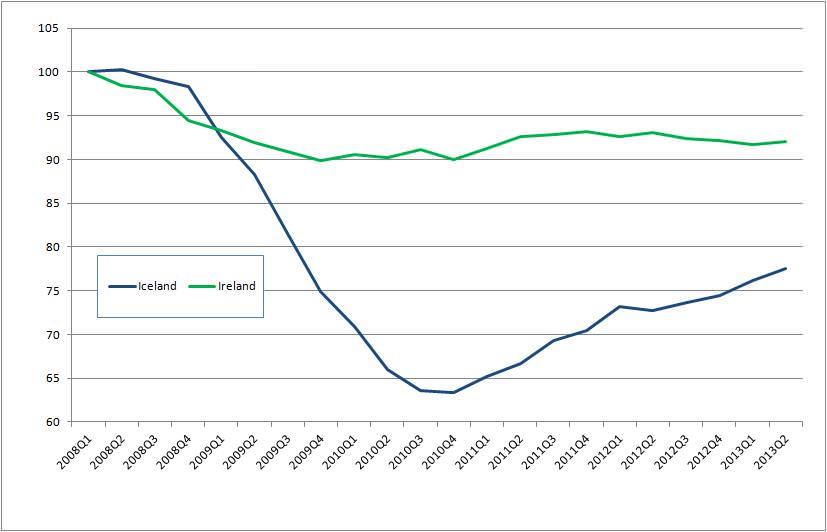
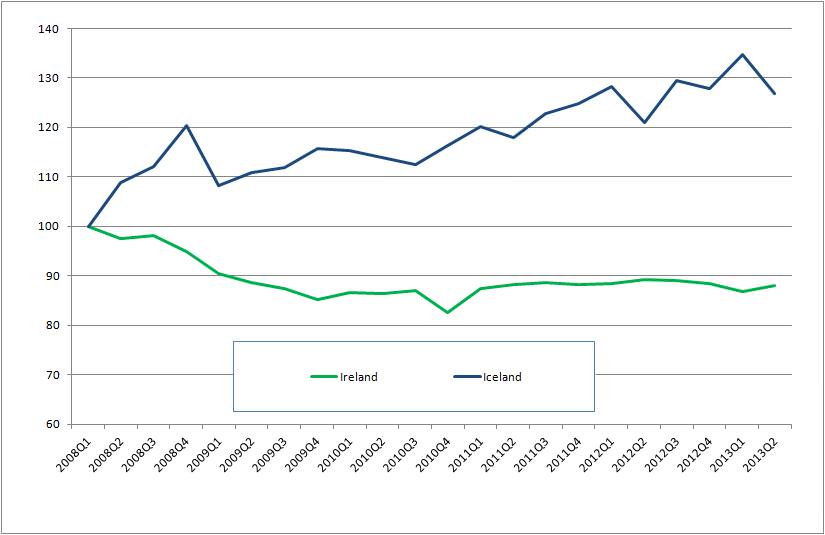
Figure 1: Nominal GDP (2008 = 100) Source: Federal Reserve Bank of St. Louis

Figure 1 shows the common story. Iceland’s inflationary policy stimulated exports, papered over some bad debts, and in general allowed it to exit the storm relatively unscathed. In contrast, Ireland is languishing in slow growth and five years later the country’s income is still 10 percent below its pre-bust peak.

Such an analysis neglects the pernicious effects of inflation on the Icelandic economy. This policy increased the money supply by almost 20 percent in 2008 alone, and lead to an immediate increase in prices.

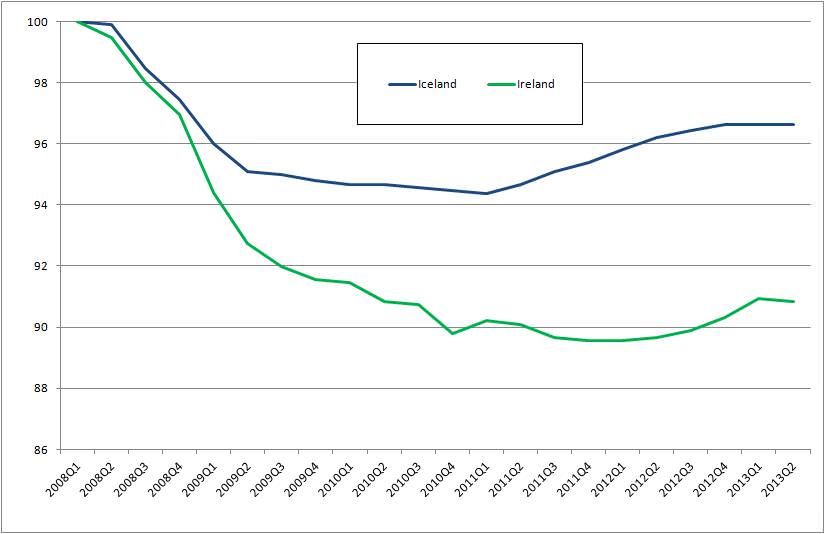
Figure 2: Real GDP (2008 = 100) Source: Federal Reserve Bank of St. Louis

In figure 2 we get a better feel for how the situation felt to the average Icelander or Irishman. As the Central Bank of Iceland inflated the money supply, price inflation raged. Icelanders continually felt their financial security worsen as their purchasing power collapsed. This was not apparent to the rest of the world, fixated as it was on the nominal prices the Icelandic economy posted. By its nadir in late 2010, inflation-adjusted income in Iceland was down over 35 percent.

In Ireland this decline was muted because of price deflation. As domestic prices fell it became easier for Irish citizens to make their declining nominal incomes go further. At its worst, the Irish economy collapsed less than 10 percent in real terms.

This seems to suggest that Ireland had the better solution by not pursuing an inflationary monetary policy. Some will note, however, that Iceland’s recovery since 2010 has been quite strong.

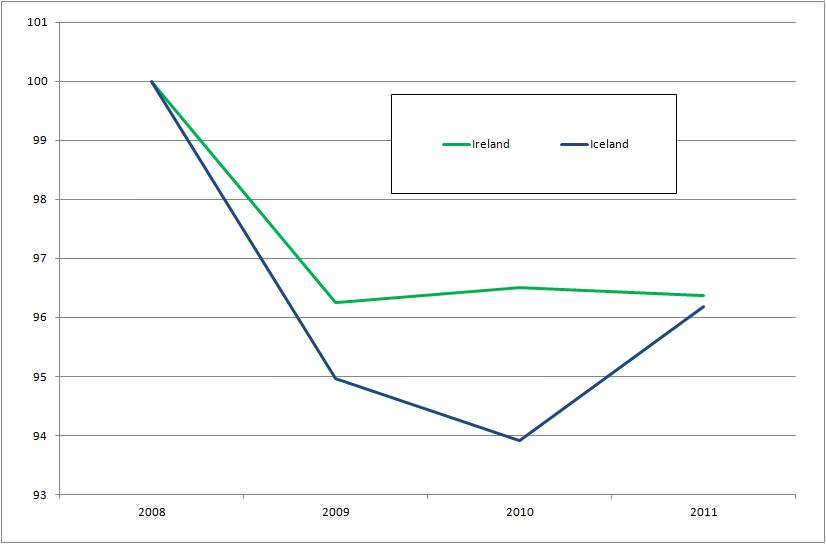
Indeed, if we look at the drop in the employment rate for both countries most probably feel more sympathy for the masses of unemployed Irishmen.

Figure 3: Employment rate (2008 = 1) Source: Federal Reserve Bank of St. Louis

Digging deeper, however, we find that not all is as it seems. Many Icelanders work two jobs to make ends meet. This effect was increasingly pronounced through the recession as inflation made it more difficult to get by with one salary. As a consequence, many Icelanders lost one job during the recession but the unemployment statistics did not reflect this as they were still employed elsewhere. This is notably not the case in Ireland, where not only is one job per worker the norm, but falling prices made it easier for an employed person to make ends meet as the recession continued.

A better way to gauge the employment situation is to look at changes in the hours worked.

Figure 4: Annual hours worked (2008 = 100) Source: Federal Reserve Bank of St. Louis

Here we can see the situation is reversed. By the recession’s trough in 2010 the number of hours worked by the average Icelander had fallen 6 percent while in Ireland the corresponding drop was only 3.5 percent — almost half as much.

Both countries still have problems. Iceland’s monetary controls are notably stifling needed investment, while Ireland is left with a large debt from bailing out its banks, and this is stalling growth. One thing is clear though — the effects of monetary policy are stark and the proclaimed benefits of Iceland’s inflationary policy were counteracted by the price inflation that ensued.

Don’t let a good crisis go to waste; learn something from it. As the tale of these two countries demonstrates, inflating one’s currency may give the appearance of recovery, but the truth is somewhat less rosy.

David Howden is Chair of the Department of Business and Economics and professor of economics at St. Louis University’s Madrid Campus, Academic Vice President of the Ludwig von Mises Institute of Canada, and winner of the Mises Institute’s Douglas E. French Prize. Send him mail. See David Howden’s article archives.

This article was published on Mises.org and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.

Longevity Logistics: We Can Manage the Effects of Overpopulation – Article by Franco Cortese

Longevity Logistics: We Can Manage the Effects of Overpopulation – Article by Franco Cortese

The New Renaissance Hat
Franco Cortese
November 5, 2013
******************************

This is a more popularly-oriented version of a scholarly article in review for the Journal of Evolution and Technology.

By far the most predominant criticism made against indefinite longevity is overpopulation. It is the first “potential problem” that comes to mind. But fortunately it seems that halting the global mortality rate would not cause an immediate drastic increase in global population; in fact, if the mortality rate dropped to zero tomorrow then the doubling rate for the global population would only be increased by a factor of 1.75 [1], which is smaller than the population growth rate during the post-WWII baby-boom.

Population is significantly more determined by birth rate than by death rate, simply because many people have more than one natural child.

This means that we should not see an unsustainable rise in population following even the complete cessation of death globally for a number of generations. We will run into problems 3 or 4 generations hence – but this leaves us with time enough to plan for overpopulation before we’re forced to resort to more drastic solution-paradigms like procreation-bans and space colonization.

Moreover, there are a number of proposed, and in some cases implemented, solutions to existing, contemporary problems that can be utilized for the purpose of minimizing overpopulation’s detrimental effects on living space and non-renewable resource constraints. These contemporary concerns include climate change and dependence on non-renewable energy sources, and they are only increasing in the amount of public attention they are attracting.

While these concerns and their potential solutions were not created by overpopulation or with overpopulation in mind, the potentially negative effects of an increasing global population can be effectively combated all the same using such contemporary methods and technologies.

Thus we can take advantage of the solution-paradigms developed for such contemporary concerns as climate change and dependence on non-renewable resources, and borrow from such movements as the sustainability movement and the seasteading movement, so as to better mitigate and effectively plan for the negative repercussions of a growing global population caused by the emergence of effective longevity technologies.

In a session with The President’s Council on Bioethics (as it was composed during the Bush Administration), S. Jay Olshansky [2] reported calculations he performed indicating that complete cessation of the global morality rate today would lead to less population growth than resulted from the post-WWII “Baby Boom”:

This is an estimate of the birth rate and the death rate in the year 1000, birth rate roughly 70, death rate about 69.5. Remember when there’s a growth rate of 1 percent, very much like your money, a growth rate of 1 percent leads to a doubling time at about 69 to 70 years. It’s the same thing with humans. With a 1 percent growth rate, the population doubles in about 69 years. If you have the growth rate — if you double the growth rate, you have the time it takes for the population to double, so it’s nothing more than the difference between the birth rate and the death rate to generate the growth rate. And here you can see in 1900, the growth rate was about 2 percent, which meant the doubling time was about five years. During the 1950s at the height of the baby boom, the growth rate was about 3 percent, which means the doubling time was about 26 years. In the year 2000, we have birth rates of about 15 per thousand, deaths of about 10 per thousand, low mortality populations, which means the growth rate is about one half of 1 percent, which means it would take about 140 years for the population to double.

Well, if we achieved immortality today, in other words, if the death rate went down to zero, then the growth rate would be defined by the birth rate. The birth rate would be about 15 per thousand, which means the doubling time would be 53 years, and more realistically, if we achieved immortality, we might anticipate a reduction in the birth rate to roughly ten per thousand, in which case the doubling time would be about 80 years. The bottom line is, is that if we achieved immortality today, the growth rate of the population would be less than what we observed during the post-World War II baby boom.

We would eventually run into problems, of course, a century down the road, but just so you know the growth rates would not be nearly what they were in the post-World War II era, even with immortality today.

In other words we will only have increased the doubling-time of the global population by a factor of 1.75 if we achieved indefinite longevity today (e.g., a doubling time of 140 years in 2000 compared to a doubling time of 80 years). This means that we will have two to four generations worth of time to consider possible solutions to growing population before we are faced with the “hard choice” of (1) finding new space and resources or else (2) limiting or regulating the global birthrate.

An alternate study on the demographic consequences of life extension concluded that “population changes are surprisingly slow in their response to a dramatic life extension”. The study applied “the cohort-component method of population projections to 2005 Swedish population for several scenarios of life extension and a fertility schedule observed in 2005,” concluding that “even for a very long 100-year projection horizon, with the most radical life extension scenario (assuming no aging at all after age 60), the total population increases by 22% only (from 9.1 to 11.0 million)” and that “even in the case of the most radical life extension scenario, population growth could be relatively slow and may not necessarily lead to overpopulation.” [2]. The total population increase due to the complete negation of mortality given by this study is significantly lower than the figure calculated by Olshansky.

Finding innovative solutions to new and old problems is what humanity does. We have a variety of possible viable options to increase the resources and living space available to humanity already. Moreover, there are several other contemporary concerns that are invoking the development of technological and methodological solutions that can be applied to our own concerns regarding the effects of overpopulation. Surely we can conceive of optimal solutions to these problems (and the more pressing a given problem is, the more funding it receives and the faster the solution to it is accomplished) – and take advantage of the growing methodological and technical infrastructure being developed for related and convergent problems – within the time it will take to feel overpopulation’s effect on living space and resources.

We could, for instance, colonize the oceans [3, 4, 5], drawing from the engineering, construction techniques used to build, maintain, and safely inhabit contemporary VLFSs (Very Large Floating Structures). 75% of the Earth’s surface area is, after all, water. This would increase our potential living space 3-fold – and I say “potential” because we surely don’t currently maximize living space on the 25% of the Earth’s surface occupied by land. Furthermore, humanity has as yet barely ventured beyond the surface of the earth – which is a sphere after all. There is nothing to prevent society building higher and building deeper. Indeed, with contemporary and projected advances in materials science and structural engineering, there is no theoretical limit to the height of structures we can safely build – the space elevator being a case in point. And while there will indeed be a maximum size wherein building higher becomes economically prohibitive (a limit determined to a large extent by the materials used), contemporary megastructures [6] indicate that very large structures can be built safety and cost-effectively. Underground living [7, 8, 9, 10] is another potential solution-paradigm as well; underground structures require less energy, are protected from weathering effects and changing temperatures to a much greater extent than structures exposed to the elements, and are less susceptible to damage from natural disasters. Furthermore, there are a number of underground cities in existence today [11], with existing techniques and technologies used to better facilitate contemporary underground living, which we can take advantage of.

In fact, the problem of limited living space is a contemporary problem for certain nations like Japan, and active projects to combat this growing problem have already been undertaken in many cases. This means that there will be an existing host of solutions, with their own technological and methodological infrastructures, which we can benefit from and take advantage of when the problematizing effects of growing global population become immediate. Not only can we take advantage of the existing engineering methodologies developed for use in the construction of VLFSs, but we can also take advantage of the growing body of knowledge pertaining to megastructural engineering and even existing proposals for floating cities [12, 13, 14, 15, 17, 18]. Another possible solution is artificial islands [19].

Furthermore, in recent years the topic of Very Large Floating Structures [21, 22] has experienced a surge of renewed interest occurring in tandem with the increasing interest in seasteading [23, 24], – that is, the creation of very-large-floating-structures for reasons of political sovereignty as well as to allow corporations to get around the laws of a given nation by occupying an area outside of exclusive economic zones. This renewed interest can only increase the amount of attention and funding these concepts receive, in turn increasing the viability of VLFS designs and their underlying structural-engineering and energy-production concerns.

Another contemporary movement that will prove advantageous for our own concerns with the effects of overpopulation on living space, working space, and resource space is the growing green movement and sustainability movement. The problem of resource scarcity is already upon us in many areas, and there exists contemporary motivation for finding more resource-efficient ways of making energy and producing goods, and for lessening our dependency on non-renewable energy sources. Climate change has only become an increasingly predominant concern in international politics, and many incentives exist to lessen our dependence on non-renewable energy sources as well as to lessen the environmental impact of contemporary civilization, which is itself another oft-touted problematic concern possibly resulting from overpopulation. Developments in these areas are only set to continue, for reasons wholly unrelated to the effects of overpopulation, and when those effects come to the fore we will have a collection of existing methodologies that can then be harnessed to lessen the impact of overpopulation on living space and resource scarcity.

The predominance of these problems, as well as the amount of attention and funding they are expected to receive (and thus the viability of their potential solutions), will only increase as we move forward into the future. The solutions we have to the potential problems of overpopulation – namely resource scarcity and lack of living space – will not only increase as the effects of overpopulation get closer, but the technological and methodological infrastructures underlying those solutions will also become more tried, tested, and robust, fueled by contemporary concerns over decreasing living space, climate-change and resource scarcity.

While space colonization is the most frequently proffered technological solution to the possibility of future overpopulation, I think we will turn to various Earth-bound solutions to increasing humanity’s available living space, as well as the space available for agricultural labs, that is the manufacture of food-stuffs, or indoor farming systems [25, 26, 28], before colonizing the cosmos becomes an economically optimal option. I think these sorts of solutions will be employed long before humanity is forced to either regulate the birthrate or move into the cosmos.

Moreover, people who wish to have children will have incentive to support politicians running on policies promoting new solutions to decreasing living space. Consider the number of U.S. taxpayer dollars spent during the Space Race, with no immediate material or scientific benefit (other than to prove it could be done, as well as to maintain rough militaristic equality with the USSR to some extent, as the state of rocket technology was indicative of the state of ballistic technologies like missiles). If humanity is forced to choose between having children and receiving the medical treatments that will keep them from dying, surely people will be motivated to fund initiatives and projects aimed at solving the problems of decreasing living space and increasing resource constraints due to a growing global population.

It is important to remember that the largest increase in life expectancy we have experienced historically was followed by a drastic decrease in birthrate over the next few generations thereafter. Before the Industrial Revolution, English women had on average 6 children. In 2000 the average was less than 2.

Figure 1: Fertility Rates in England, 1540-2000
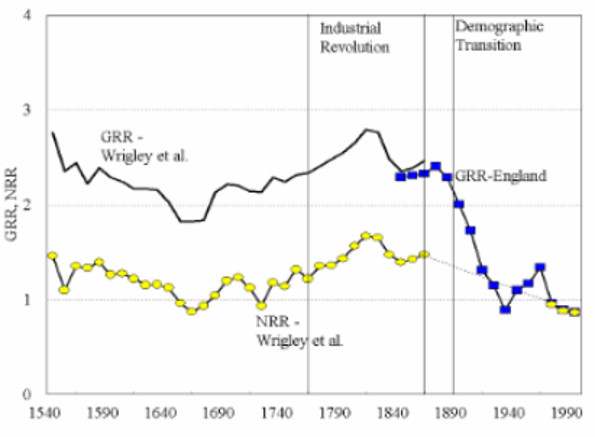
Note: GRR = Gross Reproduction Rate, NRR = Net Reproduction Rate
Source: Wrigley et al. (1997) p. 614. Office of National Statistics, United Kingdom.

The drop in birthrate following the industrial revolution has several causes. Chief among them is the fact that children were considered to some extent as assets, helping with maintaining the family livelihood, often by doing agricultural work on a family farm or helping with household chores (which were much more extensive then). Another large determining factor is a high rate of child mortality; thus families would have multiple children in anticipation of losing some to death. But with a rise in living conditions, the child mortality rate dropped drastically – and as a result we stopped having more kids in anticipation of some of them dying. Moreover, we started treating children less as assets and more as people to nurture and raise for their own sake. Longer lives, and less susceptibility to death in general, appears to have made us better parents.

Thus it is not only possible but probable that we will see a similar drop in the birthrate as a consequence of a significant future increase in average lifespan, with people having children much later in life, when they are more financially stable and when they have done all the commitment-free things they’ve always wanted to do. Without a looming limit on one’s available reproductive lifespan, there will be no pressing motivation to have children “before it’s too late” – and this alone could very well facilitate an unprecedented decrease in the Total Fertility Rate (TFR) of the global population.

Evidence indicates that the drop in birth rate was neither limited to England, nor an isolated result of the Industrial Revolution. A net drop in the TFR seems to be a longer-term trend concurrent across the globe. It is likely that the drop in the TFR is due to the same factors as the drop in birth rate following the Industrial Revolution – increasing life expectancy and continually improving living conditions allow people to have children without expecting a portion of them to be lost to death, to have them for the sake of having children rather than as assets to aid in maintaining the family livelihood, and to have children later in life due to the increase in one’s reproductive lifespan that comes with increasing life expectancy. The fact that the drop in TFR is not an isolated historical event is advantageous because the global population is affected by birth rate much more than by the mortality rate. Hence we may see a continuing decrease in the TFR occur in tandem with increasing life expectancy, leveling out the imbalance created by a mortality rate of zero by a larger than has been heretofore anticipated. (Source: U.S. Central Intelligence Agency, World Factbook.)

Let us suppose, for a moment, the worst: that indefinite longevity is achieved and we completely ignore (i.e., fail to plan for) overpopulation until its effects start becoming readily apparent. Even in this seeming worst-case scenario, overpopulation is not likely to result in any great tragedies. In such a case we would be forced to limit the global birthrate until we are able to implement the solutions that would allow us to sustainably procreate again. If people have a strong enough desire to continue having children, then they will express their demand and politicians will consequently base their policies upon deliberative initiatives to increase available living and agricultural space – and get elected if the desire to freely procreate is strong and widespread enough. Failing to plan for overpopulation will simply be a wake-up call, letting us know that we should have been planning for its effects from the beginning, and that we had better start planning for them now if we want to continue to freely procreate.

Thus while overpopulation is the most prominent and most credible criticism against continually increasing lifespans, and the one that needs to be planned for the most (because it will eventually happen, but it will lead to sustainability, resource, and living-space problems only if we do nothing about it), it is in no way insoluble, nor particularly pressing in terms of the time available to plan and implement solutions to shrinking living space and resource space (i.e., the space occupied by resources such as food, energy production, workplaces, etc.). We have a host of potential solutions today, ones we can use to increase available living space without regulating the global birthrate, and decades following the achievement of indefinite lifespans to consider the advantages and disadvantages of the various possible solutions, to develop them and to implement them.

So then: where to from here? Overpopulation is still the most prominent criticism raised against indefinite longevity, and if combated, the result could be an increase in public support for the Longevity movement. You might think that the widespread concern with overpopulation due to increasing longevity won’t really matter, if they turn out to be wrong, and overpopulation isn’t so insoluble a problem as one is inclined to first presume. But this misses a crucial point: that the time it takes to achieve longevity is determined by and large by how strongly and in how widespread a manner society and the members constituting it desire and demand it. If we can convince people today that overpopulation isn’t an insoluble problem, then continually increasing longevity might happen much sooner than otherwise. At the cost of 100,000 deaths due to age-correlated causes per day, I think hastening the arrival of indefinite longevity therapies by even a modest amount is somewhat imperative. Hastening its arrival by one month will save 3 million lives, and achieving it one year sooner than otherwise will save an astounding 36.5 Million real, human lives.

Thus, we should work toward putting more concrete numbers to these estimates. How much more living space can be feasibly created by colonizing the oceans? How deep can we really dig, build and live? How high can we safely build? Is there a threshold height or depth where building higher or deeper becomes too economically prohibitive to be worth the added living, working or resource space? What are the parameters (e.g., material strength/cost ratio, specific structural design) determining such a threshold?

First, we need to collect and analyze the feasibility studies that have already been undertaken on floating cities, artificial islands, VLFSs and the new solution-paradigms that are emerging to combat the contemporary concerns of sustainability and resource scarcity. In short, we need to compile data from the feasibility studies that have already been done, and the projects already implemented. Then we need to plan and commission further feasibility studies, undertaken by engineers and geologists, to build upon the work already accomplished in feasibility studies pertaining to existing designs for floating cities and other Very Large Floating Structures. We need to put some numbers to the cost the additional space for food, resources, work and living necessitated by widely available life-extension therapies. We need to do some hard calculations to show that the effects of overpopulation are problems that can be solved using existing megascale engineering and construction techniques and materials, safely and economically. We need to show the world that it has more space than it ever thought it had, and that such solution-paradigms as cosmic colonization and procreative regulation are neither the only ones, nor necessarily the most optimal ones. We need, in short, to show them that, in this case, where there’s a will there’s a way, and that the weight of waiting is too high a price to pay.

Franco Cortese is a futurist, author, editor, Affiliate Scholar at the Institute for Ethics & Emerging Technologies, Ambassador at The Seasteading Institute, Affiliate Researcher at ELPIs Foundation for Indefinite Lifespans, Fellow at Brighter Brains Institute, Advisor at the Lifeboat Foundation (Futurists Board Member and Life Extension Scientific Advisory Board Member), Director of the Canadian Longevity Alliance, Activist at the International Longevity Alliance, Canadian Ambassador at Longevity Intelligence Communications, an Administrator at MILE (Movement for Indefinite Life Extension), Columnist at LongeCity, Columnist at H+ Magazine, Executive Director of the Center for Transhumanity, Contributor to the Journal of Geoethical Nanotechnology, India Future Society, Serious Wonder, Immortal Life and The Rational Argumentator. Franco edited Longevitize!: Essays on the Science, Philosophy & Politics of Longevity, a compendium of 150+ essays from over 40 contributing authors.

References:

  1. Presidents Council for Bioethics: Transcripts (December 12, 2002): Session 2: Duration of Life: Is There a Biological Warranty Period? 01.
  2. L. A. Gavrilov and N.S. Gavrilova. “Demographic Consequences of Defeating Aging”. Rejuvenation Research. 2010 April; 13(2-3): 329–334.
  3. Ibid.
  4. McCullagh, Declan. “Seasteaders” Take First Step Toward Colonizing The Oceans.” CBS News, October 9, 2009. 02
  5. Pasternack, Alex. “Bioengineer aspires to colonize the sea.” CNN, January 12, 2011. 03
  6. Banham, Reyner. Megastructure: urban futures of the recent past. London: Thames and Hudson, 1976.
  7. Tsuchiyama, Ray. “Ocean Colonies as Next Frontier.” Forbes, April 24, 2011. Accessed August 1, 2013. 04
  8. “Inside Underground Cities.” Before Its News. 2013 March. 05
  9. South, D. B., and Freda Parker. “Underground Homes – Good or Bad?” Monolithic, January 22, 2009. 06.
  10. Good Earth Plants & Greenscaped Buildings. “Underground Living.” Last modified May 6, 2013. 07.
  11. Kelly, J. “10 Amazing Underground Cities”. Listverse.com. January 22, 2013. Accessed August 1, 2013. 08
  12. Gammon, Katharine. “Building Artificial Islands That Rise With Sea.” PopSci, June 8, 2012. 09
  13. Cottrell, Claire. “A Survey of Futuristic Floating Cities.” FlavorWire, November 2, 2012. 10
  14. “Cities on the Ocean.” Technology Quarterly – The Economist. Q4 2011.
  15. Bonsor, Kevin. “How the Floating Cities Will Work.” HowStuffWorks. n.d. 11.
  16. DigInfo TV. “GREEN FLOAT – a Floating City in the Sky.” Accessed August 6, 2013. 12.
  17. National Geographic. “Pictures: Floating Cities of the Future.” Accessed August 6, 2013. 13.
  18. Emerging Technology News. “Self-Sufficient Floating Cities Planned for 2025: Japan.” Accessed August 6, 2013. 14.
  19. “An artificial island in Hambantota.” News.LK, August 2, 2013. 15
  20. Goodier, Rob. “The World’s 18 Strangest Man Made Islands.” Popular Mechanics, n.d. 16
  21. E. Watanabe, C.M. Wang, T. Utsunomiya and T. Moan. “Very Large Floating Structures: Applications, Analysis and Design”. CORE Report No. 2004-02. Centre for Offshore Research and Engineering National University of Singapore. 17
  22. C.M. Wang, and Z. Tay. Very Large Floating Structures: Applications, Research and Development. In The Proceedings of the Twelfth East Asia-Pacific Conference on Structural Engineering and Construction — EASEC12. Edited by LAM Heung Fai. Singapore: Department of Civil Engineering, National University of Singapore Kent Ridge, 2011. 18
  23. World Architecture News. “Seasteading, United States.” Accessed August 6, 2013. 19
  24. The Seasteading Institute. The Seasteading Institute Annual Report 2008. Rep. n.p., n.d.
  25. Nagy, Attila. “14 High-Tech Farms Where Veggies Grow Indoors.” Gizmodo, June 17. 20.
  26. Meinhold, Bridgette. “Indoor Vertical Farm ‘Pinkhouses’ Grow Plants Faster With Less Energy.” Inhabitat. Last modified May 23, 2013. 21.
  27. TerraSphere. “Urban farming 2.0: No soil, no sun.” Accessed August 1, 2013. 22.
  28. The Vertical Farm Project – Agriculture for the 21st Century and Beyond. “Vertical Farm Designs.” Accessed August 6, 2013. 23

 

Libertarians and Voting – Article by Alex Salter

Libertarians and Voting – Article by Alex Salter

The New Renaissance Hat
Alex Salter
November 5, 2013
******************************

While it’s often dangerous to make blanket statements about sociopolitical movements, it’s not a stretch to say libertarians have a contentious relationship with voting.

Many libertarians don’t vote at all, and cite positive (as opposed to normative) reasons for doing so. The standard argument goes something like this: Voting in an election is costly, in the sense that it takes time that could have been used doing something else. However, in the vast majority of elections—and probably all elections that matter for who gets to determine significant aspects of policy—each individual vote, taken by itself, is worthless. The voting populace is so large that the probability that the marginal vote affects the outcome of the election is virtually zero. To the extent that one votes solely for the sake of impacting the outcome of elections, the costs of voting outweigh the expected benefits, defined as the probability one’s vote is decisive multiplied by the payoff from having one’s preferred candidate win. A really big payoff, multiplied by zero, is zero.

This argument is a staple of the academic literature in political economy and public choice. It’s used to explain many phenomena, the most prominent of which is rational ignorance. Since each individual’s vote doesn’t matter, no individual has any incentive to become informed on the issues. As such, voters acting rationally remain largely uninformed. As an explanation for an observed phenomenon in political life, it is impeccably reasoned and extremely useful for academic research. However, as an explanation for why individual libertarians refrain from voting, it is potentially quite dangerous.

Voting is a quintessential collective-action problem. Policy would be more libertarian at the margin if libertarians showed up en masse to vote on election day. But for each individual libertarian voter, voting is costly. Furthermore, the benefits of a more libertarian polity are available to each libertarian whether he votes or not. Each libertarian potential voter thus acts according to his own self-interest and stays home, even though if some mechanism were used to get all libertarians to vote, each of them would be better off.

Why is using this argument for abstaining from voting dangerous?  The answer lies in a significant reason why libertarians are libertarians. Many who are not libertarians advocate government provision of goods and services such as roads or education on the grounds that collective-action problems would result in these goods and services being undersupplied. Libertarians rightly respond that this is nonsense. History is full of examples of privately supplied roads and education, not to mention more difficult cases. The existence of a collective-action problem is not a sufficient argument for government intervention. To believe otherwise is to ignore the creative and imaginative capacities of individuals engaging in private collective action to overcome collective-action problems.

Every time a libertarian points to the collective-action problem as a reason for abstaining from voting, he weakens, at least partially, the argument that individuals in their private capacity can overcome these kinds of problems. By suggesting we cannot overcome a relatively simple collective-action problem like voting, our illustrations of ways other collective-action problems have been solved privately, and arguments for how such problems might be solved privately going forward, may appear disingenuous.

Looking at the problem more closely, there are all sorts of ways libertarians can solve the collective-action problem associated with voting. Libertarians could meet throughout the year in social groups dedicated to furthering their education by, say, reading Human Action together, and follow up such meetings with dinner parties or social receptions. The price tag for admission to such groups could be meeting at a predetermined time and place on Election Day and voting. This coupling of mild political activism with other desirable activities is an example of bundling, a very common mechanism by which collective goods and services have been privately supplied throughout history.

At this point, a few caveats are in order.

First, this potential solution is irrelevant for those who refuse to engage in the political process for ethical reasons. A libertarian could find the current popular interpretation of the “social contract” so unacceptable that any engagement in the political process cannot be justified. Second, even after deriving mechanisms for overcoming the voting collective-action problem, individuals’ opportunity cost of participating exceeds the expected benefit. Academics who are libertarians — who must spend significant time engaging highly technical scholarly literature to further their careers — would be most likely to cite this argument, and they may very well be right to do so. Third, organizing “voting clubs” large enough to have a chance of mattering for election outcomes may itself be prohibitively costly. Such is most likely to be true in national elections.

But if these reasons or others are why libertarians abstain from voting, they should say so. Citing the collective-action problem by itself is not enough, and it undermines the argument that purposeful human actors can overcome collective-action problems through voluntary association.

Alex Salter is a Ph.D. student in economics at George Mason University.

This article was originally published by The Foundation for Economic Education.
Why Do Banks Keep Going Bankrupt? – Article by Kirby R. Cundiff

Why Do Banks Keep Going Bankrupt? – Article by Kirby R. Cundiff

The New Renaissance Hat
Kirby R. Cundiff
November 4, 2013
******************************

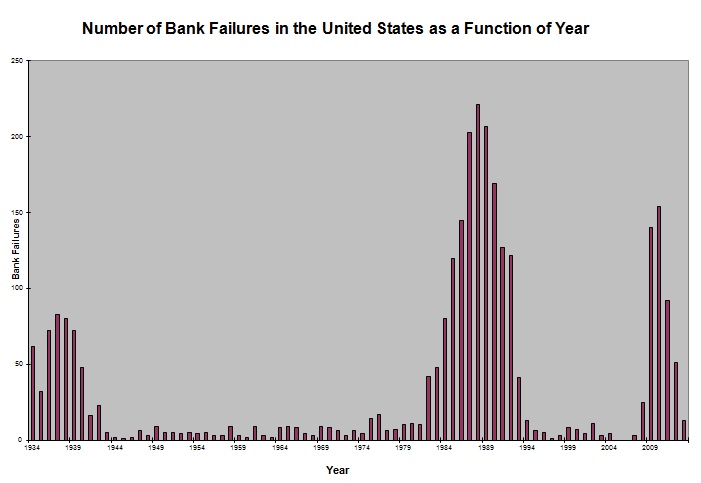
The banking industry is unstable. Banks are regularly going bankrupt. Crises in the banking industry have occurred in three distinct time periods during the twentieth century—during the Great Depression of the 1930s, during the Savings and Loan crisis of the 1980s and 1990s, and during the Great Recession from 2007 to present.

Why the banking industry is so vulnerable to bankruptcies and what can be done to correct this problem?

Debt to assets, or leverage, ratios vary significantly from industry to industry. They are typically under ten percent in most high tech industries and go up to forty percent for public utilities. Average debt ratios in the banking and financial services industry are in the fifty to seventy percent range, however, and many banks have much higher leverage ratios.

Firms attempt to minimize their total financing costs or Working Average Cost of Capital (WACC). The component costs of capital (cost of debt and cost of equity) are determined by investors’ perceptions of the risk and return possibilities associated with buying debt or equity in a given company or individual.

A credit card loan has a higher interest rate than a home loan because the credit card loan is riskier—i.e. there are no assets to seize if the money is not paid back. Similarly, a high-risk company normally pays a higher interest rate on its debt than a lower-risk company and increasing leverage is normally associated with increasing risk. Due to deposit insurance, however, this isn’t the case with banks.

Moral Hazard

The Federal Deposit Insurance Corporation (FDIC) insures deposits up to $250,000 in the United States. Most of the European countries (including Cyprus) have similar organizations that insure deposits up to 100,000 EUR. (See Deposit Insurance.)

Since depositors believe that their bank accounts are insured by governments, they do not generally know or care how much risk banks incur when they invest their depositors’ money. This creates a moral hazard problem with very little oversight by depositors of a bank’s management of their assets. Bank managers can take a lot of risk and, if they make profits, they keep the money. If they lose money, the taxpayers pay for the losses. In theory, this moral hazard problem is mitigated by subordinated debt, investors with deposits over the deposit insurance limit, and banking regulations. But these approaches are clearly not working.

In a series of agreements called the Basel Accords, the Basel Committee on Bank Supervision (BCBS) provides certain recommendations on banking regulations in regards to capital risk, market risk and operational risk. The purpose of these accords is to ensure financial institutions have enough capital to meet their obligations. The Tier I and Tier II capital controls of the Basel Agreements are supposed to prevent banks from taking too much risk with depositors’ assets. Tier 1 capital consists largely of shareholders’ equity. Tier 2 capital comprises undisclosed reserves, revaluation reserves, general provisions, hybrid instruments and subordinated debt.

The capital ratios are:

  •   Tier 1 capital ratio = Tier 1 capital / Risk-adjusted assets
  •   Total capital (Tier 1 and Tier 2) ratio = Total capital (Tier 1 + Tier 2) / Risk-adjusted assets
  •   Leverage ratio = Tier 1 capital / Average total consolidated assets

To be well-capitalized under federal bank regulatory definitions, a bank holding company must have a Tier 1 capital ratio of at least six percent, a total capital ratio of at least ten percent, and a leverage ratio of at least five percent (Capital).

The leverage ratios allowed under the Basel agreements are far higher than the typical leverag ratios in most industries and are far higher than would exist in a free-market financial system. Under a free-market system, depositors would not put their money in overly-leveraged banks and banks would be forced to decrease their leverage ratios and behave more like mutual or money market funds. Banks would be less likely to use short-term liabilities (deposits) to fund long-term assets (loans).

The S&L Crisis

Massive bank leverage would not create as much instability if the money supply was stable as in the 1800s under the gold standard. Under the current debt-is-money system, inflation and interest rates can vary wildly from year to year. The Savings and Loan Associations (S&Ls) made many low interest 30-year fixed rate home loans when inflation was low in the 1960s—five percent interest rate loans were typical. As inflation increased, the S&Ls still had these long-term home loans on their books, but the market now demanded higher interest rates on deposits (eighteen percent at times). The interest rates that many savings and loans were receiving on their assets (30-year fixed rate loans) were much lower than the interest rates the same S&Ls were paying on their liabilities (deposits). This duration mismatch resulted in the mass insolvency of the Savings and Loan Industry and a bailout of the S&Ls by the American tax payers exceeding $100 billion.

The Great Recession

The banking defaults of the Great Recession (2007 to present) were also caused by unstable interest rates combined with high leverage. The Federal Reserve lowered rates in the early 2000s to stimulate the economy after the bursting of the dot.com bubble. This resulted in many people borrowing money at very low interest rates to buy homes. Then the Federal Reserve raised interest rates and many people were no longer able to make their home payments. Again the result was massive bank insolvency and a substantial decrease in home values. Another huge taxpayer -funded bailout of the banking system followed, and the Federal Reserve has been printing money ever since, trying to stimulate the economy in the wake of yet another bubble it created.  The disbursements associated with placing into conservatorship government-sponsored enterprises Fannie Mae and Freddie Mac by the U.S. Treasury, the Troubled Asset Relief Program (TARP), and the Federal Reserve’s Maiden Lane Transactions are probably around $400 billion. How much of these disbursements will be paid back is currently unclear.

During the recent crises in Cyprus, proposals were seriously considered to ignore the 100,000 EUR deposit insurance and seize a fraction of even small depositors’ money. Most depositors lost access to their accounts for over a week and large depositors are still likely to lose a large fraction of their assets. This crisis has made some depositors more likely to pay attention to the solvency of their banks, but most depositors still believe that deposit insurance will cover any possible losses. If banks are to become more stable, the amount of equity relative to debt in the banking system must be drastically increased to something resembling what it would be without government deposit insurance, central bank subsidies, and treasury bailouts. Given the lobbying power of bankers in Washington, DC and around the word, such is unlikely to occur. The boom-bust cycle of banking bubbles followed by banking crises will most surely continue.

For further reading on this topic see this from The Freeman.

Kirby R. Cundiff, Ph.D. is an Associate Professor of Finance at the Rochester Institute of Technology. He is a Chartered Financial Analyst and a CERTIFIED FINANCIAL PLANNERTM Professional. 

This article was originally published by The Foundation for Economic Education.


Economies are Not Destroyed in a Day – Article by Nicolás Cachanosky

Economies are Not Destroyed in a Day – Article by Nicolás Cachanosky

The New Renaissance Hat
Nicolás Cachanosky
October 26, 2013
******************************

Earlier this month, Argentina’s leading conservative paper, La Nación published an unsigned editorial comparing the economies of Argentina and Venezuela. The editorial concluded that as economic freedom declines in Argentina, and as Argentina adopts more of what Chavez called “twenty-first century socialism,” it is becoming increasingly similar to Venezuela. Is this true? Will Argentina suffer the same fate as Venezuela where poverty is increasing and toilet paper can be a luxury?

The similarities of regulations and economic problems facing both countries are indeed striking in spite of obvious differences in the two countries. Yet, when people are confronted with the similarities, it is common to hear replies like “but Argentina is not Venezuela, we have more infrastructure and resources.”

Institutional changes, however, define the long-run destiny of a country, not its short-run prosperity.

Imagine that Cuba and North Korea became, overnight, the two most free-market, limited-government countries in the world. The two countries would have immediately gained civil liberties and economic freedom, but they would still have to accumulate wealth and to develop their economies. The institutional change affects the political situation immediately, but a new economy requires time to take shape. For example, as China opened parts of its economy to international markets, the country started to grow, and we are now seeing the effects of decades of relative economic liberalization. It is true that many areas in China continue to lack significant freedoms, but it would be a much different China today had it refused to change its institutions decades ago.

The same occurs if one of the wealthiest and developed countries in the world were to adopt Cuban or North Korean institutions overnight. The wealth and capital does not vanish in 24 hours. The country would shift from capital accumulation to capital consumption and it might take years or even decades to drain the coffers of previous accumulated wealth. In the meantime, the government has the resources to play the game of Bolivarian (i.e., Venezuelan) populist socialism and enjoy the wealth, highways, electrical infrastructure, and communication networks that were the result of the more free-market institutional realities of the past.

Eventually, though, highways start to deteriorate from the lack of maintenance (or trains crash in the station killing dozens of passengers), the energy sector starts to waver, energy imports become unavoidable, and the communication network becomes obsolete. In other words, economic populism is financed with resources accumulated by non-populist institutions.

According to the Fraser Institute’s Economic Freedom of the World project, Argentina ranked 34th-best in the year 2000. By 2011, however, Argentina fell to 137, next to countries like Ecuador, Mali, China, Nepal, Gabon, and Mozambique. There is no doubt that Argentina enjoys a higher rate of development and wealth than those other countries. But, can we still be sure that this will be the situation 20 or 30 years from now? The Argentinean president is known for having said that she would like Argentina to be a country like Germany, but the path to becoming like Switzerland or Germany involves adopting Swiss and German-type institutions, which Argentina is not doing.

The adoption of Venezuelan institutions in Argentina, came along with high growth rates. These growth rates, however, are misleading:

First, economic growth, properly speaking, is not an increase in “production,” but an increase in “production capacity.” The growth in observed GDP after a big crisis is economic recovery, not economic growth properly understood.

Second, you can increase your production capacity by investing in the wrong economic activities. Heavy price regulation, as takes place in Argentina (now accompanied by high rates of inflation), misdirects resource allocation by affecting relative prices. We might be able to see and even touch the new investment, but such capital is the result of a monetary illusion. The economic concept of capital does not depend on the tangibility or size of the investment (i.e, on its physical properties), but on its economic value. When the time comes for relative prices to adjust to reflect real consumer preferences, and the market value of capital goods drops, capital is consumed or destroyed in economic terms even if the physical qualities of capital goods remains unchanged.

Third, production can increase not because investment increases, but because people are consuming invested capital, as is the case when there is an increase in the rate that machinery and infrastructure wear out.

I’m not saying that there is no genuine growth in Argentina, but it remains a fact that a nontrivial share of the Argentinean GDP growth can be explained by: (1) recovery, (2) misdirection of investment, and (3) capital consumption. If that weren’t the case, employment creation wouldn’t have stagnated and the country’s infrastructure should be shining rather than falling into pieces.

Most economists and policy analysts seem to have a superficial reading of economic variables. If an economy is healthy, then economic variables look good, GDP grows, and inflation is low. But the fact that we observe good economic indicators does not imply that the economy is healthy. There’s a reason why a doctor asks for tests from a patient that appears well. Feeling well doesn’t mean there might not be a disease that shows no obvious symptoms at the moment. The economist who refuses to have a closer look and see why GDP grows is like a doctor who refuses to have a closer look at his patient. The Argentinian patient has caught the Bolivarian disease, but the most painful symptoms have yet to surface.

NOTE: This is a translated and expanded version of an original piece published in Economía Para Todos (Economics for Everyone).

Nicolás Cachanosky is Assistant Professor of Economics at Metropolitan State University of Denver. See Nicolás Cachanosky’s article archives.

You can subscribe to future articles by Nicolás Cachanosky via this RSS feed.

This article was published on Mises.org and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.

The FDA: A Pain From the Neck to the Big Toe – Article by Mark Thornton

The FDA: A Pain From the Neck to the Big Toe – Article by Mark Thornton

The New Renaissance Hat
Mark Thornton
October 25, 2013
******************************

I recently experienced severe pain in my feet, particularly in the big toes. In my imagination it felt like my feet had been run over by a truck and that several of my toes had been broken. But I knew that was not the case, and that the pain came on slowly at first, and then spread to other parts of my feet until I could barely walk.

My first approach was to take some ibuprofen to relieve the pain and swelling. When this did not resolve the matter, I thought perhaps a new pair of soft shoes might work. That idea also failed, and with a little internet research I realized I had a classic case of the gout. I was soon off to see my doctor to determine what the problem was and to get it solved with the powers of modern medicine.

The doctor confirmed that I had the gout. I was not pleased to find out, that in my case, the gout was probably brought on by another drug that I had been taking daily, against my better judgment. However, I was pleased to learn that I would no longer have to take it, that as part of my treatment I was being prescribed an ancient and natural drug, and that I would only have to take this drug “as needed.”

I was off to get my prescription filled at the pharmacy when a thought came to mind: if this drug was as natural and ancient as advised by my doctor, why did I need a prescription in the first place? Upon inspection the prescription was for Colcrys, the brand name of the drug colchicine. Furthermore, when I picked up my prescription the price was much higher than I anticipated given that it was a natural drug. When questioned, the pharmacy technician replied that the actual price was much higher and that my insurance paid for more than three-quarters of the bill. The cash price (without insurance) was $198.99 which is $6.63 per pill if taken daily, or nearly $20 per dose if used to treat flare-ups.

An extremely high price for an ancient natural drug? I knew I had a new case to solve and that the solution was probably the same old answer.

After conducting some research on Wikipedia, I learned the following: Colchicine can be used to treat gout, Behcet’s disease, pericarditis, and the Mediterranean fever. It has been in use as a medicine for over 3,000 years. After serving as ambassador to France, Benjamin Franklin brought colchicum plants back to America in order to treat his own gout. Modern science has further refined the drug for better medicinal use.

Colcrys has been used to treat gout for a very long time, although the Food and Drug Administration (FDA) had not approved Colcrys specifically for the treatment of gout prior to 2009. Alternative drugs, such as Allopurinal, are also used to treat gout and related ailments. Until recently, you could treat your own gout using one of these medicines for pennies a day.

In the summer of 2009, the Food and Drug Administration approved Colcrys as a treatment for gout flare-ups and the Mediterranean fever. The FDA gave pharmaceutical company URL Pharma an exclusive marketing agreement for selling Colcrys in exchange for completing studies on Colcrys and paying the FDA a $45 million application fee.

This deal effectively created a patented drug with no generic alternative. Therefore it gave the company a monopoly for the duration of the agreement. URL Pharma immediately raised the price from less than a dime to nearly $5 dollars per pill. Comprehensive medical insurance does substantially reduce the price to consumers, but it does not reduce the cost. Insurance only spreads the cost-burden across policy holders.

At the same time, doctors are encouraged by pharmaceutical companies to employ more expensive and profitable treatments. As a result the overall cost burden increases. Evidence suggests that doctors are prescribing Colcrys in large volumes to treat gout flare-ups and as a long-term preventative measure.

Once again the federal government has taken something that was both cheap and beneficial and turned it into a monopoly that hurts the general public and drives up the cost of medical care to the benefit of Big Pharma.

Note: Just because it is natural and produced in a pharmaceutical environment, does not mean that Colcrys is harmless. It can be considered toxic in large amounts, has a long list of possible side effects, and is not recommended for people with certain conditions.

Mark Thornton is a senior resident fellow at the Ludwig von Mises Institute in Auburn, Alabama, and is the book review editor for the Quarterly Journal of Austrian Economics. He is the author of The Economics of Prohibition, coauthor of Tariffs, Blockades, and Inflation: The Economics of the Civil War, and the editor of The Quotable Mises, The Bastiat Collection, and An Essay on Economic Theory. Send him mail. See Mark Thornton’s article archives.

You can subscribe to future articles by Mark Thornton via this RSS feed.

This article was published on Mises.org and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.

Free Your Talent and the Rest Will Follow – Article by Orly Lobel

Free Your Talent and the Rest Will Follow – Article by Orly Lobel

The New Renaissance Hat
Orly Lobel
October 17, 2013
******************************

Imagine two great cities. Both are blessed with world-class universities, high-tech companies, and a concentration of highly educated professionals. Which will grow faster? Which will become the envy and aspiration for industrial hubs all around the world?

Such was the reality for two emerging regions in the 1970s: California’s Silicon Valley and the high-tech hub of Massachusetts Route 128. Each region benefited from established cities (San Francisco and Boston), strong nearby universities (University of California-Berkeley/Stanford and Harvard/MIT), and large pools of talented people.

We’ve all heard about Silicon Valley, but not so much Route 128. Despite their similarities, and despite the Bostonian hub having three times more jobs than Silicon Valley in the 1970s, Silicon Valley eventually overtook Route 128 in number of start-ups, number of jobs, salaries per capita, and invention rates.

The distinguishing factor for Silicon Valley was an economic environment of openness and mobility. For more than a century, dating back to 1872, California has banned post-employment restrictions. The California Business and Professions Code voids every contract that restrains someone from engaging in a lawful profession, trade, or business. This means that unlike most other states, California’s policy favors open competition and the right to move from job to job without constraint. California courts have repeatedly explained that this ban is about freeing up talent, allowing skilled people to move among ventures for the overall gain of California’s economy.

The data confirm this intuition: Silicon Valley is legendary for the success of employees leaving stable jobs to work out of their garages, starting new ventures that make them millionaires overnight. Stories are abundant of entire teams leaving a large corporation to start a competitive firm. Despite these risks, California employers don’t run away. On the contrary, they seek out the Valley as a prime location to do business. Despite not having the ability to require non-compete clauses from their employees, California companies compete lucratively on a global scale. These businesses think of the talent wars as a repeat game and find other ways to retain the talent they need most.

In fact, the competitive talent policy is also supported by a market spirit of openness and collaboration. Even when restrictions are legally possible—for example, in trade secret disputes—Silicon Valley firms frequently choose to look the other way. Sociologist Annalee Saxenian, who studied the industrial cultures of both Silicon Valley and Route 128 in Massachusetts, found that while Boston’s Route 128 developed a culture of secrecy, hierarchy, and a conservative attitude that feared exchanges and viewed every new company as a threat, Silicon Valley developed an opposing ethos of fluidity and networked collaborations. These exchanges of the Valley gave it an edge over the autarkic environment that developed on the East Coast. In Massachusetts, firms are more likely to be vertically integrated—or to have internalized most production functions—and employee movement among firms occurs less frequently.

New research considering these different attitudes and policy approaches toward the talent wars supports California’s modus operandi.

A recent study by the Federal Reserve and the National Bureau of Economic Research examined job mobility in the nation’s top 20 metropolitan areas and found that high-tech communities throughout California—not only Silicon Valley—have greater job mobility than equivalent communities in other states. Network mapping of connections between inventors also reveals that Silicon Valley has rapidly developed denser inventor networks than other high-tech hubs have.

Researching over two million inventors and almost three million patents over three decades, a 2007 Harvard Business School study by Lee Fleming and Keon Frenken observes a dramatic aggregation of the Silicon Valley regional networks at the beginning of the 1990s. Comparing Boston to Northern California, the study finds that Silicon Valley mushroomed into a giant inventor network and a dense superstructure of connectivity, as small isolated networks came together. By the new century, almost half of all inventors in the area were part of the super-network. By contrast, the transition in Boston occurred much later and much less dramatically.

Michigan provides a natural experiment for understanding the consequences of constraining talent mobility. Until the mid-1980s, Michigan, like California, had banned non-competes. In 1985, as part of an overarching antitrust reform, Michigan began allowing non-competes, like most other states. Several new studies led by MIT Sloan professor Matt Marx look at the effects of this change on the Michigan talent pool. The studies find that not only did mobility drop, but that also once non-competes became prevalent, the region experienced a continuous brain drain: Its star inventors became more likely to move elsewhere, mainly to California. In other words, California gained twice: once from its intra-regional mobility supported by a strong policy that favors such flows, and once from its comparative advantage over regions that suppress mobility.

A virtuous cycle can be put into motion geographically where talent mobility supports professional networks, which in turn enhance regional innovation. Firms can learn to love these environments of high risk and even higher gain. Rather than thinking of every employee who leaves the company as a threat and an enemy, smart companies are beginning to think of their former employees as assets, just as universities wish for the success of their alumni. Companies like Microsoft and Capital One have established networks of alumni. They showcase their former employees’ achievements and practicing rehiring of their best talent, hoping that at least some of those who leave will soon realize that the grass is not always greener elsewhere.

Most importantly, motivation and performance are triggered by commitment and positive incentives to stay, rather than threats and legal restrictions against leaving. In behavioral research I’ve conducted with my co-author On Amir, we find that restrictions over mobility can suppress performance and cause people to feel less committed to the task. Cognitive controls over skill, knowledge, and ideas are worse than controls over other forms of intellectual property because they prevent people from using their creative capacities, they don’t just prevent firms from using inventions that are already out there. So instead of requiring non-competes or threatening litigation over intellectual property, California companies use rewards systems, creating the kind of corporate cultures where employees want to work and do well. Again, a double victory.

Unsurprisingly, when Forbes recently looked at the most inventive cities in the country for 2013 using OECD data, the two top cities were in California: bio-tech haven San Diego, and the legendary home of Silicon Valley, San Francisco. Boston, still vibrant and highly innovative despite its most restrictive attitudes, came in third. Competition is the lifeblood of any economy, and fierce competition over people is the essence of the knowledge economy.

Orly Lobel is the Don Weckstein Professor of Law at the University of San Diego and founding faculty member of the Center for Intellectual Property and Markets. Her latest book is Talent Wants to be Free: Why We Should Learn to Love Leaks, Raids, and Free-Riding (Yale University Press, September 2013).

This article was originally published by The Foundation for Economic Education.
New Fed Boss Same as the Old Boss – Article by Ron Paul

New Fed Boss Same as the Old Boss – Article by Ron Paul

The New Renaissance Hat
Ron Paul
October 13, 2013
******************************

The news that Janet Yellen was nominated to become the next Chairman of the Board of Governors of the Federal Reserve System was greeted with joy by financial markets and the financial press. Wall Street saw Yellen’s nomination as a harbinger of continued easy money. Contrast this with the hand-wringing that took place when Larry Summers’ name was still in the running. Pundits worried that Summers would be too cautious, too hawkish on inflation, or too close to big banks.

The reality is that there wouldn’t have been a dime’s worth of difference between Yellen’s and Summers’ monetary policy. No matter who is at the top, the conduct of monetary policy will be largely unchanged: large-scale money printing to bail out big banks. There may be some fiddling around the edges, but any monetary policy changes will be in style only, not in substance.

Yellen, like Bernanke, Summers, and everyone else within the Fed’s orbit, believes in Keynesian economics. To economists of Yellen’s persuasion, the solution to recession is to stimulate spending by creating more money. Wall Street need not worry about tapering of the Fed’s massive program of quantitative easing under Yellen’s reign. If anything, the Fed’s trillion dollars of yearly money creation may even increase.

What is obvious to most people not captured by the system is that the Fed’s loose monetary policy was the root cause of the current financial crisis. Just like the Great Depression, the stagflation of the 1970s, and every other recession of the past century, the current crisis resulted from the creation of money and credit by the Federal Reserve, which led to unsustainable economic booms.

Rather than allowing the malinvestments and bad debts caused by its money creation to liquidate, the Fed continually tries to prop them up. It pumps more and more money into the system, piling debt on top of debt on top of debt. Yellen will continue along those lines, and she might even end up being Ben Bernanke on steroids.

To Yellen, the booms and bust of the business cycle are random, unforeseen events that take place just because. The possibility that the Fed itself could be responsible for the booms and busts of the business cycle would never enter her head. Nor would such thoughts cross the minds of the hundreds of economists employed by the Fed. They will continue to think the same way they have for decades, interpreting economic data and market performance through the same distorted Keynesian lens, and advocating for the same flawed policies over and over.

As a result, the American people will continue to suffer decreases in the purchasing power of the dollar and a diminished standard of living. The phony recovery we find ourselves in is only due to the Fed’s easy money policies. But the Fed cannot continue to purchase trillions of dollars of assets forever. Quantitative easing must end sometime, and at that point the economy will face the prospect of rising interest rates, mountains of bad debt and malinvested resources, and a Federal Reserve which holds several trillion dollars of worthless bonds.

The future of the US economy with Chairman Yellen at the helm is grim indeed, which provides all the more reason to end our system of central economic planning by getting rid of the Federal Reserve entirely. Ripping off the bandage may hurt some in the short run, but in the long term everyone will be better off. Anyway, most of this pain will be borne by the politicians, big banks, and other special interests who profit from the current system. Ending this current system of crony capitalism and moving to sound money and free markets is the only way to return to economic prosperity and a vibrant middle class.

Ron Paul, MD, is a former three-time Republican candidate for U. S. President and Congressman from Texas.

This article is reprinted with permission from the Ron Paul Institute for Peace and Prosperity.

Review of Edward W. Younkins’s “Exploring Capitalist Fiction” – Article by G. Stolyarov II

Review of Edward W. Younkins’s “Exploring Capitalist Fiction” – Article by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
October 12, 2013
******************************

Exploring Capitalist Fiction, a new volume of literary analysis by Dr. Edward W. Younkins, offers perceptive, relevant, and engaging commentaries on 25 works of fiction which portray the business world and its relationship to all areas of human life. The novels, plays, and films featured in the book span 125 years of literary culture – from The Rise of Silas Lapham (1885) by William Dean Howells to the 2010 Oliver Stone film Wall Street: Money Never Sleeps. This volume offers thorough coverage of both works that portray heroic entrepreneurs and economic liberty in a positive light – such as Ayn Rand’s Atlas Shrugged, Garet Garrett’s The Driver, and Henry Hazlitt’s Time Will Run Back – as well as works that are more critical of the business world – including Edward Bellamy’s Looking Backward, Sinclair Lewis’s Babbitt, Frank Norris’s The Octopus, and the Wall Street films. In each of his essays, Younkins provides a sequential summary of the fictional work, interspersed with commentary that highlights the philosophical and economic implications of major elements and integrates them with the historical context of the time period in which the work takes place.

Younkins is to be commended for emphasizing the value of fiction as a teaching tool for both students of business and individuals immersed in the business world. A thorough reading of the book’s Conclusion is highly recommended for attaining an understanding of the unique ability of fiction to communicate memorable lessons rooted in specific, richly detailed situations which render the conflicts, dilemmas, and options faced by individuals in the business world more palpable and engaging than would a sole reliance on lectures, case studies, and outlines of business and economic concepts. In addition, the Conclusion offers a fast-paced chronological overview of many more fictional works which address business themes and which have made their mark on the world of artistic culture.

As with his previous volumes, where Dr. Younkins provided integrated presentations of the thoughts of great philosophers and economists throughout the centuries, this book provides a refreshing focus on human flourishing and the application of the lessons of particular novels, plays, and films toward the improvement of both one’s own condition and the degree of prosperity found in the broader economy. This is not literary analysis for its own sake, but rather a book that highlights the lessons an individual can take from each great work and apply to his or her own life.

Younkins combines his support for free markets, entrepreneurial innovation, individualism, reason, and moral responsibility with an ability to point out the many valuable insights in those works which criticize capitalism as conventionally understood. He utilizes the insights of Austrian economics and his extensive knowledge of economic history to show how the bleak portrayals of businessmen and the business world in these books stem from the consequences of situations where the principles of honest free commerce and individual rights were violated. When critics of capitalism express their objections through fiction, they inevitably portray situations where fraud, corruption, morally questionable manipulation, corporatist special privileges, thoughtless conformity, and zero-sum thinking are involved. All of these are indeed negative attributes from the standpoints of free markets and rational philosophy as well, and Younkins’s analysis shows that the works of the critics do make valid points – provided that one understands that the system they are criticizing is the one that has actually prevailed in the Western world over the past century. This is the system which mixes aspects of capitalist free enterprise with significant aspects of corporatist cronyism as well as central planning. It is a system quite different from the free-market capitalism advocated by Henry Hazlitt, Garet Garrett, and Ayn Rand. Indeed, in Atlas Shrugged, the protagonists go on strike precisely against this sort of cronyist system, though one that is farther-gone than our own. In Tucker: The Man and His Dream, an excellent movie to which Younkins devotes  a chapter, this is also the system which attempts to suppress a genuine forward-thinking capitalist innovator, Preston Tucker, through the use of political force, motivated by the lobbying of the staid Big Three automobile companies.

For readers of all persuasions, Exploring Capitalist Fiction is an excellent means to appreciate the richness and variety of fictional portrayals of business, especially since the Second Industrial Revolution of the late 19th century. The book offers a concise introduction to many works and endeavors to motivate readers to seek out and experience the original novels, plays, and films. Hopefully, it will inspire many people to explore these great works of fiction, as it has already inspired me on multiple occasions.

Disclosure: The author received a free copy of the book in advance of publication.