Browsed by
Tag: central banking

Inflation Has Not Cured Iceland’s Economic Woes – Article by David Howden

Inflation Has Not Cured Iceland’s Economic Woes – Article by David Howden

The New Renaissance Hat
David Howden
November 6, 2013
******************************

No two countries’ responses have polarized commentators over the past five years more than the contrasting post-crisis policies in Iceland and Ireland.

In a paper published in Economic Affairs (available here as a PDF) I contrast the policies enacted by Iceland and Ireland, perhaps the two countries most affected by the liquidity freeze of 2008. A common conclusion has been that one country did everything right and the other did everything wrong, however, I take a more pragmatic approach. There are some positive aspects in each case, and other aspects we can do without.

At the risk of over-simplifying their situations, the key policy differences are:

  1. Iceland allowed substantial swaths of its financial sector to collapse (mostly foreign-domiciled subsidiaries) while Ireland enacted blanket guarantees to keep its financial sector afloat.
  2. Iceland quickly inflated its krona in a bid to regain international competitiveness through depreciation. By being locked in the euro, Ireland was unable to pursue a similar path and instead had to become more attractive to foreigners by lowering its domestic prices (i.e., disinflation or outright deflation).
  3. Iceland stymied a capital flight by enacting monetary controls aimed at keeping investment within the country. By being part of the European Union, Ireland maintained its commitment to free capital markets, and investors were able to enter or exit as they pleased.

The evidence is mixed as to which solution was more effective. Iceland seems to have softened the immediate blow of its recession, but present growth in Ireland is stronger. In a similar way, unemployment in Iceland was less and still remains lower today.

For our purposes here, I want to focus just on the effects of their respective monetary policies, and how the short-term gains from Iceland’s inflationary response now pale in comparison to Ireland’s more subdued response.

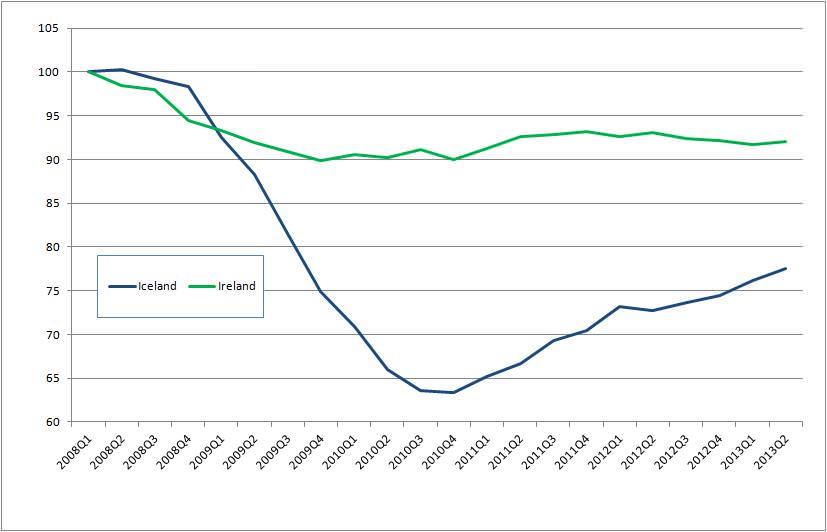
Figure 1: Nominal GDP (2008 = 100) Source: Federal Reserve Bank of St. Louis

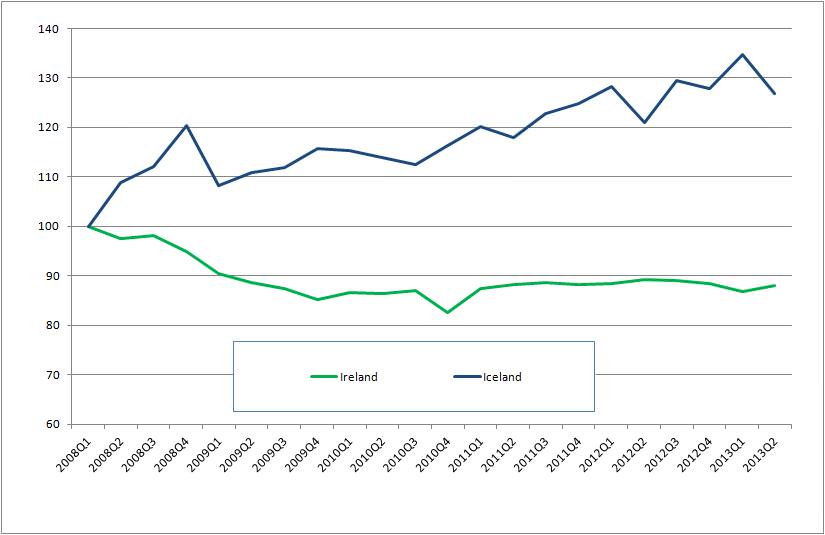
Figure 1 shows the common story. Iceland’s inflationary policy stimulated exports, papered over some bad debts, and in general allowed it to exit the storm relatively unscathed. In contrast, Ireland is languishing in slow growth and five years later the country’s income is still 10 percent below its pre-bust peak.

Such an analysis neglects the pernicious effects of inflation on the Icelandic economy. This policy increased the money supply by almost 20 percent in 2008 alone, and lead to an immediate increase in prices.

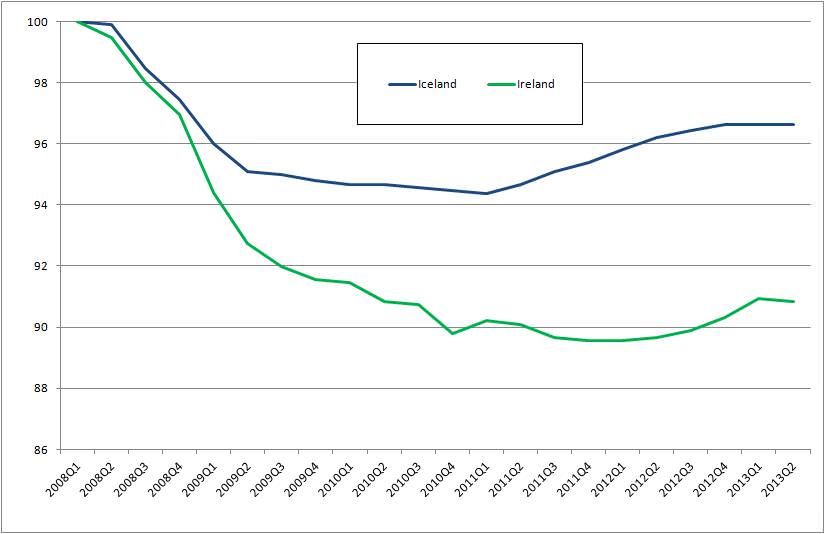
Figure 2: Real GDP (2008 = 100) Source: Federal Reserve Bank of St. Louis

In figure 2 we get a better feel for how the situation felt to the average Icelander or Irishman. As the Central Bank of Iceland inflated the money supply, price inflation raged. Icelanders continually felt their financial security worsen as their purchasing power collapsed. This was not apparent to the rest of the world, fixated as it was on the nominal prices the Icelandic economy posted. By its nadir in late 2010, inflation-adjusted income in Iceland was down over 35 percent.

In Ireland this decline was muted because of price deflation. As domestic prices fell it became easier for Irish citizens to make their declining nominal incomes go further. At its worst, the Irish economy collapsed less than 10 percent in real terms.

This seems to suggest that Ireland had the better solution by not pursuing an inflationary monetary policy. Some will note, however, that Iceland’s recovery since 2010 has been quite strong.

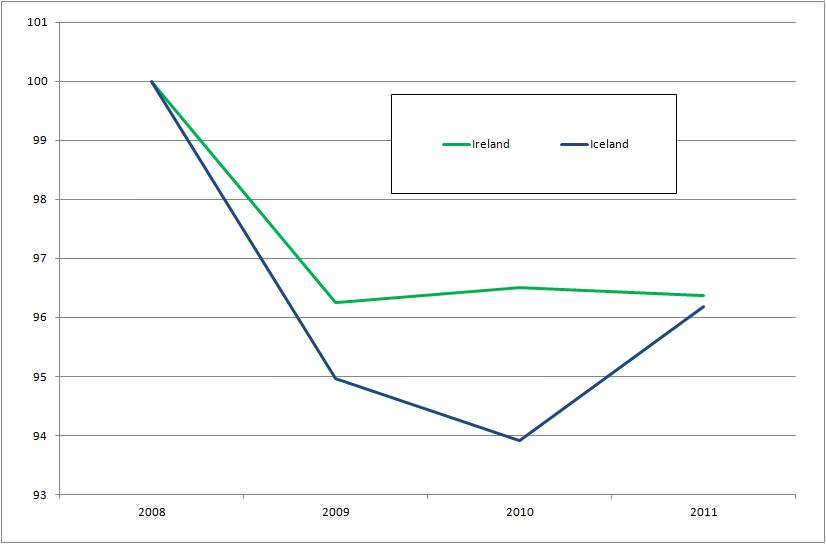
Indeed, if we look at the drop in the employment rate for both countries most probably feel more sympathy for the masses of unemployed Irishmen.

Figure 3: Employment rate (2008 = 1) Source: Federal Reserve Bank of St. Louis

Digging deeper, however, we find that not all is as it seems. Many Icelanders work two jobs to make ends meet. This effect was increasingly pronounced through the recession as inflation made it more difficult to get by with one salary. As a consequence, many Icelanders lost one job during the recession but the unemployment statistics did not reflect this as they were still employed elsewhere. This is notably not the case in Ireland, where not only is one job per worker the norm, but falling prices made it easier for an employed person to make ends meet as the recession continued.

A better way to gauge the employment situation is to look at changes in the hours worked.

Figure 4: Annual hours worked (2008 = 100) Source: Federal Reserve Bank of St. Louis

Here we can see the situation is reversed. By the recession’s trough in 2010 the number of hours worked by the average Icelander had fallen 6 percent while in Ireland the corresponding drop was only 3.5 percent — almost half as much.

Both countries still have problems. Iceland’s monetary controls are notably stifling needed investment, while Ireland is left with a large debt from bailing out its banks, and this is stalling growth. One thing is clear though — the effects of monetary policy are stark and the proclaimed benefits of Iceland’s inflationary policy were counteracted by the price inflation that ensued.

Don’t let a good crisis go to waste; learn something from it. As the tale of these two countries demonstrates, inflating one’s currency may give the appearance of recovery, but the truth is somewhat less rosy.

David Howden is Chair of the Department of Business and Economics and professor of economics at St. Louis University’s Madrid Campus, Academic Vice President of the Ludwig von Mises Institute of Canada, and winner of the Mises Institute’s Douglas E. French Prize. Send him mail. See David Howden’s article archives.

This article was published on Mises.org and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.

Why Do Banks Keep Going Bankrupt? – Article by Kirby R. Cundiff

Why Do Banks Keep Going Bankrupt? – Article by Kirby R. Cundiff

The New Renaissance Hat
Kirby R. Cundiff
November 4, 2013
******************************

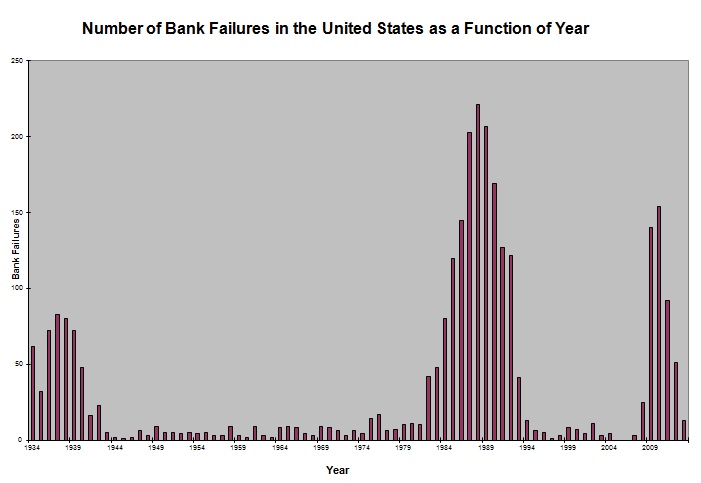
The banking industry is unstable. Banks are regularly going bankrupt. Crises in the banking industry have occurred in three distinct time periods during the twentieth century—during the Great Depression of the 1930s, during the Savings and Loan crisis of the 1980s and 1990s, and during the Great Recession from 2007 to present.

Why the banking industry is so vulnerable to bankruptcies and what can be done to correct this problem?

Debt to assets, or leverage, ratios vary significantly from industry to industry. They are typically under ten percent in most high tech industries and go up to forty percent for public utilities. Average debt ratios in the banking and financial services industry are in the fifty to seventy percent range, however, and many banks have much higher leverage ratios.

Firms attempt to minimize their total financing costs or Working Average Cost of Capital (WACC). The component costs of capital (cost of debt and cost of equity) are determined by investors’ perceptions of the risk and return possibilities associated with buying debt or equity in a given company or individual.

A credit card loan has a higher interest rate than a home loan because the credit card loan is riskier—i.e. there are no assets to seize if the money is not paid back. Similarly, a high-risk company normally pays a higher interest rate on its debt than a lower-risk company and increasing leverage is normally associated with increasing risk. Due to deposit insurance, however, this isn’t the case with banks.

Moral Hazard

The Federal Deposit Insurance Corporation (FDIC) insures deposits up to $250,000 in the United States. Most of the European countries (including Cyprus) have similar organizations that insure deposits up to 100,000 EUR. (See Deposit Insurance.)

Since depositors believe that their bank accounts are insured by governments, they do not generally know or care how much risk banks incur when they invest their depositors’ money. This creates a moral hazard problem with very little oversight by depositors of a bank’s management of their assets. Bank managers can take a lot of risk and, if they make profits, they keep the money. If they lose money, the taxpayers pay for the losses. In theory, this moral hazard problem is mitigated by subordinated debt, investors with deposits over the deposit insurance limit, and banking regulations. But these approaches are clearly not working.

In a series of agreements called the Basel Accords, the Basel Committee on Bank Supervision (BCBS) provides certain recommendations on banking regulations in regards to capital risk, market risk and operational risk. The purpose of these accords is to ensure financial institutions have enough capital to meet their obligations. The Tier I and Tier II capital controls of the Basel Agreements are supposed to prevent banks from taking too much risk with depositors’ assets. Tier 1 capital consists largely of shareholders’ equity. Tier 2 capital comprises undisclosed reserves, revaluation reserves, general provisions, hybrid instruments and subordinated debt.

The capital ratios are:

  •   Tier 1 capital ratio = Tier 1 capital / Risk-adjusted assets
  •   Total capital (Tier 1 and Tier 2) ratio = Total capital (Tier 1 + Tier 2) / Risk-adjusted assets
  •   Leverage ratio = Tier 1 capital / Average total consolidated assets

To be well-capitalized under federal bank regulatory definitions, a bank holding company must have a Tier 1 capital ratio of at least six percent, a total capital ratio of at least ten percent, and a leverage ratio of at least five percent (Capital).

The leverage ratios allowed under the Basel agreements are far higher than the typical leverag ratios in most industries and are far higher than would exist in a free-market financial system. Under a free-market system, depositors would not put their money in overly-leveraged banks and banks would be forced to decrease their leverage ratios and behave more like mutual or money market funds. Banks would be less likely to use short-term liabilities (deposits) to fund long-term assets (loans).

The S&L Crisis

Massive bank leverage would not create as much instability if the money supply was stable as in the 1800s under the gold standard. Under the current debt-is-money system, inflation and interest rates can vary wildly from year to year. The Savings and Loan Associations (S&Ls) made many low interest 30-year fixed rate home loans when inflation was low in the 1960s—five percent interest rate loans were typical. As inflation increased, the S&Ls still had these long-term home loans on their books, but the market now demanded higher interest rates on deposits (eighteen percent at times). The interest rates that many savings and loans were receiving on their assets (30-year fixed rate loans) were much lower than the interest rates the same S&Ls were paying on their liabilities (deposits). This duration mismatch resulted in the mass insolvency of the Savings and Loan Industry and a bailout of the S&Ls by the American tax payers exceeding $100 billion.

The Great Recession

The banking defaults of the Great Recession (2007 to present) were also caused by unstable interest rates combined with high leverage. The Federal Reserve lowered rates in the early 2000s to stimulate the economy after the bursting of the dot.com bubble. This resulted in many people borrowing money at very low interest rates to buy homes. Then the Federal Reserve raised interest rates and many people were no longer able to make their home payments. Again the result was massive bank insolvency and a substantial decrease in home values. Another huge taxpayer -funded bailout of the banking system followed, and the Federal Reserve has been printing money ever since, trying to stimulate the economy in the wake of yet another bubble it created.  The disbursements associated with placing into conservatorship government-sponsored enterprises Fannie Mae and Freddie Mac by the U.S. Treasury, the Troubled Asset Relief Program (TARP), and the Federal Reserve’s Maiden Lane Transactions are probably around $400 billion. How much of these disbursements will be paid back is currently unclear.

During the recent crises in Cyprus, proposals were seriously considered to ignore the 100,000 EUR deposit insurance and seize a fraction of even small depositors’ money. Most depositors lost access to their accounts for over a week and large depositors are still likely to lose a large fraction of their assets. This crisis has made some depositors more likely to pay attention to the solvency of their banks, but most depositors still believe that deposit insurance will cover any possible losses. If banks are to become more stable, the amount of equity relative to debt in the banking system must be drastically increased to something resembling what it would be without government deposit insurance, central bank subsidies, and treasury bailouts. Given the lobbying power of bankers in Washington, DC and around the word, such is unlikely to occur. The boom-bust cycle of banking bubbles followed by banking crises will most surely continue.

For further reading on this topic see this from The Freeman.

Kirby R. Cundiff, Ph.D. is an Associate Professor of Finance at the Rochester Institute of Technology. He is a Chartered Financial Analyst and a CERTIFIED FINANCIAL PLANNERTM Professional. 

This article was originally published by The Foundation for Economic Education.


Federal Reserve Blows More Bubbles – Article by Ron Paul

Federal Reserve Blows More Bubbles – Article by Ron Paul

The New Renaissance Hat
Ron Paul
May 5, 2013
******************************

Last week at its regular policy-setting meeting, the Federal Reserve announced it would double down on the policies that have failed to produce anything but a stagnant economy. It was a disappointing, but not surprising, move.

The Fed affirmed that it is prepared to increase its monthly purchases of Treasuries and mortgage-backed securities if things don’t start looking up. But actually the Fed has already been buying more than the announced $85 billion per month. Between February and March, the Fed’s securities holdings increased $95 billion. From March to April, they increased $100 billion. In all, the Fed has pumped more than a half trillion dollars into the economy since announcing its latest round of “quantitative easing” (QE3) in September 2012.

Although many were up in arms when the Fed said it would buy $600 billion in government debt outright for the previous round, QE2, all seems quiet about the magnitude of QE3 because it doesn’t come with huge up-front total price tag. But by year’s end the Fed’s balance sheet could hit $4 trillion.

With no recovery in sight, where’s all this money going? It is creating bubbles. Bubbles in the housing sector, the stock market, and government debt. The national debt is fast approaching $17 trillion, with the Fed monetizing most of the newly issued debt. The stock market has been hitting record highs for the past two months as investors seek to capitalize on the Fed’s easy money. After all, as long as the Fed keeps the spigot open, nominal profits are there for the taking. But this is a house of cards. Eventually, just like in 2008-2009, the market will discipline the bad actions of the Fed and seek to find the real normal.

In the meantime, real families are suffering. While Wall Street and the federal government take advantage of access to the Fed’s new “free” money, the Fed claims there is no inflation. But who hasn’t paid higher prices at the grocery store, the gas pump, for tuition, for insurance? It’s bad enough that household incomes have stagnated, but real purchasing power has declined so much that one in seven Americans, 47.3 million people, are on food stamps. Five million are collecting unemployment insurance with 21.5 million afflicted by unemployment according to the federal government’s own figures. That’s 13.9 percent — close to double the 7.5 percent unemployment number reported last week.

We are certainly not in a recovery. We don’t see the long unemployment and soup-kitchen lines like in the Great Depression, but that’s just because the lines are electronic now.

It is not surprising the Fed has decided to hand the American people more of the same failed policies. But it is disappointing. We know what the real solution is: allow the marketplace to work. Allow entrepreneurs the chance to create instead of stifling innovation with arbitrary regulations. Allow interest rates to rise to equal the risks in the economy. Allow bad debts to be liquidated so we can build on a firm foundation. Stop printing money to benefit the government and big banks. Restore sound money to the economy and the American people. Sound money is the bedrock for prosperity and the best check on big government and crony capitalism.

Ron Paul, MD, is a former three-time Republican candidate for U. S. President and Congressman from Texas.

This article is reprinted with permission.

The Golden Age of Freedom Is Still Ahead – Article by Anthony Gregory

The Golden Age of Freedom Is Still Ahead – Article by Anthony Gregory

The New Renaissance Hat
Anthony Gregory
October 6, 2012
******************************

Free enterprise is often associated with the past. This perception puts the market’s champions, seen as hopeless reactionaries, on the defensive.

A typical narrative follows: America had an insufficiently active government under the Articles of Confederation. The Constitution expanded the central government to meet society’s needs. In this climate, where property rights continued to trump the common good, the central government could not maintain national cohesion and ensure racial equality. During the Civil War, the federal government grew to preserve the Union, enable commerce through expansion of infrastructure, and abolish the ancient evil of slavery. During the late nineteenth century, laissez faire reigned supreme. Unchecked, robber barons exploited their customers and workers.

American society, so continues the narrative, overcame its laissez-faire history and embraced active government in the Progressive Era. Commerce, banking, monopolies, food and drugs, and labor conditions finally became regulated. The market was still too free, however, causing the stock market crash and the Great Depression, which the New Deal’s reforms finally addressed. Anachronistic free marketers resisted this progress.

A generation later the free market proved inadequate on race relations, education, poverty, social insurance, workers’ conditions, and the environment. New regulations, taxes, and programs arose in the 1960s and 1970s to address these deficiencies. Ronald Reagan’s election marked a conservative counterrevolution toward the free market, causing the savings-and-loan crisis, rising income disparities, and, ultimately, the 2008 financial collapse. After four consecutive reactionary presidents—Bill Clinton being a practitioner of neoliberal austerity—deregulation and market fundamentalism have again revealed themselves as outdated approaches to America’s modern problems.

This repeated recognition that the free market no longer suits society’s needs is a common theme of modern liberalism. Through experience the inadequacy of the unhampered market has forced enlightened observers to accept the need for more government.

One obvious problem with this narrative is the steadily changing definition of “free market.” The free market is said to have caused problems addressed in the Progressive Era, yet once again the market economy was blamed for the Depression.The New Deal is said finally to have abolished laissez faire, yet laissez faire has been the culprit in every crisis since. Thoughtful proponents of this narrative explain that the 1980s, for example, were somehow substantially more laissez-faire than the 1970s, yet they rarely present more than a handful of superficial examples of deregulation amid an overall trend of regulatory expansion.

A major problem market proponents have in confronting this narrative, whatever its shortcomings, arises because they themselves sometimes accept it implicitly, often complaining about the liberties lost over the years. The significant kernel of truth is that the national government has unmistakably grown well beyond anything imagined in 1789 or even the nineteenth century. And surely, for every argument statists have defending this growth, compelling historical and economic counterarguments are available.

Yet we must be careful before conceding this premise that the past was laissez-faire. By celebrating the political economy of yesteryear, we risk associating our ideals with the past’s many injustices. We can and should avoid this baggage entirely.

Slavery: The Opposite of Free Enterprise

No libertarian defends the horrid institution of slavery. The problem comes in how free marketers sometimes describe slavery as a mere exception to the rule of early American freedom. In fact this exception virtually swallowed the principle whole.

Progressives love contrasting the pro-liberty, anti-tax rhetoric of the founding generation with the slavery that they tolerated or championed. Robin Einhorn’s American Taxation, American Slavery is a sophisticated contribution to the argument that those loudly protesting taxes were often the very people who clung to human bondage. This argument indicts the rhetoric of property rights, which is foundational to free enterprise and, in a warped form, the “right” of one person to own another. Infamously, the Supreme Court found in Dred Scott v. Sanford (1857) that the Fifth Amendment protected a white man’s right not to be deprived of his slave without due process. Given this association between America’s slave-owning generations and the rhetoric of liberty, it is crucial that free marketers explain, emphatically and intelligently, how slavery was the very negation of the free-market system.

The subjugation of slaves would undermine early America’s status as a free country even if slaves were a tiny minority. They were not. Slaves amounted to 18 percent of the population at the time of the Constitution’s ratification and 12.6 percent on the eve of the Civil War, at which point there were nearly four million.

Libertarians should study the brutality of this system. Historians estimate that hundreds of thousands of slaves were forced to migrate in antebellum America’s internal slave trade. Children were frequently ripped from their families. Beatings and rape were ubiquitous, and torture as punishment was hardly unusual.

Even slaves with relatively humane masters lacked the freedoms that most of today’s Americans, living under the modern leviathan, take for granted.

Peter Kolchin, in his seminal American Slavery: 1619–1877, sums up the reality:

Slaves could hardly turn around without being told what to do.They lived by rules, sometimes carefully constructed and formally spelled out and sometimes haphazardly conceived and erratically imposed. Rules told them when to rise in the morning, when to go to the fields, when to break for meals, how long and how much to work, and when to go to bed; rules also dictated a broad range of activities that were forbidden without special permission, from leaving home to getting married; and rules allowed or did not allow a host of privileges, including the right to raise vegetables on garden plots, trade for small luxuries, hunt, and visit neighbors. Of course, all societies impose rules on their inhabitants in the form of laws, but the rules that bound slaves were unusually detailed, covered matters normally untouched by law, and were arbitrarily imposed and enforced, not by an abstract entity that (at least in theory) represented their interests, but by their owners. Slaves lived with their government.

I thank God I don’t live with my government! For many years the pro-market tradition saw slavery as a grave violation of its principles. Kolchin writes:

Early political economists—including Adam Smith, whose book The Wealth of Nations (1776) remained for decades the most influential justification for the principles underlying capitalism—believed that slavery, by preventing the free buying and selling of labor power and by eliminating the possibility of self-improvement that was the main incentive to productive labor, violated central economic laws.

Although critics blame market exchange for the rise of slavery, this criticism is grossly unfair. The slave trade was indeed a market of sorts—unfree, unjust, and regulated—but the most fundamental relationship in slavery was not a market at all. Kolchin explains:

Slave owners engaged in extensive commercial relations, selling cotton (and other agricultural products), buying items both for personal consumption and for use in their farming operations, borrowing money, and speculating in land and slaves, but the market was conspicuously absent in regulating relations between the masters and their slaves. In other words, relations of exchange were market-dominated, but relations of production were not.

The slave power dominated political life in the South and enjoyed federal support through the Fugitive Slave Clause. Slavery was a major government program, its enforcement costs socialized through law. “The chief way that the South’s slaveholding elite externalized the costs of the peculiar institution was slave patrols,” writes Jeffrey Rogers Hummel in Emancipating Slaves, Enslaving Free Men. These slave patrols were “established in every slave state” to enforce black codes, inflict punishment, and suppress insurrections and were “compulsory for most able bodied white males.” Slave patrols, necessary to slavery’s maintenance, were a flagrant violation of the free economy.

The destruction of the Indians, the restrictions on women owning property, and many other antebellum policies also illustrate that the United States hardly had a free market before the Civil War. Slavery best makes the point. The conflation of a slave society with free enterprise is an obscenity.

Protectionism, Nationalism, and Corporatism

Outside of slavery nineteenth-century America often fell far short of the free-market ideal. Protectionism was a perennial problem, from the nationalist Tariff of 1816 to the sectionally biased Tariff of 1824 and the infamous Tariff of Abominations in 1828, from President Andrew Jackson’s threat to invade South Carolina to enforce the Tariff of 1832 to the Morrill Tariff of 1861. In 1870 the average tariff rate hit 44.6 percent. High tariffs financed the corporatist arrangement of federal subsidies for waterways, canals, and railroads during the Civil War, a war that defied market principles dramatically through its taxation, conscription, militarization of society, massive inflation, and inauguration of new government bureaus.

After slavery’s abolition and before the twentieth century, American economic liberty in some senses achieved a peak, but not without many qualifications. Immediately after the Civil War, state-level black codes kept nominally free blacks in a form of extended slavery, indenturing them to employers and criminalizing “vagrancy.” The U.S.  government began enforcing Reconstruction in the conquered South through military rule. Reconstruction counteracted State-imposed rights violations but also fostered a rise in government education and infrastructure projects financed through federal subsidies and considerable hikes on state-level property taxes. Government schooling became much more prevalent in the South, and by the end of the century 75 percent of the states had compulsory attendance laws.

The banking system—fundamental to any modern economy—was regulated by the federal government for most of the nineteenth century. There was a National Bank from 1791 to 1811 and again from 1816 to 1832.The Civil War birthed a new federal banking system that quickly grew, eventually culminating in the creation of the Federal Reserve in 1913.

In the late nineteenth century Benjamin Tucker identified four federally created monopoly powers that robbed Americans of their liberty—the land monopoly, money monopoly, patent monopoly, and tariff monopoly. These mostly involved federal privileges, but the heavy hand of government was also felt locally. Nineteenth-century state governments, at times working with federal authorities, displaced and killed American Indians; regulated various professions, labor relations, consumption goods, and businesses; and implemented social programs.

All in all, the U.S. regulatory state, explains Roderick Long, was not a twentieth-century innovation, but rather was “deeply involved from the start, particularly in the banking and currency industries and in the assignment of property titles to land. (Even such land as was not stolen from the natives was seldom appropriated in accordance with any sort of Lockean homesteading principle; instead, vast tracts of unimproved land were simply declared property by barbed wire or legislative fiat.)”

In substantial ways the economy of the late nineteenth century was freer than today, although some groups were heavily controlled, not least of all the southern blacks persecuted by Jim Crow laws, to say nothing of whites restricted by segregation from freely associating with these blacks.

Even nationally the twilight of the nineteenth century was a mixed bag. Veto-happy Grover Cleveland was probably the most laissez-faire president in half a century and ever since. Yet Cleveland’s terms had nontrivial blemishes: He used U.S. Marshals to quell the Pullman strike and enforce the Sherman Antitrust Act, supported the Dawes Act’s aggrandizement of presidential authority over Indian affairs, strengthened the Chinese Exclusion Act, begrudgingly acquiesced to an income tax to offset reduced tariff revenue, created the Interstate Commerce Commission, and despite a largely anti-imperialist record, threatened and used military force to assert dominance in Latin America against European influence and in favor of U.S. banking interests.

Shifting Definition

The market’s defenders often mimic its opponents in moving the benchmarks to describe historical periods as “laissez-faire.” This dangerous game does not stop with the nineteenth century.

American life before the New Deal was certainly freer in important respects, but we must be cautious in defending the 1920s. Putting aside the bloated bureaucracies lingering from World War I, the Fordney McCumber Tariff of 1922, the Immigration Control Act of 1924, and the calamity of alcohol prohibition, it was 1920s credit expansion that Austrian economists credibly blame for the boom and 1929 crash. We lose credibility in carelessly praising the pre–New Deal Era while blaming the Depression on policies enacted in that time.

Less ambitious free marketers idealize the 1950s—the decade of top marginal tax rates exceeding 90 percent (and, for the poorest Americans, 20 percent); the FCC’s puritanical regulation of the airwaves and maintenance of the telephone monopoly; the booming military-industrial complex; and the growing regimentation of industry, farming, and higher education. The transformative Great Society was in many ways an expansion on Eisenhower-era precedents more than a qualitative break from the past.

Even more desperate acts of nostalgia glorify the Reagan years. Although some government impositions were curtailed on the margins, Ronald Reagan oversaw growth of the New Deal–Great Society regime, as deficit spending exploded, Social Security and protectionism expanded, and foreign aid and bureaucracies ballooned.

None of this sober reflection backward should prompt us to see our history as an inexorable march toward liberty. There have been major advances in modern times—abolition of the draft, strengthened free-speech rights, and greater legal tolerance for minorities—but even in areas like racial oppression and personal freedom, many matters have worsened. Over two million Americans are behind bars. The drug war has devastated African-American communities. Last year the national government deported more immigrants than ever before. The war on terror has shredded basic rights. Washington’s run-of-the-mill economic interventions—in the name of health, equality, environmentalism, and fighting poverty—have escalated.The national debt and entitlement state have seen an unprecedented boom.

Neither today’s dismal state of affairs nor past oppression should make us nihilistic. History can teach us a lot about liberty. Certain areas of American life were freer in the nineteenth century than today and others were not, and the social blessings arising from relative conditions of liberty are worth identifying and understanding. Economics shows that free markets serve the masses by elevating workers’ productivity and smashing the old order of privilege and oppression. Both experience and economic science demonstrate the superiority of liberty to statism.

The golden era of freedom and free markets is not now and it’s not behind us. It is still ahead of us. This is reason to rejoice. We can happily envision a much better future.

Anthony Gregory is a Research Fellow at the Independent Institute.

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.

Legalize Competing Currencies – Article by Ron Paul

Legalize Competing Currencies – Article by Ron Paul

The New Renaissance Hat
Ron Paul
August 16, 2012
******************************

I recently held a hearing in my congressional subcommittee on the subject of competing currencies.  This is an issue of enormous importance, but unfortunately few Americans understand how the Federal Reserve and Treasury Department impose a strict monopoly on money in America.

This monopoly is maintained using federal counterfeiting laws, which is a bit rich.  If any organization is guilty of counterfeiting dollars, it is our own Treasury.  But those who dare to challenge federal legal tender laws by circulating competing currencies – at least physical currencies – risk going to prison.

Like all federally created monopolies, the federal monopoly on money results in substandard product in the form of our ever-depreciating dollars.

Yet governments have always sought to monopolize the issuance of money, either directly or through the creation of central banks. The expanding role of the Federal Reserve in the 20th century enabled our federal government to grow wildly larger than would have been possible otherwise.  Our Fed, like all central banks, encourages deficits by effectively monetizing Treasury debt.  But the price we pay is the terrible and ongoing debasement of our money.

Allowing individuals and business to use alternate currencies, especially currencies backed by gold and silver, would expose the whole rotten system because the marketplace would prefer such alternate currencies unless and until the Fed suddenly imposed radical discipline on its dollar inflation.

Sadly, Americans are far less free than many others around the world when it comes to protecting themselves against the rapidly depreciating US dollar.  Mexican workers can set up accounts denominated in ounces of silver and take tax-free delivery of that silver whenever they want.  In Singapore and other Asian countries, individuals can set up bank accounts denominated in gold and silver.  Debit cards can be linked to gold and silver accounts so that customers can use gold and silver to make point of sale transactions, a service which is only available to non-Americans.

The obvious solution is to legalize monetary freedom and allow the circulation of parallel and competing currencies.  There is no reason why Americans should not be able to transact, save, and invest using the currency of their choosing.  They should be free to use gold, silver, or other currencies with no legal restrictions or punitive taxation standing in the way.  Restoring the monetary system envisioned by the Constitution is the only way to ensure the economic security of the American people.

After all, if our monetary system is fundamentally sound– and the Federal Reserve indeed stabilizes the dollar as its apologists claim–then why fear competition?  Why do we accept that centralized, monopoly control over our money is compatible with a supposedly free-market economy?  In a free market, the government’s fiat dollar should compete with alternate currencies for the benefit of American consumers, savers, and investors.

As Austrian economist Ludwig von Mises explained, sound money is an instrument that protects our civil liberties against despotic government. Our current monetary system is indeed despotic, and the surest way to correct things simply is to legalize competing currencies.

Representative Ron Paul (R – TX), MD, is a Republican candidate for U. S. President. See his Congressional webpage and his official campaign website. 

This article has been released by Dr. Paul into the public domain and may be republished by anyone in any manner.

Let Unsound Money Wither Away – Article by Joseph T. Salerno

Let Unsound Money Wither Away – Article by Joseph T. Salerno

The New Renaissance Hat
Joseph T. Salerno
July 29, 2012
******************************
[This is a revised version of written testimony submitted to the the Subcommittee on Domestic Monetary Policy and Technology of the Committee on Financial Services, US House of Representatives “Fractional Reserve Banking and Central Banking as Sources of Economic Instability: The Sound Money Alternative,” June 28, 2012.]
***

Chairman Paul and members of the subcommittee, I am deeply honored to appear before you to testify on the topic of fractional-reserve banking. Thank you for your invitation and attention.

In the short time I have, I will give a brief description of fractional reserve-banking, identify the problems it presents in the current institutional setting, and suggest a potential solution.

A bank is simply a business firm that issues claims to a fixed sum of money in receipt for a deposit of cash. These claims are payable on demand and without cost to the depositor. In today’s world these claims may take the form of checkable deposits, so called because they can be transferred to a third party by writing out a check payable to the party named on the check. They may also take the form of so-called “savings” deposits with limited or no checking privileges and that require withdrawal in person at one of the bank’s branches or at an ATM. In the United States, the cash for which the claim is redeemable are Federal Reserve notes — the “dollar bills” that we are all familiar with.

Fractional-reserve banking occurs when the bank lends or invests some of its depositors’ funds and retains only a fraction of the deposits in cash. This cash is the bank’s reserves. Hence the name fractional-reserve banking. All commercial banks and thrift institutions in the United States today engage in fractional–reserve banking.

Let me illustrate how fractional-reserve banking works with a simple example. Assume that a bank with deposits of $1 million makes $900,000 of loans and investments. If we ignore for simplicity the capital paid in by its owners, this bank is holding a cash reserve of 10 percent against its deposit liabilities. The deposits constitute the bank’s liabilities because the bank is contractually obligated to redeem them on demand. The assets of the bank are its reserves, loans, and investments. Bank reserves consist of the dollar bills in its vaults and ATMs and the bank’s deposits at the Federal Reserve, which can be cashed on demand for dollar bills printed by the Bureau of Engraving and Printing at the order of the Fed. The bank’s loans and securities are noncash assets that are titles to sums of cash payable only in the near or distant future. These assets include short-term business loans, credit-card loans, mortgage loans, and the securities issued by the US Treasury and foreign financial authorities.

Now the key to understanding the nature of fractional-reserve banking and the problems it creates is to recognize that a bank deposit is not itself money. It is rather a “money substitute,” that is, a claim to standard money — dollar bills — universally regarded as perfectly secure.

Bank deposits transferred by check or debit card will be routinely paid and received in exchange in lieu of money only as long as the public does not have the slightest doubt that the bank that creates these deposits is able and willing to redeem them without delay or expense.

Under these circumstances, bank deposits are eagerly accepted and held by businesses and households and regarded as indistinguishable from cash itself. They are therefore properly included as part of the money supply, that is, the total supply of dollars in the economy.

The very nature of fractional-reserve banking, however, presents an immediate problem. On the one hand, all of a bank’s deposit liabilities mature on a daily basis, because it has promised to cash them in on demand. On the other, only a small fraction of its assets is available at any given moment to meet these liabilities. For example, during normal times, US banks effectively hold much less than 10 percent of deposits in cash reserves. The rest of a bank’s liabilities will only mature after a number of months, years, or, in the case of mortgage loans, even decades. In the jargon of economics, fractional-reserve banking always involves “term-structure risk,” which arises from the mismatching of the maturity profile of its liabilities with that of its assets.

In layman’s terms, banks “borrow short and lend long.” The problem is revealed when demands for withdrawal of deposits exceeds a bank’s existing cash reserves. The bank is then compelled to hastily sell off some of its longer-term assets, many of which are not readily saleable. It will thus incur big losses. This will cause a panic among the rest of its depositors who will scramble to withdraw their deposits before they become worthless. A classic bank run will ensue. At this point the value of the bank’s remaining assets will no longer be sufficient to pay off all its fixed-dollar deposit liabilities and the bank will fail.

A fractional-reserve bank, therefore, can only remain solvent for as long as public confidence exists that its deposits really are riskless claims on cash. If for any reason — real or imagined — the faintest suspicion arises among its clients that a bank’s deposits are no longer payable on demand, the bank’s reputation as an issuer of money substitutes vanishes overnight. The bank’s brand of money substitutes is then instantly extinguished and people rush to withdraw their deposits in cash — cash that no fractional-reserve bank can provide on demand in sufficient quantity. Thus the threat of brand extinction and insolvency is always looming over fractional-reserve banks.

In other words, a fractional-reserve bank must develop what Ludwig von Mises called a “special kind of good will” in order to create a clientele who treats their deposits as money substitutes. On a free market this kind of good will is very difficult and costly to acquire and maintain. This reputational asset is what induces a bank’s clients to forebear from immediately cashing in their deposit claims and driving the bank into instant insolvency. Of course to remain profitable the bank must also build up conventional business good will, which depends upon convenient geographical location, outstanding customer service, attractive facilities, the reputation of its management team and so on. But unlike the common form of good will essential to all successful business ventures, the good will that is necessary for a particular bank’s brand of deposits to circulate as money substitutes is indivisible. In almost all other industries, customer good will can be gained or lost in marginal units and does not typically vanish all at once, destroying its product brand and plunging the firm into immediate insolvency.

Ludwig von Mises described the loss of confidence in a bank’s solvency and the related phenomenon of brand extinction in the following terms:

The confidence which a bank and the money-substitutes it has issued enjoy is indivisible. It is either present with all its clients or it vanishes entirely. If some of the clients lose confidence the rest of them lose it too.… One must not forget that every bank issuing fiduciary media is in a rather precarious position. Its most valuable asset is its reputation. It must go bankrupt as soon as doubts arise concerning its perfect trustworthiness and solvency. [1]

The issuing of deposits not fully backed by cash is therefore always a precarious business on the free market. The slightest doubt about the bank’s solvency among even some of its clients will instantly destroy the character of its deposits as money substitutes. Furthermore, the loss of confidence that causes this phenomenon of “brand extinction” is the cause and not the result of a run on the bank and cannot be deterred by a high ratio of reserves to deposits. For under fractional-reserve banking, by definition, reserves are always insufficient to pay off all the demand liabilities that the bank has incurred. In fact the level of cash reserves is not directly relevant to the stability of a bank. It is simply one of several factors that a bank’s clients take into account in forming their subjective judgment concerning whether a bank’s brand of notes and deposits are or are not money substitutes. For example in the 19th century the ratio of gold reserves to notes and deposits of the Bank of England are reported to have been as low as 3 percent, yet it was generally regarded as one of the most stable financial institutions in the world.

The peculiar and overriding importance of public confidence in sustaining fractional-reserve banking was particularly emphasized by Murray N. Rothbard:

But in what sense is a bank “sound” when one whisper of doom, one faltering of public confidence, should quickly bring the bank down? In what other industry does a mere rumor or hint of doubt bring down a mighty and seemingly solid firm? What is it about banking that public confidence should play such a decisive and overwhelmingly important role? The answer lies in the nature of our banking system, in the fact that both commercial banks and thrift banks have been systematically engaging in fractional-reserve banking: that is, they have far less cash on hand than there are demand claims to cash outstanding.[2]

Rothbard’s point about the extreme fragility of public confidence in issuers of fractionally-backed money substitutes is well illustrated by the stunning collapse of Washington Mutual (WaMu) in September 2008, the largest bank failure in United States history. WaMu had been in existence for 119 years and was the sixth-largest bank in the United States with assets of $307 billion. It had branches throughout the country and billed itself as the Walmart of banking. It was one of the top performers on Wall Street until shortly before its failure. Its depositors clearly had enormous confidence in its solidity, especially given that its deposits were insured by the federal government reinforced by the existence of the Fed’s “too-big-to-fail” policy. And yet, almost overnight the special good will that gave its deposits the quality of money substitutes vanished as panic-stricken depositors rushed to withdraw their funds. The unlikely event that triggered the sudden loss of confidence and subsequent brand extinction was the failure of Lehman Brothers, a venerable investment house. A week after Lehman failed, mighty WaMu was no more.

The highly publicized Lehman Brothers failure had shaken public confidence in the solvency not only of WaMu but of the entire banking system. Had the Fed and Treasury not acted aggressively to bail out the largest banks in the fall of 2008, there is no doubt that the entire system would have collapsed in short order. Indeed on a single day in December, the combined emergency lending by the Fed and the US Treasury had risen to a peak of $1.2 trillion. The recipients of these billions included some of the most trusted and reputable brand names in banking: Citibank, Bank of America, Morgan Stanley, as well as European banks like the Royal Bank of Scotland and UBS AG. Without this unprecedented bailout, these discredited brand names would have been relegated to the dustbin of business history

The ever-present threat of insolvency is a relatively minor problem with fractional-reserve banks, however. Its effects are restricted to the bank’s stockholders, creditors, and depositors who voluntarily assume the peculiar risks involved in this business.

The major problems with fractional-reserve banking are its harmful effects on the overall economy caused by the related phenomena of inflation and business cycles.

First, fractional-reserve banking is inherently inflationary. When a bank lends out its clients’ deposits, it inevitably expands the money supply. For example, when people deposit an additional $100,000 of cash in the bank, depositors now have an additional $100,000 in their checking accounts while the bank accumulates an additional $100,000 of cash (dollar bills) in its vaults. The total money supply, which includes both dollar bills in circulation among the public and dollar balances in bank deposits, has not changed. The depositors have reduced the amount of cash in circulation by $100,000, which is now stored in the bank’s vaults, but they have increased the total deposit balance that they may draw on by check or debit card by the exact same amount. Suppose now the loan officers of the bank lend out $90,000 of this added cash to businesses and consumers and maintain the remaining $10,000 on reserve against the $100,000 of new deposits. These loans increase the money supply by $90,000 because, while the original depositors have the extra $100,000 still available on deposit, the borrowers now have an extra $90,000 of the cash they did not have before.

The expansion of the money supply does not stop here however, for when the borrowers spend the borrowed cash to buy goods or to pay wages, the recipients of these dollars redeposit some or all of these dollars in their own banks, which in turn lend out a proportion of these new deposits. Through this process, bank-deposit dollars are created and multiplied far beyond the amount of the initial cash deposits. (Given the institutional conditions in the United States today, each dollar of currency deposited in a bank can increase the US money supply by a maximum of $10.00.) As the additional deposit dollars are spent, prices in the economy progressively rise, and the inevitable result is inflation, with all its associated deleterious effects on the economy.

Fractional-reserve banking inflicts another great harm on the economy. In order to induce businesses and consumers to borrow the additional dollars created, banks must reduce interest rates below the market-equilibrium level determined by the amount of voluntary savings in the economy. Businesses are misled by the artificially low interest rates into borrowing to expand their facilities or undertake new long-term investment projects of various kinds. But the prospective profitability of these undertakings depends on expectations that bank credit will remain cheap more or less indefinitely. Consumers, too, are deceived by the lower interest rates and rush to purchase larger residences or vacation homes. They take out second mortgages on their homes to buy big-ticket luxury items. A false economic boom begins that is doomed to turn into a bust as soon as interest rates begin to rise again.

As the inflationary boom progresses and prices rise, the demand for credit becomes more intense at the same time that more cash is withdrawn from bank deposits to finance the purchase of everyday goods. The banks react to these developments by sharply raising interest rates and contracting loans and deposits, causing a decline in the money supply. Indeed the money supply may very well collapse, as it did in the early 1930s, because the public loses confidence in the banks and demands it deposits back in cash. In this case, a series of bank runs ensue that pushes many fractional-reserve banks into insolvency and instantly extinguishes their money substitutes, which had previously circulated as part of the money supply. Recession and deflation results and the binge of bad investments and overconsumption is starkly revealed in the abandoned construction projects, empty commercial buildings, and foreclosed homes that litter the economic landscape. At the end of the recession it turns out that almost all households and business firms are made poorer by fractional-reserve bank-credit expansion, even those who may have initially gained from the inflation.

Inflation and the boom-bust cycles generated by fractional-reserve banking are enormously intensified by Federal Reserve and US-government interference with the banking industry. Indeed, this interference is justified by economists and policymaker precisely because of the instability of the fractional-reserve system. The most dangerous forms of such interference are the power of the Federal Reserve to create bank reserves out of thin air via open market operations, its use of these phony reserves to bail out failing banks in its role as a lender of last resort, and federal insurance of bank deposits. In the presence of such polices, the deposits of all banks are perceived and trusted by the public as one homogeneous brand of money substitute fully guaranteed by the Federal government and backed up by the Fed’s power to print up bank reserves at will and bail out insolvent banks. Under the current monetary regime, there is thus absolutely no check on the natural propensity of fractional-reserve banks to mismatch the maturity profiles of their assets and liabilities, to expand credit and deposits, and to artificially depress interest rates. Without fundamental change in the US monetary system, the growth of bubbles in various sectors of the economy and subsequent financial crises will continue unabated.

The solution is to treat banking as any other business and permit it to operate on the free market — a market completely free of government guarantees of bank deposits and of the possibility of Fed bailouts. In order to achieve the latter, federal deposit insurance must be phased out and the Fed would have to be permanently and credibly deprived of its legal power to create bank reserves out of nothing. The best way to do this is to establish a genuine gold standard in which gold coins would circulate as cash and serve as bank reserves; at the same time the Fed must be stripped of its authority to issue notes and conduct open-market operations. Also, banks would once again be legally enabled to issue their own brands of notes, as they were in the 19th and early 20th century.

Once this mighty rollback of government intervention in banking is accomplished, each fractional-reserve bank would be rigidly constrained by public confidence when issuing money substitutes. One false step — one questionable loan, one imprudent emission of unbacked notes and deposits — would cause instant brand extinction of its money substitutes, a bank run, and insolvency.

In fact on the banking market as I have described it, I foresee the ever-present threat of insolvency compelling banks to refrain from further lending of their deposits payable on demand. This means that if a bank wished to make loans of shorter or longer maturity, they would do so by issuing credit instruments whose maturities matched the loans. Thus for short-term business lending they would issue certificates of deposits with maturities of three or six months. To finance car loans they might issue three-year or four-year short bonds. Mortgage lending would be financed by five- or ten-year bonds. Without government institutions like Fannie Mae and Freddie Mac — backed by the Fed’s money-creating power — implicitly guaranteeing mortgages, mortgage loans would probably be transformed into shorter five- or ten-year balloon loans, as they were until the 1930s. The bank may retain an option to roll over a mortgage loan when it comes due pending a reevaluation of the mortgagor’s current financial situation and recent credit history as well as the general economic environment. In short, on a free market, fractional-reserve banking with all its inherent problems would slowly wither away.

Notes

[1] Ludwig von Mises, Human Action: A Treatise on Economics. Scholar’s Ed. (Auburn, AL: Ludwig von Mises Institute, 1998), pp. 442, 444.

[2] Murray N. Rothbard, Making Economic Sense, 2nd ed. (Auburn, AL: Ludwig von Mises Institute, 2006), p. 326.

Joseph Salerno is academic vice president of the Mises Institute, professor of economics at Pace University, and editor of the Quarterly Journal of Austrian Economics. He has been interviewed in the Austrian Economics Newsletter and on Mises.org. Send him mail. See Joseph T. Salerno’s article archives.

This is a revised version of written testimony submitted to the the Subcommittee on Domestic Monetary Policy and Technology of the Committee on Financial Services, US House of Representatives “Fractional Reserve Banking and Central Banking as Sources of Economic Instability: The Sound Money Alternative,” June 28, 2012.

You can subscribe to future articles by Joseph T. Salerno via this RSS feed.

Copyright © 2012 by the Ludwig von Mises Institute. Permission to reprint in whole or in part is hereby granted, provided full credit is given.

Not Enough Inflation? – Article by Tyler Watts

Not Enough Inflation? – Article by Tyler Watts

The New Renaissance Hat
Tyler Watts
July 15, 2012
******************************

Two wrongs may not make a right, but a second dose of poison might just cure the first dose. That’s at least what Paul Krugman, America’s most prominent left-wing economic pundit, is saying about an untapped remedy for our economic woes. In his April 5 New York Times column, “Not Enough Inflation,” Krugman repeated his claim that “a bit more inflation would be a good thing, not a bad thing.”

If you’re wondering how progressively higher prices for everyday goods could help any household get ahead economically, let alone contribute to overall economic recovery, you’re in good company. As all econ-principles students know, inflation is caused by an increase in the supply of money relative to money demand. The increase in consumer goods prices—that’s how the layman defines and experiences inflation—is really just a symptom of the reduced purchasing power of money caused by the increase in its quantity. The higher prices for all goods in turn mean lower real incomes for consumers—which is all of us—not to mention that inflation is also typically symptomatic of the boom-bust business cycle and can cause significant widespread economic damage. In its most severe forms, inflation can wipe out people’s monetary wealth and bring commerce to a halt.

But smart guys like Professor Krugman aren’t mere monetary cranks. They know that high inflation is economically dangerous. What they’re asking for is just a small, temporary dose of fresh money to inject some new life into the economy. There is a kernel of truth to this inflationary prescription. As the Scottish philosopher David Hume explained in his 1752 essay Of Money, prices for different kinds of goods react differently to new money entering the economy. Generally speaking, commodities or consumer goods prices will rise faster than wages. So for a manufacturing entrepreneur, for instance, who employs many workers, inflation will cause output prices (revenue) to increase relative to wages (costs), bringing an increase in profits that will induce an increase in output. Therefore, in Hume’s terms, an increase of money “must first quicken the diligence of every [entrepreneur], before it increase the price of labor.”

This “sticky wages” effect is what economists like Hume, John Maynard Keynes, and Krugman have in mind when advocating inflationary stimulus. Krugman also notes that “parts of the private sector continue to be crippled by the overhang of debt accumulated during the bubble years,” and that “modest inflation . . . by eroding the real value of that debt . . . [would] help promote the private-sector recovery.” So higher inflation not only increases the demand for labor, but can also help clean up companies’ and individuals’ balance sheets, giving them the ability to ramp up their hiring and spending. What’s not to love about this miracle elixir?

There are two big problems with inflationary stimulus. The first involves the process dynamics of the market economy. The inflationists tend to omit the rest of the story, which involves the long-run effects of new money. New money will eventually increase all prices—even wages—meaning the stimulus effect can only be temporary. For if entrepreneurs read the price increases not as mere inflation, but higher demand for their products (as the inflationists hope), they are liable to make investments to expand their production capacity. Once the inflation effect peters out, once rising wages eventually push profits back down, they find that extra production is no longer profitable. The expansion can’t be sustained without more inflationary stimulus.

In a rising inflation environment, moreover, people will eventually come to anticipate further price increases. Workers demand upward wage adjustments in advance, and entrepreneurs anticipate rising costs and thus scale back their expansion plans. Once people catch on to inflationary stimulus in this fashion, larger and larger money injections (that is, higher inflation rates) are needed to merely maintain output levels. At some point, the high, rising, and volatile inflation rate itself becomes a drag on the economy. Miscalculation of next year’s, or even next month’s, inflation rate could spell disaster for entrepreneur and worker alike. As inflation heats up, it can actually drag investment down, as people seek to shelter their wealth in “sterile” assets like gold. Inflation, instead of a stimulus factor, becomes a source of economic confusion and frustration. Iconic images of people hauling wheelbarrow loads of money to buy a loaf of bread in post-World War I Germany remind us of the potential economic turmoil of unchecked inflation. This of course is not what Krugman has in mind, but we should not forget that the mightiest river begins as a trickle.

The second big problem with inflation is a moral one. Along with causing economic confusion, inflation redistributes wealth. The key fact here, again, is that not all prices rise immediately when new money enters circulation. People who are first to receive the new money get to spend it before prices go up. Those last in line see prices go up before their own incomes do. Inflation also redistributes wealth from lenders to borrowers, as Krugman indicated, by reducing the real value of debt. But Krugman conveniently ignores the corresponding fact that, whenever a borrower’s real debt burden is eased, a lender’s asset value is eroded. Thus to use inflation as a partial bailout for borrowers is to harm lenders and investors. This is happening already—even at “mild” inflation rates that are too low for Krugman’s tastes, real returns on investments like bank CDs are driven into negative territory.

Through these redistributions of purchasing power, inflation acts like a tax: a tax on savers, on investors, on those at the very end of the monetary policy food chain. Ironically for Progressives like Krugman, this inflation tax arguably hits the poor and uneducated hardest. Educated, economically sophisticated people know the warning signs of inflation and know how to shelter their assets—as attested by the flurry of gold bullion dealers’ ads on cable news and AM radio. The poor are much more likely to be wage earners whose incomes tend to lag inflation, or pensioners who, even with annual cost-of-living adjustments, can still see consistent reductions in their purchasing power.

Nonetheless, Krugman and the inflation party don’t understand the free-market camp’s arguments against inflation. He accuses us of “obsessing” over inflation, while he thinks the Fed should focus on curing unemployment. Even conceding that inflation can provide a temporary, halting employment stimulus, the objection remains strong. It comes down to the fact that inflation is a big lie—or, should we say, a million little lies, because inflation distorts all prices and thereby hinders their crucial function of giving entrepreneurs and workers the correct information and incentives on which to make the best economic decisions. Inflation’s promises of faster growth and greater wealth are illusory. Like alcohol or drug abuse, every high begets a crash that demands larger and larger doses to maintain the effect. Inflation is a dangerous medicine that stands to do the patient more harm than good.

Tyler Watts is an assistant professor of economics at Ball State University and the winner of the 2012 Beth A. Hoffman Memorial Prize for Economic Writing.

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.