Browsed by
Category: Economics

UN “Green Climate” Program Is a Slush Fund for Dictators – Article by Marian L. Tupy

UN “Green Climate” Program Is a Slush Fund for Dictators – Article by Marian L. Tupy

The New Renaissance HatMarian L. Tupy
******************************

The fund is planned to be $450 billion by 2020

Wherever you stand on the subject of global warming, pay close attention to one under-reported aspect of the 2015 United Nations Climate Change Conference or Paris Agreement. I am referring to the Green Climate Fund (GCF), which is a financial mechanism intended “to assist developing countries in adaptation and mitigation practices to counter climate change.”

According to the current estimates, developed countries will be obliged to contribute up to $450 billion a year by 2020 to the GCF, which will then “redistribute” the money to developing countries allegedly suffering from the effects of global warming.

Lo and behold, Zimbabwe’s government-run daily “newspaper” The Herald reported that “Southern Africa is already counting the costs of climate change-linked catastrophes… In Zimbabwe, which has seen a succession of droughts since 2012, a fifth of the population is facing hunger… Feeding them will cost $1.5 billion or 11 percent of … the Gross Domestic Product.”

No doubt Robert Mugabe, the 91-year-old dictator who has ruled Zimbabwe since 1980, is salivating at the prospect of some global warming cash. Beginning in 2000, Mugabe started to expropriate privately-held agricultural land. The result of what is euphemistically called “land reform” was a monumental fall in productivity and the second highest bout of hyperinflation in recorded history.

slush1Some three million of Zimbabwe’s smartest people, including tens of thousands of doctors and lawyers, have left the country. Most of those who have remained behind are subsistence farmers with very little wealth. There is, in other words, very little loot left for the government to steal.

slush2

Thankfully for the Zimbabwean dictator, there are plenty of gullible Westerners willing to believe that the frighteningly vile, comically incompetent government isn’t at the root of Zimbabwe’s food shortages, but that global warming is to blame.

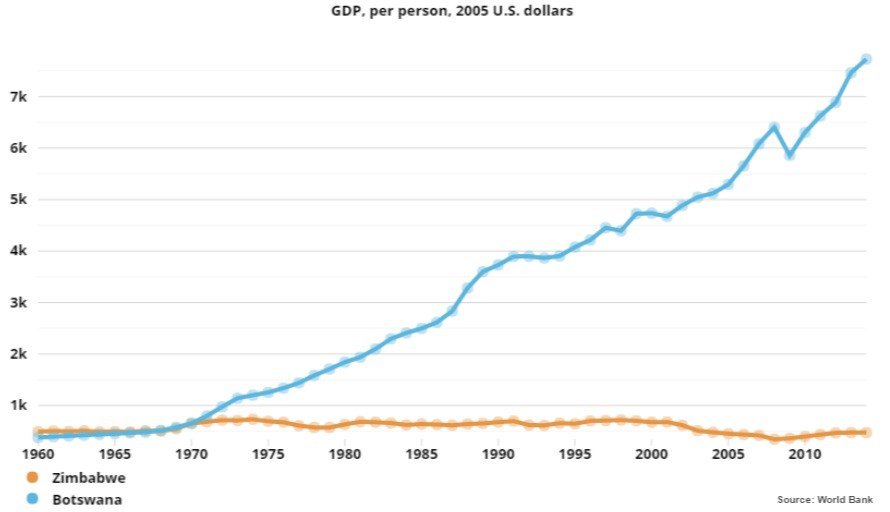
Of course, this is pure nonsense. Botswana and Zimbabwe share a border and their climate and natural resources are exceptionally similar. Yet, since 2004, food production has increased by 29 percent in Botswana, while declining by 9 percent in Zimbabwe. It is not drought but government policies that make nations starve!

slush3

As befits a dictatorship, Zimbabwe is one of the most corrupt places on earth. The notion that GCF funds will be will used for environmental “adaptation and mitigation” is a dangerous fantasy.

Like much foreign aid before it, most of the “green aid” money will likely end up in the pockets of some of the cruelest and most corrupt people on earth. Congress must stand firm and refuse to appropriate any money for the fund.

slush4

This post first appeared at Human Progress.

Marian L. Tupy is the editor of HumanProgress.org and a senior policy analyst at the Center for Global Liberty and Prosperity. 

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution 4.0 International License, which requires that credit be given to the author.

Why Negative Interest Rates Will Fail – Article by Frank Hollenbeck

Why Negative Interest Rates Will Fail – Article by Frank Hollenbeck

The New Renaissance HatFrank Hollenbeck
******************************

It is now just a matter of time before the US central bank follows the central banks of Japan, the EU, Denmark, Sweden and Switzerland in setting negative rates on reserve deposits.

The goal of such rates is to force banks to lend their excess reserves. The assumption is that such lending will boost aggregate demand and help struggling economies recover. Using the same central bank logic as in 2008, the solution to a debt problem is to add on more debt. Yet, there is an old adage: you can bring a horse to water but you cannot make him drink! With the world economy sinking into recession, few banks have credit-worthy customers and many banks are having difficulties collecting on existing loans.

Italy’s non-performing loans have gone from about 5 percent in 2010 to over 15 percent today. The shale oil bust has left many US banks with over a trillion dollars of highly risky energy loans on their books. The very low interest rate environment in Japan and the EU has done little to spur demand in an environment full of malinvestments and growing government constraints.

Central bank policies have also driven government bond yields into negative territory. Nearly $7 trillion of government bonds are currently trading at negative rates.

But, economic theory presupposes that negative rates are an impossibility. After all, why would you buy a one-year treasury bill for $1,005 that will get you $1,000 in a year, when you can stuff your mattress with the $1,005 and still have $1,005 in a year? Some would say that storing money is costly and risky, but that is also true for most assets.

The reason is actually quite simple and shows how distortive monetary policy has become worldwide: It makes sense to purchase a bill for $1,005 if you intend to sell it before it matures to the central bank for more than $1,005. In today’s world, the central bank is often ultimately expected to purchase the bill and lose money on it. It’s just another type of debt monetization.

(And it is, by the way, something the Germans emphatically wanted to avoid when the ECB was initially created.)

We Just Need to Print More Money!
The real problem is the way monetary policy is taught in almost every undergraduate and graduate program in the world. Pick up any macroeconomics textbook and it will explain how interest rates are determined by the demand and supply of liquidity. The economy is treated as a car, and interest rates are viewed as the gas petal. When reality does not match up with the model, today’s economist, instead of questioning the model and theory, assumes that more of the same will ultimately force reality into the model.

The problem arises from a fundamental misunderstanding about the role of interest rates. Mises in 1912 had this to say about our current enlightened view on money:

[This view of money] regards interest as a compensation of the temporary relinquishing of money in the broader sense — a view, indeed, of unsurpassable naiveté. Scientific critics have been perfectly justified in treating it with contempt; it is scarcely worth even cursory mention. But it is impossible to refrain from pointing out that these very views on the nature of interest holds an important place in popular opinion, and that they are continually being propounded afresh and recommended as a basis for measures of banking policy.

In fact, interest rates reflect the ratio of the value assigned to current consumption relative to the value assigned to future consumption. That is, money isn’t just some commodity that can solve our problems if we just create more of it. Money serves a key function of coordinating output with demand across time.

So, the more you interfere with interest rates, the more you create a misalignment between demand and supply across time, and the greater will be the adjustment to realign output with demand to return the economy to sustainable economic growth with rising standards of living (see here and here). Negative rates will only ensure an ever greater misalignment between output and demand.

As with Japan, Western economies that pursue a long-term policy of low or negative interest rates can expect decades of low growth unless these “unorthodox” monetary policies are rapidly abandoned. Recessions are not a problem of insufficient demand. They are a problem of supply being misaligned with demand.

The War on Cash
Meanwhile, a goal of some of the attendees at Davos and others has been to push the world toward a cashless society since an increase in cash holdings would limit the effectiveness of negative rates. They know that if they eliminate cash, central banks will have greater control over the money supply and the ability to guide the economy toward their macroeconomic goals.

As long as there is physical cash, people will hold cash in times of uncertainty. It is a wise alternative when all other options seem unproductive or irrational — and keeping cash in a bank at a time of negative rates is, all things being equal, irrational. Central banks, not surprisingly, would therefore like to take away the ability to hold cash outside the banking system. Worst of all, people who hold cash outside the system might be saving it instead of spending it. Naturally, from the Keynesian perspective, this must be stopped.

This is just the latest frontier in the radical monetary policy we’ve been increasingly witnessing since the 2008 financial crisis. The best monetary policy, however, is no monetary policy at all, and central bankers should take an extended holiday so that the world economy can finally heal itself.

Frank Hollenbeck teaches finance and economics at the International University of Geneva. He has previously held positions as a Senior Economist at the State Department, Chief Economist at Caterpillar Overseas, and as an Associate Director of a Swiss private bank.

This article was published on Mises.org and may be freely distributed, subject to a Creative Commons Attribution United States License, which requires that credit be given to the author.

What Markets Are Telling Us – Article by Ron Paul

What Markets Are Telling Us – Article by Ron Paul

The New Renaissance HatRon Paul
******************************
Last week US stock markets tumbled yet again, leaving the Dow Jones index down almost 1500 points for the year. In fact, most major world markets are in negative territory this year. There are many Wall Street cheerleaders who are trying to say that this is just a technical correction, that the bottom is near, and that everything will be getting better soon. They are ignoring the real message the markets are trying to send: you cannot print your way to prosperity.

People throughout history have always sought to acquire wealth. Most of them understand that it takes hard work, sacrifice, savings, and investment. But many are always looking for that “get rich quick” scheme. Monetary cranks throughout history have thought that just printing more money would result in greater wealth and prosperity. Every time this was tried it resulted in failure. Huge economic booms would be followed by even larger busts. But no matter how many times the cranks were debunked both in theory and practice, the same failed ideas kept coming back.

The intellectual descendants of those monetary cranks are now leading the world’s central banks, which is why the last decade has seen an explosion of money creation. And what do the central bankers have to show for it? Lackluster employment numbers that have not kept up with population growth, increasing economic inequality, a rising cost of living, and constant fear and uncertainty about what the future holds.

The past decade has been a lot like the 1920s, when prices would have dropped without intervention, but the Federal Reserve kept the price level steady through injections of easy money into the economy. The result in the 1920s was the Great Depression. But in the 1920s prices were dropping because of increased production. More goods being produced meant lower prices, which the Fed then tried to prop up by printing money. Unlike the “Roaring 20s” however, the economy isn’t quite as strong today. It’s more of a gasp than a roar.

Production today is barely above 2007 levels, while heavily-indebted households already hurt during the financial crisis don’t want to keep spending. The bad debts and mal-investments from the last Federal Reserve-induced boom were never liquidated, they were merely papered over with more easy money. The underlying economic fundamentals remain weak but the monetary cranks who run the Fed keep trying to pump more and more money into the system. They fail to realize that easy money is the cause, not the cure, of recessions and depressions. They didn’t realize that prices needed to drop in order to clear all the bad debt and mal-investments out of the system. Because they don’t realize that, we are on the verge of yet another financial crisis.

Don’t be confused by any stock market rallies over the next few months and think that the worst is over. Remember that after Black Tuesday in 1929 the Dow Jones rallied over the next year before it began slowly and steadily to sink again. The central bankers will do everything they can to delay the inevitable. If they had allowed housing prices to fall in 2008 and hadn’t bailed out the big Wall Street banks, the economy would have corrected itself. Yes, it would have been a severe correction, but it would have been nothing compared to the inevitable correction that will present itself when the Fed runs out of easy money options. The Fed may try to cut interest rates again, maybe even going negative, or it will do more quantitative easing, but that won’t work. Creating more money does not lead to economic growth and well-being. The more money the Federal Reserve creates, the more ordinary Americans will end up suffering.

Ron Paul, MD, is a former three-time Republican candidate for U. S. President and Congressman from Texas.

This article is reprinted with permission from the Ron Paul Institute for Peace and Prosperity.

Why Free-Market Advocates Are Not Obligated to Defend the Economic Status Quo – Article by G. Stolyarov II

Why Free-Market Advocates Are Not Obligated to Defend the Economic Status Quo – Article by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
******************************

Many on the political left today equate advocacy of free-market capitalism with an “anything goes” support for the economic status quo. Many on the political right give credence to this perception by, indeed, seeking to defend the status quo just because it happens to be so. Yet this is neither an obligatory nor an advisable approach for characterizing a genuinely well-considered free-market outlook.

Suppose that you are a free-market advocate and also an engineer, well-versed in the principles and methods for constructing durable, safe structures. You hold that individuals and businesses should have the freedom to be able to build structures which would improve human well-being, in exchange for the opportunity to earn a profit (or not, if they wish to build structures for a charitable purpose). Now suppose that you are tasked with evaluating the integrity of a particular structure constructed by a private business – perhaps a bridge. This particular bridge happens to be fully privately funded – no subsidies, no exclusive rights, no barriers to competitors’ entry. The business undertaking the construction intends for the bridge to be used as part of a major new toll road that is intended to carry massive amounts of traffic.

Unfortunately, upon deploying your technical skillset and studying the bridge design carefully, you find that the bridge, while it is represented as being able to withstand one thousand cars at a time, would in fact collapse under the weight of only five hundred cars. You also find that, in your basic repertoire of engineering techniques, you have knowledge of construction techniques and superior materials which would rectify these design flaws and enable the bridge to be as safe and as durable as originally represented. The trouble is that the business owners want to hear none of it. They are attached to their original design partly out of cost considerations, but mostly because they simply cannot understand your findings or appreciate their significance, no matter how many different ways you have attempted to communicate them. The business owners have almost no engineering knowledge themselves and are generally contemptuous of overtly mathematical, “nerdy” types (like you). They are skilled salespeople who have capital from a previous venture and are eager to make additional money on a high-profile project such as this bridge. Suppose that you know that you have all of the technical knowledge of your discipline firmly on your side, but it is the owners’ money on the line, so, unconvinced by your arguments, they build the bridge according to their original specifications. They still advertise it as highly durable, but in a sufficiently nebulous way that the advertisements do not truly make any specific promises or technical claims. (This business is short on technically knowledgeable professionals, but spares no expense in hiring attorneys to litigation-proof its marketing materials.) The driving public’s impression from the marketing campaign is expected to be, “It is an incredibly sturdy, state-of-the-art, daring new bridge that you will enjoy driving on in safety and style.” The business owners contend that there is no problem. After all, were this a truly free market, the public could choose to pay to use their bridge or to find some alternative in getting from point A to point B. And competitors could build their own bridges, too, if they could buy the land, purchase the tools and materials, and hire the labor to do it.

Of course, on most days, this bridge would not collapse, since it is rare for five hundred cars to be on it simultaneously. The owners could well be reaping profits from their bridge for years and convince the lay public to drive on it with no visible ill consequences during that time. The bridge is, however, vulnerable to high winds, earthquakes, freezing damage, and gradual deterioration over time (exacerbated by substandard construction). As time passes, the risks of collapse increase. No bridge is invulnerable, but this particular bridge is about 30 years farther along the path to decay than other bridges that you know could easily have been built in its place, had the owners only listened to you. As a free-market advocate, you have some sympathies with the owners’ view that the construction of the bridge should not be forcibly prevented, as they are using their own property for their own chosen purposes, and they are not forcing anyone to use it. However, as an engineer who knows better when it comes to quality of bridge design and construction, what do you do?

This dilemma illustrates a question at the core of how free-market advocates approach the world in which they find themselves – a world, of course, which is far from free in an economic sense, but where many people still use their own property for their own purposes. There are some who will assert that the very fact of private, voluntary use of property renders such use inherently above criticism, provided it is a manifestation of free choice. (We can overlook, for the sake of this argument, the fact that, in the real world, many incentives and constraints upon human action are routinely distorted by the effects of political influences in favor of one group or set of outcomes and/or in opposition to others.) In this argument’s more typical instantiation in today’s world, some would assert that any outcome of “private enterprise” in today’s world must be acceptable for free-market advocates, since it was (ostensibly) somebody’s use of private property for a private purpose. For example, mass corporate layoffs (virtually unheard of until the 1970s), raising the price of a life-saving, long-generic drug by 5,556 percent (as pharmaceutical executive Martin Shkreli did with Daraprim in 2015), listening to or creating brutal “gangsta rap” (virtually unheard of until the 1990s), teaching of creationism in private schools (common throughout history, but increasingly untenable in the face of over 150 years of mounting evidence), and many other behaviors of questionable rationality and/or taste are defended as being the decisions of private entities – so what could be wrong about them?

The problem with reflexively defending any and every behavior, just because a private entity undertakes it, even in the absence of market distortions, is that it misses an essential point. The market is nothing more than the sum of the choices and actions of its participants. A market outcome is not a Panglossian “best of all possible worlds” scenario. Even in the absence of compulsion or restraint, some people will be mistaken, irrational, overconfident, immoral, confused, or all of the above. Ex ante, they may expect that the transactions and behaviors they engage in will benefit them – much like a tribal shaman might believe that his rain dance would bring forth water for the tribe’s crops – but, ex post, they may well find themselves regretting their behavior, or even if not, they may have still become materially, intellectually, or emotionally worse off from it compared to the alternatives. In addition to choice, there is also truth – which comes in the form of scientific, mathematical, historical, and philosophical principles and facts. Truth is an outcome of combining induction from the empirical facts of reality with deduction from the application of logical reasoning to known facts and incontrovertible first principles. It is entirely possible for a person – including a wealthy, powerful, influential person whose decisions affect thousands or millions of others – to completely miss what the truth is, or even to be ignorant of the correct methods of arriving at the truth. In other words, if the external reality is objective and governed by comprehensible natural laws – and if morality is also objective in the sense that some outcomes are incontrovertibly more beneficial to human well-being than others – then it must be the case that somebody who is thinking in a rational, well-informed manner can truly “know better” than a particular decision-maker who is not.

Does that mean that the market could be replaced by some “superior” system of decision-making? Ultimately, no. We have no guarantee that any substitution of decision-making for that of private actors could lead to a necessarily preferable result from those decision makers’ free choices. If Person A is irrational and mistaken, we have no guarantee that leaving Person B in charge of A’s life would not lead to even more irrational and mistaken choices, compounded by the knowledge problem that B will necessarily have in relation to A’s situation. The possibility that B could be not simply misguided but nefarious, and seek to sacrifice A’s genuine interests in favor of B’s own, is a further argument against this kind of command-and-control approach. More devastating, however, would be an outcome in which a different person, C, really is doing his best to act in a truthful, rational, and just manner, but the controller B does not see it. Or perhaps B does see it and thinks it is all well and good, but B needs to set uniform standards that would keep the lowest common denominator in check, and C’s scrupulous, innovative, and principled way of living could never be generalized to a society-wide system of controls.

But getting back to you, the engineer: How to address the dilemma that you are in? Has the “market” not “decided” that the bridge of substandard technical quality is just fine? Not so fast. We must never forget that we are the market, and that the market does not only consist of the first decisions and inclinations of some small group of wealthy, powerful, or connected individuals. Quite the contrary: We are what a truly free market consists of. A truly free market consists not only of our affirmative choices, but also of our negations and criticisms of certain other choices. It consists of our knowledge, including those situations where we truly “know better” than certain others. You, the free-market engineer, could not force the bridge owners to change their design. However, you could fully publicize its flaws in a fully free society, one characterized by robust protections of free speech and lack of a climate of frivolous litigation with regard to libel laws. If today such professional criticism is difficult, it is because many larger, politically connected enterprises will hire legions of attorneys to squelch sufficiently specific assertions in meritless litigation that is too costly for ordinary people to counter. But a truly free society would lack this obstacle and would include a legal system that is designed with speed, simplicity, affordability, and protections for peaceful natural persons in mind. A corporation would not be able to sue you for publicizing detailed criticisms of its products; the judge would be empowered to simply throw out such a lawsuit at first glance. A truly free market of goods and ideas is not an indiscriminate stew of anyone’s and everyone’s plans. Any such plans also would get tested, scrutinized, refined, and ultimately accepted or rejected by the other market participants. To the extent that one owns property that could sustain the perpetuation of a plan, one might counter even strongly held prevailing opinions – but only temporarily and only if one has other means of replenishing that property if the plan causes it to be depleted.

Moreover, in a truly free market, barriers to entry exist only on the basis of the constraints of the physical world, not on politics and special behind-the-scenes influence. Thus, competitors can always arise with a superior business model. Perhaps if you, the engineer, criticize the existing bridge sufficiently, another business enterprise will learn of its defects, purchase another piece of land, and construct a parallel, sturdier bridge that takes your suggestions into account. The misguided owners of the first bridge might eventually find themselves out of business because travelers will discover that safer, more convenient routes are available. And if the bridge ever does fail, a free-market system of civil liability will penalize those businesses who, through negligence, failed to take reasonable precautions to protect the health and safety of their customers. If the bridge ever becomes an imminent danger to travelers, it would be proper for public warnings to be issued and for the law-enforcement entity (be it a minarchist government or a private dispute-resolution agency) to order that traffic to the bridge be discontinued until the immediate danger is averted (perhaps through structural improvements at that time). A free market does not permit the reckless endangerment of unwitting, non-consenting others.

But always, in a hypothetical free-market society or in our own, a free-market-oriented engineer – or any professional, really – should have no compunction about expressing the truth about the soundness and validity of any party’s decisions or proposals, be they private or governmental. Just as a private party may well propose building a substandard bridge, so might a government today actually develop a decent bridge, especially if the incentives of a given political system are conducive to that particular outcome. The free-market engineer should not hesitate to praise the technical design of a good bridge, no matter what its source – because truth is true, and a bridge that could support two thousand cars at a time would, indeed, support those cars no matter who constructed it (provided the methods and materials used are identical in each case). A free-market perspective is a political and economic position which is compatible with completely rigorous, objective views of matters of science, technology, mathematics, history, metaphysics, epistemology, ethics, psychology, and any other conceivable discipline. Free-market advocates should respect people’s right to make choices, even when those choices are mistaken, but can maintain their own right to criticize those mistakes using as high a set of standards as they consider justified. If your values include striving for truth and justice, then those values are a part of the market as well, and you can improve market outcomes by working to instantiate those values in reality.

This essay may be freely reproduced using the Creative Commons Attribution Share-Alike International 4.0 License, which requires that credit be given to the author, G. Stolyarov II. Find out about Mr. Stolyarov here.

This Crazy 100-Year-Old Law Makes Almost Everything More Expensive – Article by George C. Leef

This Crazy 100-Year-Old Law Makes Almost Everything More Expensive – Article by George C. Leef

The New Renaissance HatGeorge C. Leef
******************************

It’s time to repeal the absurd, costly “Jones Act”

The 2016 presidential campaign so far has featured almost no discussion of downsizing the federal government. Americans would benefit enormously if we could get rid of costly old laws that interfere with freedom and prosperity, and future generations would benefit even more.

I keep hoping that someone will manage to put this question squarely to the candidates in either party: “What laws would you seek to repeal if you were the president?”

There are so many laws that ought to be repealed, including countless special interest statutes that benefit a tiny group while imposing costs on a vastly greater number of Americans. But if candidates need an idea of where to start, one such law is the Merchant Marine Act of 1920, also called the “Jones Act.”

The Act requires that all shipments between American ports to be done exclusively on American ships. As Daniel Pearson explains,

Its stated purpose was to maintain a strong U.S. merchant marine industry. Drafters of the legislation hoped that the merchant fleet would remain healthy and robust if all shipments from one U.S. port to another were required to be carried on U.S.-built and U.S.-flagged vessels.

The theory behind the law is musty, antiquated mercantilism — the notion that the nation will be stronger if we protect “our” industries against foreign competition.

Imagine how strong we would be if there had been a Jones Act for automobile transportation. Would Americans be better off today if the Detroit automakers had remained an oligopoly by keeping out all of those Hondas, BMWs, and Hyundais? Obviously not — yet this logic has handicapped US shipping for 96 years.

A recent op-ed in the Honolulu Star-Advertiser nicely explain the absurd consequences of this law. The writer just wants to buy a cabinet, but “although the cabinet was made in Taiwan, it could not be off-loaded in Hawaii, but rather had to be shipped to the West Coast, then loaded onto an American ship for the costly backward journey to Hawaii.” Tons of time, fuel, and expense wasted, all thanks to the Jones Act.

We get a more comprehensive view of its costs from a report by the Government Accountability Office (GAO) last September. The report, titled “International Food Assistance: Cargo Preference Increases Food Aid Shipping Costs,” shows the heavy cost of the law. The GAO, known for its non-partisan, straight-shooting approach, found that the Jones Act increased the cost of shipping food aid by 23 percent.

What does that mean? Between 2011 and 2014, the taxpayers had to fork over an extra $45 million to ship food for USAID. With Washington’s prodigious spending, we’ve gotten used to the idea that amounts under a billion are too small to bother with, but that is the wrong way to look at things. Even if we didn’t have a constantly increasing national debt, we ought to root out every needless federal expenditure.

Treading very delicately, the GAO states that, because the Jones Act “serves statutory policy goals,” Congress should merely tweak it so that aid agencies can find less costly shipping. But the federal government has no constitutional authority to be in the business of international aid, and carving out a special exemption for this would simply help the government avoid the consequences that it is inflicting on everyone else. Congress should simply repeal the protectionist law entirely.

The Jones Act also distorts our energy market and leads to higher prices than otherwise. Writing at The Federalist, trade attorney Scott Lincicome points out that, due to the law’s restrictions, only thirteen ships can legally move crude oil between US ports, and those ships are “booked solid.” As a result, shipping American crude from Texas to Philadelphia costs more than three times as much as it would cost to send it all the way to Canada on a foreign vessel.

One of the Act’s few congressional opponents is Arizona Senator John McCain, who pointed out in this testimony that Hawaiian cattlemen who want to sell livestock on the mainland “have actually resorted to flying the cattle on 747 jumbo jets to work around the restrictions of the Jones Act. Their only alternative is to ship the cattle to Canada because all livestock carriers in the world are foreign-owned.”

Hawaii is especially hard hit by the Jones Act, but other states and territories that depend heavily on water-borne shipping also suffer. Consider Puerto Rico: a 2012 study by the New York Fed found that it cost about $3,063 to ship a 20-foot container from an east coast US port to Puerto Rico, but shipping the same container to a foreign destination, such as Jamaica, would cost only about $1,687. Because it is an American territory, the poor island pays almost twice as much to import American products.

For nearly a century, we’ve paid more at the pump, more for goods, more in taxes, and even more to do charitable aid, all because of this ancient special interest law.

All that the Jones Act accomplishes is to guarantee a market for costly, unionized American shipping. It is similar in purpose to the Davis-Bacon Act, which guarantees a market for high-cost unionized construction (as I explain here).

Such special interest laws are never good for the country as a whole, but they are passed and maintained because their lobbyists are crafty, knowledgeable, and highly motivated, while the voting public is mostly ignorant.

It takes a spotlight and presidential leadership to get rid of them. Will any of this year’s crop take up the challenge?

George Leef is the former book review editor of The Freeman. He is director of research at the John W. Pope Center for Higher Education Policy.

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution 4.0 International License, which requires that credit be given to the author.

Venezuela Is Facing Runaway Financial Catastrophe – Article by Emily Skarbek

Venezuela Is Facing Runaway Financial Catastrophe – Article by Emily Skarbek

The New Renaissance HatEmily Skarbek
******************************

Debt, capital flight, food shortages, and hyperinflation take hold

Often, economists want to isolate questions of public debt and analyse these issues as if public choice considerations weren’t at play. Perhaps less studied are the ways in which debt practices can systematically exert pressure on formal political institutions.

But if you want to understand what is going on in Venezuela today, you can’t do so without looking at this political-economy nexus.

For regular people living in Venezuela, the situation is bleak. As the Economist reports, food queues start at 3 am, with the real possibility there won’t be anything for those at the end of the line. And the queues are growing longer and violent.

Real wages fell by 35% last year, 76% of Venezuelans are now poor, supplies of medicines have fallen to 1/5 of their normal level.

The government has admitted that in the 12 months to September 2015 the economy contracted by 7.1% and inflation was 141.5%. Even Nicolás Maduro, Chávez’s hapless heir and successor, called these numbers “catastrophic”.

The IMF thinks worse is in store: it reckons inflation will surge to 720% this year and that the economy will shrink by 8%, after contracting by 10% in 2015. The Central Bank is printing money to cover much of a fiscal deficit of around 20% of GDP.

In a case study of Venezuela from 1984 to 2013, Reinhart and Santos examine the relationship among domestic debt, financial repression, and external vulnerability. The paper begins with a narrative of the evolution of domestic and external debt in Venezuela over the period.

Despite soaring oil prices from 2006 to 2013, net consolidated external debt of Venezuela rose from US $26.9 to US $104.3 billion. The central government, however, only accounted for roughly a fifth of that increment.

The difference, US $60.9 billion (78%), owed to standard practices of the Bolivarian revolution, and was issued by state owned enterprises and the relatively new Fondo Comun China-Venezuela (FCCV). The FCCV is a special-purpose vehicle that allows Venezuela to withdraw from a rolling line of credit at the Chinese Development Bank in exchange for future shipments of oil.

Domestic debt in local currency also climbed, rising from 36.298 million bolivares (VEF) in 2006 to 420.502 million in 2013. The nominal increase of 1,060% (an average annual rate of 42%) was partially offset by an accumulated price increase of 528% (or an average annual rate of 30%), reducing the cumulative increase in real domestic debt to about 85% (or 9% per annum).

During much of this period, the combination of exchange controls and interest ceilings created a captive domestic audience for domestic government debt despite markedly negative real ex post interest rates. The significant losses imposed on domestic bondholders escalated over time, owing to accelerating inflation.

Unlike foreign currency-denominated debt, debt in domestic currency may be reduced through financial repression (i.e., taxes on bondholders and savers producing negative real interest rates). Reinhart and Santos find the financial repression “tax rate” is significantly higher in years of exchange controls and legislated interest rate ceilings. In Venezuela, the “haircut” on depositors and bondholders via negative ex post real interest has exceeded 30% per annum on several occasions.

Confiscating the wealth of those responsible for capital savings can partially ameliorate the existing stock of domestic debt in the short run, but at the expense of encouraging capital flight and undermining any semblance of trust in crucial economic institutions.

The paper documents that capital flight has been a chronic feature in the Venezuelan economy, “representing on average of 4.7% of GDP at the official exchange rate and 7.1% of GDP at the parallel market exchange rate, while siphoning away 17.2% of total exports.”

By all measures, exchange controls proved ineffective at reducing capital flight. In fact, “when measured as percent of GDP at the average parallel market, rate capital flight turned out to be significantly higher in years of controls (8.0% vs 5.2%).

Hayek would not be surprised. Over his professional career he argued disastrous monetary policy commits the state to taking measures that weaken the proper functioning of the market. In order to combat inflation, states will attempt to impose further controls that “would not only make the price mechanism wholly ineffective, but also make inevitable an ever-increasing central direction of all economic activity.”

In Venezuela, Chávez turned the would-be checks and balances of the state — the Supreme Court and the electoral authority — into extensions of executive power. He packed the court and they then threw out those legislators necessary for the opposition to get the two-thirds majority needed to change the constitution.

President Nicolás Maduro seems prepared to continue the repression and price controls, calling the owner of Venezuela’s largest privately-held company a thief and publicly blaming him for the country’s dire economic condition.

It is perhaps fitting that it was at a Mont Pèlerin Conference in Caracas where Hayek famously quipped:

We now have a tiger by the tail: how long can this inflation continue? If the tiger (of inflation) is freed he will eat us up; yet if he runs faster and faster while we desperately hold on, we are still finished!

I’m glad I won’t be here to see the final outcome…

Emily Skarbek is Lecturer in Political Economy at King’s College London and guest blogs on EconLog. Her website is EmilySkarbek.com. Follow her on Twitter @EmilySkarbek.​

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution 4.0 International License, which requires that credit be given to the author.

Oil Prices Too Low? – Article by Randal O’Toole

Oil Prices Too Low? – Article by Randal O’Toole

The New Renaissance HatRandal O’Toole
******************************

Remember peak oil? Remember when oil prices were $140 a barrel and Goldman Sachs predicted they would soon reach $200? Now, the latest news is that oil prices have gone up all the way to $34 a barrel. Last fall, Goldman Sachs predicted prices would fall to $20 a barrel, which other analysts argued was “no better than its prior predictions,” but in fact they came a lot closer to that than to $200.

Low oil prices generate huge economic benefits. Low prices mean increased mobility, which means increased economic productivity. The end result, says Bank of America analyst Francisco Blanch, is “one of the largest transfers of wealth in human history” as $3 trillion remain in consumers’ pockets rather than going to the oil companies. I wouldn’t call this a “wealth transfer” so much as a reduction in income inequality, but either way, it is a good thing.

Naturally, some people hate the idea of increased mobility from lower fuel prices. “Cheap gas raises fears of urban sprawl,” warns NPR. Since “urban sprawl” is a made-up problem, I’d have to rewrite this as, “Cheap gas raises hopes of urban sprawl.” The only real “fear” is on the part of city officials who want everyone to pay taxes to them so they can build stadiums, light-rail lines, and other useless urban monuments.

A more cogent argument is made by UC Berkeley sustainability professor Maximilian Auffhammer, who argues that “gas is too cheap” because current prices fail to cover all of the external costs of driving. He cites what he calls a “classic paper” that calculates the external costs of driving to be $2.28 per gallon. If that were true, then one approach would be to tax gasoline $2.28 a gallon and use the revenues to pay those external costs.

The only problem is that most of the so-called external costs aren’t external at all but are paid by highway users. The largest share of calculated costs, estimated at $1.05 a gallon, is the cost of congestion. This is really a cost of bad planning, not gasoline. Either way, the cost is almost entirely paid by people in traffic consuming that gasoline.

The next largest cost, at 63 cents a gallon, is the cost of accidents. Again, this is partly a cost of bad planning: remember how fatality rates dropped nearly 20 percent between 2007 and 2009, largely due to the reduction in congestion caused by the recession? This decline could have taken place years before if cities had been serious about relieving congestion rather than ignoring it. In any case, most of the cost of accidents, like the other costs of congestion, are largely internalized by the auto drivers through insurance.

The next-largest cost, pegged at 42 cents per gallon, is “local pollution.” While that is truly an external cost, it is also rapidly declining as shown in figure 1 of the paper. According to EPA data, total vehicle emissions of most pollutants have declined by more than 50 percent since the numbers used in this 2006 report. Thus, the 42 cents per gallon is more like 20 cents per gallon and falling fast.

At 12 cents a gallon, the next-largest cost is “oil dependency,” which the paper defines as exposing “the economy to energy price volatility and price manipulation” that “may compromise national security and foreign policy interests.” That problem, which was questionable in the first place, seems to have gone away thanks to the resurgence of oil production within the United States, which has made other oil producers, such as Saudi Arabia, more dependent on us than we are on them.

Finally, at a mere 6 cents per gallon, is the cost of greenhouse gas emissions. If you believe this is a cost, it will decline when measured as a cost per mile as cars get more fuel efficient under the current CAFE standards. But it should remain fixed as a cost per gallon as burning a gallon of gasoline will always produce a fixed amount of greenhouse gases.

In short, rather than $2.38 per gallon, the external cost of driving is closer to around 26 cents per gallon. Twenty cents of this cost is steadily declining as cars get cleaner and all of it is declining when measured per mile as cars get more fuel-efficient.

It’s worth noting that, though we are seeing an increase in driving due to low fuel prices, the amount of driving we do isn’t all that sensitive to fuel prices. Real gasoline prices doubled between 2000 and 2009, yet per capita driving continued to grow until the recession began. Prices have fallen by 50 percent in the last six months or so, yet the 3 or 4 percent increase in driving may be as much due to increased employment as to more affordable fuel.

This means that, though there may be some externalities from driving, raising gas taxes and creating government slush funds with the revenues is not the best way of dealing with those externalities. I’d feel differently if I felt any assurance that government would use those revenues to actually fix the externalities, but that seems unlikely. I actually like the idea of tradable permits best, but short of that the current system of ever-tightening pollution controls seems to be working well at little cost to consumers and without threatening the economic benefits of increased mobility.

Randal O’Toole is a Cato Institute Senior Fellow working on urban growth, public land, and transportation issues. O’Toole’s research on national forest management, culminating in his 1988 book, Reforming the Forest Service, has had a major influence on Forest Service policy and on-the-ground management. His analysis of urban land-use and transportation issues, brought together in his 2001 book, The Vanishing Automobile and Other Urban Myths, has influenced decisions in cities across the country. In his book The Best-Laid Plans, O’Toole calls for repealing federal, state, and local planning laws and proposes reforms that can help solve social and environmental problems without heavy-handed government regulation. O’Toole’s latest book is American Nightmare: How Government Undermines The Dream of Homeownership. O’Toole is the author of numerous Cato papers. He has also written for Regulation magazine as well as op-eds and articles for numerous other national journals and newspapers. O’Toole travels extensively and has spoken about free-market environmental issues in dozens of cities. An Oregon native, O’Toole was educated in forestry at Oregon State University and in economics at the University of Oregon.  

IJ and Small Business Owner Beat IRS on Civil Asset Forfeiture – Article by Adam Bates

IJ and Small Business Owner Beat IRS on Civil Asset Forfeiture – Article by Adam Bates

The New Renaissance HatAdam Bates
******************************

The court struck a blow for property rights

Last year I referred readers to the abuse of civil asset forfeiture laws by the IRS in its attempt to take more than $107,000 from North Carolina small business owner Lyndon McLellan without charging him with any crime.

The IRS cleaned out Mr. McLellan’s business account because it suspected him of “structuring,” an offense whereby a person avoids legally-mandated financial reporting requirements by keeping their deposits and withdrawals under $10,000.

Because there are many perfectly legitimate reasons a business owner may deposit less than $10,000 at a time (for instance, if their insurance policy only covers $10,000 cash on hand), and because civil asset forfeiture allows the government to seize cash and property without proving any wrongdoing, IRS structuring seizures are prone to abuse.

Tacitly recognizing the abuse allowed by the law, former Attorney General Eric Holder announced changes to the use of civil forfeiture in structuring offenses last year. The policy changes should have spared innocent business owners like Lyndon McLellan, but it seems some federal prosecutors never got the memo.

In fact, the Assistant U.S. Attorney in charge of the case responded to criticism by sending veiled threats to Lyndon McLellan and his lawyers at the Institute for Justice, warning them against publicizing the case lest it “ratchet up feelings” in the IRS offices.

The publicity worked. After significant public and political pressure, the IRS relented and returned the amount they had taken from Mr. McLellan’s bank account. As I noted last year, however, the IRS refused to reimburse Mr. McLellan for the costs of fighting the seizure or to pay interest on the money it had wrongfully seized.

But this week a federal judge ruled that the IRS must do more to make Mr. McLellan whole, and awarded him legal costs totalling more than $20,000.

The court held:

Certainly, the damage inflicted upon an innocent person or business is immense when, although it has done nothing wrong, its money and property are seized. Congress, acknowledging the harsh realities of civil forfeiture practice, sought to lessen the blow to innocent citizens who have had their property stripped from them by the Government. …

This court will not discard lightly the right of a citizen to seek the relief Congress has afforded.

Fortunately, thanks to the efforts of Mr. McLellan and the Institute for Justice, the good guys won this time. Ultimately, however, the only way to ensure that civil forfeiture abuses stop happening is to abolish civil forfeiture. If the government cannot prove beyond a reasonable doubt that a person engaged in criminal activity, it should not be able to punish them as if they’re guilty.

As long as Congress and state legislatures allow this practice to continue, more innocent Americans will end up fighting for their livelihoods like Lyndon McLellan had to.

Cross-posted from Cato.org.

Adam Bates is a policy analyst with Cato’s Project on Criminal Justice. His research interests include Constitutional law, the War on Drugs, the War on Terror, police militarization, and overcriminalization.

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution 4.0 International License, which requires that credit be given to the author.

Low-Skilled Workers Flee the Minimum Wage – Article by Corey Iacono

Low-Skilled Workers Flee the Minimum Wage – Article by Corey Iacono

The New Renaissance HatCorey Iacono
******************************

What happens when, in a country where workers are free to move, a region raises its minimum wage? Do those with the fewest skills seek out the regions with the highest wage floors?

New minimum wage research by economist Joan Monras of the Paris Institute of Political Studies (Sciences Po) attempts to answer that question. Monras theoretically shows that there should be a close relationship between the employment effects of raising the minimum wage and the migration of low-skilled workers.

When the demand for local low-skilled labor is relatively unresponsive (or inelastic) to wage changes, raising the minimum wage should lead to an influx of low-skilled workers from other states in search of better-paying jobs. On the other hand, if the demand for low-skilled labor is relatively responsive (or elastic), raising the minimum wage will lead low-skilled workers to flee to states where they will more easily find employment.

To test the model empirically, Monras examined data from all the changes in effective state minimum wages over the period 1985 to 2012. Looking at time frames of three years before and after each minimum wage increase, Monras found that

  1. As depicted in the graph below on the left, those who kept their jobs earned more under the minimum wage. No surprise there.
  2. As depicted in the graph below on the right, workers with the fewest skills were having an easier time finding full-time employment prior to the minimum wage increase. But this trend completely reversed as soon as the minimum wage was increased.
  3. A control group of high-skilled workers didn’t experience either of these effects. Those affected by the changing laws were the least skilled and the most vulnerable.

monrasp17a

These results show that the timing of minimum wage increases is not random.

Instead, policy makers tend to raise minimum wages when low-skilled workers’ real wages are declining and employment is rising. Many studies, misled by the assumption that the timing of minimum wage increases is not influenced by local labor demand, have interpreted the lack of falling low-skilled employment following a minimum wage increase as evidence that minimum wage increases have no effect on employment.

When Monras applied this same false assumption to his model, he got the same result. However, to observe the true effect of minimum wage increases on employment, he assumed a counterfactual scenario where, had the minimum wages not been raised, the trend in low-skilled employment growth would have continued as it was.

By making this comparison, Monras was able to estimate that wages increased considerably following a minimum wage hike, but employment also fell considerably. In fact, employment fell more than wages rose. For every 1 percent increase in wages, the share of a state’s population of low-skilled workers in full-time employment fell by 1.2 percent. (The same empirical approach showed that minimum wage increases had no effect on the wages or employment of a control group of high-skilled workers.)

Monras’s model predicts that if labor demand is sensitive to wage changes, low-skilled workers should leave states that increase their minimum wages — and that’s exactly what his empirical evidence shows.

According to Monras,

A 1 percent reduction in the share of employed low-skilled workers [following a minimum wage increase] reduces the share of low-skilled population by between .5 and .8 percent. It is worth emphasizing that this is a surprising and remarkable result: workers for whom the [minimum wage] policy was designed leave the states where the policy is implemented.

These new and important findings reinforce the view that minimum wage increases come at a cost to the employment rates of low-skilled workers.

They also pose a difficult question for minimum wage proponents: If minimum wage increases benefit low-skilled workers, why do these workers leave the states that raise their minimum wage?

Corey Iacono is a student at the University of Rhode Island majoring in pharmaceutical science and minoring in economics.

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution 4.0 International License, which requires that credit be given to the author.

Capitalism Promotes Equality – Article by Barry Brownstein

Capitalism Promotes Equality – Article by Barry Brownstein

The New Renaissance HatBarry Brownstein
******************************

Equality in Consumption Is Now the Norm

Highway traffic began to slow outside of Boston as we made our way to the airport. My wife was driving, so I took out my $100 Android phone and opened Google Maps. Google Traffic instantly showed me, in real time, the best route to avoid delays and estimated the number of minutes we’d save by altering our route. Thanks to Google, there was no threat of missing our flight.

It was not too long ago that we relied on traffic reporters in helicopters, and their advice was often useless by the time we heard their updates.

Have you wondered how Google Traffic does it? The answer is crowdsourcing. If you are among the two-thirds of American adults who own a smartphone, and if the GPS locator on your phone is enabled, you are generating real-time traffic information. Google Traffic measures how fast cars are moving compared to normal speeds and generates location-specific reports.

Rich or poor, most of the drivers on the highway that day had access to the same miraculous traffic report and the same opportunity to make better driving decisions. This is just one example of how the marketplace generates equality in consumption.

The cars we drive are another indicator of consumption equality. We were driving an inexpensive Subaru Outback. There are more expensive, comfortable, and bigger cars on the market, but the Insurance Institute for Highway Safety says that there are none safer than the Outback.

Would a rich individual, on this same drive to the airport, have any noticeable advantages over me? He or she could hire a driver and use the drive time for something more productive, but even that advantage will dwindle as driverless cars become the norm.

In his Wall Street Journal commentary “The Rise of Consumption Equality,” former hedge fund manager Andy Kessler writes:

Just about every product or service that makes our lives better requires a mass market or it’s not economic to bother offering. Those who invent and produce for the mass market get rich. And the more these innovators better the rest of our lives, the richer they get but the less they can differentiate themselves from the masses whose wants they serve.

“What does Google founder Larry Page have that you don’t have?” Kessler asks pointedly.

Page’s income is unimaginably larger than most of ours. But in terms of consumption, the differences are negligible — which is remarkable, given how much Page and Google have improved our lives.

All-time football great Tom Brady earns roughly $10 million a year. His diet made the news recently. Does Brady enjoy health advantages not available to Americans with a fraction of his income? Brady hires a cook. Our family doesn’t do that, but we eat much like Brady — organic vegetables, fruits, whole grains, beans, and fish make up the bulk of our diet. From May to October, a local organic farmer provides an abundance of vegetables that are picked fresh for us based on an order we place the day before. In the summertime, our produce may be fresher than Brady’s. Compared to any of us, what real dietary advantage does Tom Brady’s income afford him? It is his commitment to a healthy lifestyle, not his income, that makes the difference.

In 1900, Americans spent approximately 50 percent of their household income on food and clothing; today, we spend closer to 20 percent. Today, fresh produce from all over the world, not even available to a king a century ago, awaits common consumers when they enter the supermarket.

In 1900, only 25 percent of households had running water; fewer still had flush toilets. It would be decades before such wonders as electricity, automobiles, and indoor plumbing were ubiquitous. The faucets in the famed Hearst Castle in California may have been gold plated, but was the water any better than what the average household received? The water running in my home comes from an artesian well over 400 feet deep. More evidence of consumption equality: my water is every bit as good, if not better, than a billionaire’s in a big city penthouse.

Wealth is not a good predictor of a rich life. Psychology professor Sonja Lyubomirsky found that only 10 percent of the variance in Americans’ happiness is due to income and other circumstances. “Happiness more than anything,” she writes in her book The How of Happiness, ”is a state-of-mind, a way of perceiving and approaching ourselves and the world in which we reside.”

And what of the elements of emotional intelligence that make life richer? In the book Big Magic, best-selling author Elizabeth Gilbert observes:

If money were the only thing people needed to live rich creative lives, then the mega-rich would be the most imaginative, generative, and original thinkers among us, and they simply are not. The essential ingredients for creativity remain exactly the same for everybody: courage, enchantment, permission, persistence, trust — and those elements are universally accessible. Which does not mean that creative living is always easy; it merely means that creative living is always possible.

The same universally accessible elements are essential ingredients for entrepreneurship. Entrepreneurs persist, driven by their vision and by the equality of opportunity that capitalism affords. The entrepreneur’s choice to be persistent and courageous is the not-so-secret engine that drives success.

The essential consumption goods we couldn’t even imagine a hundred years ago are almost universally available in the United States today. The marketplace, aided by many creative, pioneering entrepreneurs and every person who strives to put in a good day’s work, is generating consumption equality.

Barry Brownstein is professor emeritus of economics and leadership at the University of Baltimore. He is the author of The Inner-Work of Leadership. He blogs at BarryBrownstein.com, Giving up Control, and America’s Highest Purpose.

This article was published by The Foundation for Economic Education and may be freely distributed, subject to a Creative Commons Attribution 4.0 International License, which requires that credit be given to the author.