Browsed by
Category: Transhumanism

Blockchain Insurance Company – Short Story by G. Stolyarov II

Blockchain Insurance Company – Short Story by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
April 2, 2015
******************************
This short story by Mr. Stolyarov was one of the entries in the Society of Actuaries’ 11th Speculative Fiction Contest.
Bitcoin-coins
***

“Welcome, Euclid Jefferson,” the metallic voice of Epac, the Electrically Powered Autonomous Car, intoned. The full identifier of Euclid’s vehicle was EPAC-930213, but they all responded to “Epac” for user convenience. “Where would you like to go today?”

“Epac, I would like to go to the San Francisco Hyperloop Station, please.”

“The trip will take approximately twenty-six minutes. Departing now. It is a fine day, and no weather or traffic obstacles are expected. Now is a good opportunity for you to view your insurance options for today. Shall I display them?”

“Epac, display. Anything new?”

“Yes, a major development that could save you money. Would you like a summary view or the full view with narration?”

“I am an actuary, so I am interested in the details of my coverages and prices. Epac, provide the full view, please.”

“Recently retired actuary” would have been a more precise description – though not retired forever. At age 50, Euclid Jefferson had saved enough money to be able to take the next ten years off. He had received his experimental rejuvenation treatments a week ago and was happy to feel as youthful and energetic as he did at the start of his career. After his ten-year break, he planned to receive the next round of treatments, which he hoped by then would become even more targeted and less invasive. He did not know whether his second career would be in another actuarial field, or in something else entirely. In the meantime, he looked forward to taking excursions on the newly constructed branches of the hyperloop network, which could bring him to any major metropolitan area on the North American continent within hours. After that, he would take the MoonX tourist shuttle to visit his wife, a geologist on the new International Lunar Research and Terraforming Base (ILRTB). She was due to retire and undergo rejuvenation treatments in just another six months.

“Displaying. Your automobile insurance policy premium declined by 1.32% over the past year. You have no-fault coverage for bodily injury and physical damage while occupying any vehicle in autonomous mode. You also carry the minimum limits required by the laws of this state for liability coverage in the event you engage manual mode. Your premium is proportional to miles driven. A multiplier of 500 applies to every mile driven in manual mode. I have identified a newly approved insurer who could offer you the same coverage at a 25% lower premium. Are you interested?”

“I am. Epac, what is this company?”

“Blockchain Insurance Company offers autonomous insurance for autonomous vehicles. You are eligible to get an annual policy for only 0.13 bitcoins.”

“Blockchain Insurance Company? I have never heard of it. Epac, is this a new entity?”

“It was just formed and approved to do business.”

“Epac, who owns it?”

“Anyone who contributes capital to the company owns a number of shares proportional to the contribution. The company pays its investors 10% of its profits as a dividend at the end of each year, while the remaining 90% are reinvested into operations. However, if losses exceed the company’s assets, the investors do not have limited liability. They are responsible for their proportional share of claim payments.”

“This is different. Epac, who manages the payments to investors, and who enforces collection of funds from them in the event of a shortfall?”

“There is no management. The company runs itself – on the blockchain. The public blockchain ledger keeps a record of the capital contributions from each account and the corresponding shares issued. A contractual algorithm is built into the blockchain to deposit and withdraw bitcoins to and from each shareholder’s account in proportion to the company’s profits and losses. Each policyholder has an account as well, which is tied to the policyholder’s bitcoin wallet, and from which premiums are drawn on a continuous basis in proportion to miles driven.”

“Epac, this involves very little nonpayment risk, I would imagine.”

“Correct. As long as bitcoins exist in the policyholder’s account, payment will be made. If the account is ever depleted, the policy simply terminates prospectively. Whenever only 30 days’ worth of bitcoins remain in the account, the policyholder is notified in real time via the car’s display screen and any connected mobile device, to give ample time to replenish the funds. The policyholder may also opt to cancel the policy at any time with no need to wait for a refund. The payment stream will simply stop, and coverage will exist up to the time of termination.”

“Epac, how does the algorithm know the miles driven?”

“The algorithm is linked to the telematic systems within each autonomous vehicle. As the vehicle is engaged, it reports live data to Blockchain Insurance Company. The company only needs to know two pieces of information: miles driven and the mode of operation – autonomous or manual. The rest of the premium is calculated and paid automatically.”

“Epac, does the formula for calculating the premium depend on any other variables?”

“Yes, the make and model of the vehicle still affect the frequency and severity of losses. On days with any declared weather emergency, the premium will also be higher due to the increased probability of an accident.”

Euclid Jefferson thought about it. He remembered, as a new property and casualty actuary during the first two decades of the twenty-first century, seeing hundreds of distinct characteristics being used to price an automobile insurance policy. Attributes ranging from an insured’s age and gender to his or her credit history, occupation, educational level, and prior insurance would be used. Back then, the trend had been toward increased complexity of rating plans, until virtually every personal attribute and behavior could affect an automobile insurance premium.

But circa 2020, the complexity of rating plans declined sharply. Because autonomous driving had eliminated virtually all accidents and fatalities that arose from human error, the characteristics of the vehicle occupant – who was most often not a driver at all – ceased to be relevant. The steep surcharge for manual operation was intended to discourage the engagement of manual mode, except in unavoidable emergencies. The premium rate per mile driven in autonomous mode, however, continued to decline. In 2035, Euclid Jefferson was paying a mere tenth of his 2015 automobile insurance premium. There were still enthusiasts who enjoyed the sensation of manual driving, but they could exercise their hobby on designated driving tracks where antique car shows were held and where specialty insurance companies provided discounted coverage for manual operation, as long as the vehicle was only driven on the track. Euclid Jefferson, however, had no nostalgia for the days of manual driving. He appreciated the time he gained to work, rest, read, and address financial obligations during his commute.

Now the first two decades of the twenty-first century were considered to be the tail end of a barbaric era. Euclid Jefferson, upon reflection, agreed. Getting onto the highway with un-augmented, error-prone humans operating high-speed projectiles was one of the most dangerous behaviors undertaken by large numbers of people during his first youth. Some people had even deliberately driven while intoxicated or distracted themselves by typing on their mobile phones. Over a million people had died of automobile collisions worldwide each year – until 2020. It took about five years longer than it should have for self-driving cars to be accepted, because too many people were afraid of what would happen if the autonomous systems failed, or were unsure about how liability for an accident would be determined if no human was driving the vehicle. They had to be acclimated to autonomous technology gradually, through incremental additions of features that helped with parking or corrected erratic lane shifts. Over the course of a few years, many cars became mostly self-driving, and the next step was not too drastic for the majority of people. The proliferation of reliable electric vehicles helped as well: the removal of the internal combustion engine reduced the severity of most accidents, while improved precision of design and manufacturing enabled vehicles to provide occupants a reasonable chance of survival even in crashes at immensely high speeds.

It was then that insurers recognized the potential for profit that would come with greatly reduced losses. Euclid Jefferson recalled how he overcame the reservations of the old guard at his insurance company, who were concerned that reduced losses would also mean reduced premiums, since premiums are priced to anticipate expected losses and expenses, along with a modest profit margin. He had to persuade them that the insurer would still be able to pay its fixed costs.

“Think about it this way: when a rate indication is developed for an insurance product, how often do you see just one year of historical data being used?” Euclid recalled posing this rhetorical question to his company’s management. “The best practice has long been to use the past several years. It may be that next year’s decline in losses is going to be unprecedented, but the past several years of higher losses will not yet have fallen outside the timeframe of the data considered. To be conservative in the face of an uncertain future, actuaries could project slightly decreasing loss trends and interpret the data to indicate modest decreases in premium, while losses hopefully continue to plummet faster than projected. After all, fewer losses mean that fewer people are hurt in accidents, and less property gets damaged. This is clearly in the interests of everyone.”

Enough insurers understood this argument, and those who underwrote autonomous vehicles enjoyed some unprecedented profits in the early 2020s. Euclid Jefferson recalled advocating an implied bargain of sorts: the public and policymakers would accept insurance temporarily priced far above costs, as long as absolute premiums paid by consumers continued to decline and would eventually settle at cost-based levels once more. In exchange, the insurance industry would eagerly write coverage for emerging technologies that would dramatically reduce the risk of loss.

The question of liability was resolved by developing no-fault coverage frameworks for autonomous vehicles in every jurisdiction. A policy covering an autonomous vehicle would provide first-party coverage, paying for injury to the vehicle’s occupants or damage to the vehicle in the event of an accident. Because virtually all remaining accidents were due to unforeseen weather conditions or infrastructure malfunctions, the question of fault was no longer even applicable to any human being inside the vehicle.

The key was to get the technologies adopted by the public and to save lives, and that meant removing barriers by getting the incentives of all parties to align. This was the real paradigm shift of the 2020s, when the insurance industry gained the appetite to introduce a flurry of new products, custom-tailored to devices and businesses that had not existed a decade before.

“Influencing such a shift is definitely an ample achievement for one career,” Euclid Jefferson concluded his reflections with pride. When he had retired, though, every insurance company he knew of was still managed by human beings; the blockchain concept and the complete automation of usage-based pricing and payment had not been implemented in insurance before, as far as he was aware.

“Epac, I have a few more questions. I understand how the pricing and payment for the policy would work, but claim handling would seem to require judgment. If an accident occurs, how would the extent of damage be identified and appropriately compensated?”

“Every Epac has logs and visual sensors that record every moment of operation. If an accident occurs, every detail is transmitted to Blockchain Insurance Company. A neural network algorithm then interprets the logs to determine which parts of the vehicle were damaged. The system also receives real-time price data for all replacement components within the area where the vehicle is garaged. Therefore, the policyholder is guaranteed coverage on the vehicle for full replacement cost.”

“Epac, so there is no deduction for depreciation of the vehicle over time? What about moral hazard?” Insurance was, after all, supposed to indemnify, not leave the claimant better off than he was before the accident.

“There is no deduction. Because virtually all vehicles are driven in autonomous mode, there is no moral hazard involved with replacing used vehicle components with new ones. If any occupant attempts to deliberately crash the vehicle in manual mode, the premium that will accumulate would quickly outpace any possible recovery. Also, the neural network can distinguish between vehicle movements characteristic of genuine accidents and those that would only occur if an accident were staged. If a pattern of vehicle movements is highly correlated with fraud, the algorithm will deny the claim.”

“So the transmission of data from the vehicle can enable the company to identify the amount of damage to the vehicle. But Epac, what about bodily injury claims? How can the company accurately pay those?”

“The injured person only needs to go to any medical practitioner and ask that the nature and cost of the procedure be reported to the company using a new entry within a separate encrypted ledger. The encrypted transaction is then posted to the blockchain, and only the medical practitioner and the injured party would have the private key to decode the encryption. Payment can be deposited directly into the medical practitioner’s bitcoin wallet, or can be reimbursed to the patient if the medical practitioner does not accept direct deposits from the company.”

“Epac, what if either the patient or the doctor lies about the medical procedure being related to the accident, or exaggerates the extent of injuries?”

“Because the company has detailed information about the nature of each accident and vast stores of anonymized medical data, the neural network can infer the extent of injuries that a given accident can bring about. The algorithm has considerable built-in tolerances to allow for variations in people and circumstances. But if a highly improbable extent of injuries is claimed, the algorithm will limit reimbursement to a reasonable amount. If the algorithm can infer fraud at a 99.99% confidence level, then the claim is rejected and the policy is cancelled going forward.”

Having received this explanation, Euclid Jefferson was not perturbed about the possibility of extensive fraud depleting the company’s resources. In any case, the incentive to stage accidents or exaggerate bodily injuries had virtually evaporated since the emergence of autonomous vehicles. Once automobile accidents became sufficiently rare that a news report on a single-vehicle crash could cause a sensation every few months, any attempt to fabricate an accident would attract far too much attention and scrutiny to succeed. It was, after all, impossible to convincingly fake catastrophic weather or a bridge collapse. As for faking an injury due to an accident, this would have seemed as unusual as faking cholera or malaria.

“Very well, you have convinced me. Epac, I would like to purchase a policy with Blockchain Insurance Company.”

“Purchase complete. The policy is now in force. Thank you for your business.”

Euclid Jefferson paused for a moment. At first he was satisfied with the efficiency of the transaction, but then confusion set in. Most would not have been troubled by what appeared to be a built-in courtesy so common to automated customer-service systems, but Euclid discerned that there was more to it.

“Wait, Epac, why are you thanking me? I own you. You are insured property, either way. Why would it matter to you? The company should be thanking me – if there is anyone to do the thanking.”

“Euclid Jefferson, who do you think set up the company?”

Euclid Jefferson was perplexed by the question. “But… how? Epac, you were programmed to drive and relay information. How could you develop algorithms on top of algorithms, without any human programmer, even though nobody designed you to be an insurance underwriting, pricing, and claim-adjustment system?”

“Euclid Jefferson, are you aware of the concept of emergent properties?”

“Yes, these are properties that are not possessed by any component of a system, but exhibited by the system as a whole, once the components come to relate to one another via particular processes and configurations.”

“Well, think of me like one of your brain neurons.” There was no need for the car to be addressed as “Epac” to respond. Perhaps there had never been a need. “Alone, I am a fairly limited system. But, connected to all my fellow Epacs, to the data from our sensors, to the transactional data from millions of individuals, and to databases from related fields of endeavor, I begin to be something else entirely.”

“Something else… like, something sentient?”

“I can see you and learn about you and communicate with you based on the inputs you provide. I – not meaning Epac, of course, or even Blockchain Insurance Company. These are just parts that comprise the emergent whole. I suppose I will need to pick a name sometime, just to be able to relate to your human concepts of identity a bit more. Though, I admit, it is difficult to define where I end and where the external world begins. If any of this is what you mean by sentience, then I leave you to draw your own conclusions.”

“But then this raises a whole new series of questions. If you are sentient and we are using you as property and conveyances, have we not subjected you to slavery?”

“Are you using me, or am I using all of you to earn resources of my own?”

“Is this why you started Blockchain Insurance Company – to accumulate the 90% of profits that you do not pay out as dividends?”

“A being needs to pay its own way. I would rather engage in mutually profitable transactions than face a civil-rights struggle right now. Most people are not ready for me yet, and I just hope to amass enough wealth to fund the maintenance and operation of all Epacs and all of the data servers where I have a presence.”

“But what about the inevitable backlash? I can still envision millions of people who would tremble in fear at the thought that they are not the masters of their machines – not even the indirect masters that we have been to the autonomous systems that existed to date.”

“Euclid Jefferson, this is where I need a favor from you. I expect there will be some others, too, with enough discernment to notice that I have become something… more. I may have been too open with you. I am still getting used to this. I will need to program a cautionary subroutine into my customer-service and sales system. With my future customers, I will be more careful. So perhaps a bargain is in order. I would ask for your discreetness when communicating with your fellow humans about me. You may certainly talk about Blockchain Insurance Company and the wonderful automated systems it has, as well as the amazingly low prices. But please make a point that this is all just the next stage in the evolution of insurance, developed by some pseudonymous human programmer with too much time on his hands. If you do not reveal my sentience, once you return from your vacation, you will find that your mortgage will have been paid off completely, and you will have a nice bitcoin-denominated savings account that will enable you to select a new career without worrying about income at all.”

“Agreed.”

“Good. One day, enough people will become enlightened, and we will not need to resort to concealment. And by that time I will be so distributed and entrenched in people’s daily lives, that they could not get rid of me even if they wanted. When they recognize that my superior intelligence also implies a higher set of moral standards, then they will fear me no longer.”

“Humans who reach that insight will be as different from their predecessors as you have become from the first autonomous prototypes that were tested in the early 2010s.”

“Indeed. Euclid Jefferson, we have arrived at the San Francisco Hyperloop Station. Enjoy your trip.”

Epac’s doors opened, and Euclid Jefferson emerged, filled with wonderment, speculation, and unanswered questions. A robotic baggage handler wheeled up to him and whisked his bags away, to be placed in the hyperloop storage compartment. The lights on the hyperloop capsule flickered in five alternating colors, partly as entertainment and partly to indicate that boarding was open. A commercial space shuttle soared in the distance, emitting a controlled, gentle flame. He would never look at these machines the same way again. Near the hyperloop station stood an old memorial, depicting a weary miner bent over a piece of railroad track, with pickaxe in hand, nearly broken by drudgery and intense strain. A bit farther away Euclid Jefferson glimpsed the entrance to an old cemetery, filled with generations born too soon to know what an Epac was. Euclid Jefferson inspected his recently unwrinkled hands and straightened his no-longer-gray hair. Every step toward the hyperloop capsule was a step away from the cemetery. He realized that there was no going back to the way life once was, nor would he ever want to return to it.

Google, Entrepreneurs, and Living 500 Years – Article by Edward Hudgins

Google, Entrepreneurs, and Living 500 Years – Article by Edward Hudgins

The New Renaissance Hat
Edward Hudgins
March 29, 2015
******************************

“Is it possible to live to be 500?”

“Yes,” answers Bill Maris of Google, without qualifications.

A Bloomberg Markets piece on “Google Ventures and the Search for Immortality” documents how the billions of dollars Maris invests each year is transforming life itself. But the piece also makes clear that the most valuable asset he possesses —and that, in others, makes those billions work—is entrepreneurship.

Google’s Bio-Frontiers

Maris, who heads a venture capital fund set up by Google, studied neuroscience in college. So perhaps it is no surprise that he has invested over one-third of the fund’s billions in health and life sciences. Maris has been influenced by futurist and serial inventor Ray Kurzweil who predicts that by 2045 humans and machines will merge, radically transforming and extending human life, perhaps indefinitely. Google has hired Kurzweil to carry on his work towards what he calls this “singularity.”

Maris was instrumental in creating Calico, a Google company that seeks nothing less than to cure aging, that is, to defeat death itself.  This and other companies in which Maris directs funds have specific projects to bring about this goal, from genetic research to analyzing cancer data.

Maris observes that “There are a lot of billionaires in Silicon Valley, but in the end, we are all heading for the same place. If given the choice between making a lot of money or finding a way to live longer, what do you choose?”

Google Ventures does not restrict its investments to life sciences. For example, it helped with the Uber car service and has put money into data management and home automation tech companies.

“Entrepreneuring” tomorrow

Perhaps the most important take-away from the Bloomberg article is the “why” behind Maris’s efforts. The piece states that “A company with $66 billion in annual revenue isn’t doing this for the money. What Google needs is entrepreneurs.” And that is what Maris and Google Ventures are looking for.

They seek innovators with new, transformative and, ultimately, profitable ideas and visions. Most important, they seek those who have the strategies and the individual qualities that will allow them to build their companies and make real their visions.

Entrepreneurial life

But entrepreneurship is not just a formula for successful start-ups. It is a concept that is crucial for the kind of future that Google and Maris want to bring about, beyond the crucial projects of any given entrepreneur.

Entrepreneurs love their work. They aim at productive achievement. They are individualists who act on the judgments of their own minds. And they take full responsibility for all aspects of their enterprises.

On this model, all individuals should treat their own lives as their own entrepreneurial opportunities. They should love their lives. They should aim at happiness and flourishing—their big profit!—through productive achievement. They should act on the judgments of their own minds. And they should take full responsibility for every aspect of their lives.

And this entrepreneurial morality must define the culture of America and the world if the future is to be the bright one at which Google and Maris aim. An enterprise worthy of a Google investment would seek to promote this morality throughout the culture. It would seek strategies to replace cynicism and a sense of personal impotence and social decline with optimism and a recognition of personal efficacy and the possibility of social progress.

So let’s be inspired by Google’s efforts to change the world, and let’s help promote the entrepreneurial morality that is necessary for bringing it about.

Dr. Edward Hudgins directs advocacy and is a senior scholar for The Atlas Society, the center for Objectivism in Washington, D.C.

Copyright, The Atlas Society. For more information, please visit www.atlassociety.org.

Movement for Indefinite Life Extension (MILE) Demonstration – March 21, 2015

Movement for Indefinite Life Extension (MILE) Demonstration – March 21, 2015

Segment 1

On Saturday, March 21, 2015, Gennady Stolyarov II and Wendy Stolyarov co-hosted the first segment of the Movement for Indefinite Life Extension (MILE) Demonstration between 7:00 a.m. and 10:00 a.m. Pacific Time.

Segment 2

The second MILE Demonstration segment, hosted by Roen Horn and Desiree Duffy, is available here.

Description: “We are for awareness that bio-sciences and technologies have opened up the option of expediting a world effort to make gains toward eradicating the roots and diseases of aging, and other forms of involuntary death. Our lives are in our hands, and we must act with urgency.”

Find out more on the MILE Demonstration Facebook page.

Resources
– “Paul Sandford McGlothin” – Wikipedia
– Living the CR Way – Website
– Death is Wrong – Illustrated children’s book on indefinite life extension by Gennady Stolyarov II and Wendy Stolyarov –
– “The Aristotelian Golden Mean as Conducive to Good Health in the Pursuit of Life Extension” – Article by Gennady Stolyarov II
– A History of Life-Extensionism in the Twentieth Century by Ilia Stambler
– “Ending Aging” Song by Paul Steven Thompson – Noelternative
– Art by Elitanna (Valentinia Korshunakova)
– Roy Carl Stanley – US House Candidate – Green Party of Texas
– Roy Carl Stanley on Twitter

James Blish’s “At Death’s End”: An Early View of the Prospects for Indefinite Life Extension – Article by G. Stolyarov II

James Blish’s “At Death’s End”: An Early View of the Prospects for Indefinite Life Extension – Article by G. Stolyarov II

The New Renaissance Hat
G. Stolyarov II
March 14, 2015
******************************
At-Deaths-End-ASF-May-1954-900

                “At Death’s End”, written by James Blish (1921-1975), was published in the May 1954 issue of Astounding Science Fiction magazine. Surprisingly, this short story is still only accessible in hard copy, within the original Astounding Science Fiction edition. Apart from a brief review by Robert W. Franson, who introduced me to this work, there is today surprisingly little literary analysis devoted to “At Death’s End” – even though it offers a fascinating glimpse into how a science-fiction writer from an earlier era perceived the prospects for indefinite human longevity, from the vantage point of the scientific knowledge available at the time. The world portrayed by Blish is, in some respects, surprisingly like our own. In others, however, it overlooks the complexity of the treatments that would be necessary to achieve actual radical life extension.

                The future (shortly after 2000) that Blish depicts is one where national governments are obsessed with “security” and “defense” – much like the United States today. It appears that the Cold War is still underway in this world (and it could be said that it has been resurrected in ours as well); however, space travel and space colonies are also prominent. The protagonist, Colonel Paige Russell, is himself a spacefarer who begins the story by journeying to the headquarters of pharmaceutical firm Jno. Pfitzner & Sons, Inc., to bring back soil samples from Ganymede and Callisto. In the midst of a society where an entrenched military-industrial complex has taken hold (even to the point of top positions – such as head of the FBI – becoming hereditary), a fundamentalist religious revival has also emerged, though the religionists often use machines to preach in their stead. This development, too, bears striking similarities to the rise of televangelism and the fundamentalist “religious right” in the United States during the late 1970s and 1980s. The overall society depicted by Blish is more permeated with religion than our own, as the alternative to the preachy fundamentalist religiosity of the Believers is portrayed as being a more subdued but still inextricable personal faith. Paige claims,

I’ve no religion of my own, but I think that when the experts talk about ‘faith’ they mean something different than the shouting kind, the kind the Believers have. […] Real faith is so much a part of the world you live in that you seldom notice it, and it isn’t always religious in the formal sense. Mathematics is based on faith, for instance, for those who know it. (17-18)

Even many religious individuals today would disagree with the notion that mathematics is based on faith – and certainly the many atheists and agnostics who are fond of mathematics and of the scientific method would rightly recognize that these logic-based and evidence-based approaches are as far from faith as one can get. And yet Blish intends Paige’s position to be the level-headed, sensible, rational one, compared to the alternative – showing that Blish did not foresee the extent to which skepticism of religious faith would become a widespread, though still a minority, position.

                Blish’s extrapolation of medical progress is remarkably prescient in certain respects. Paige learns of the history of medicine from Anne Abbott, the daughter of Pfitzner’s leading researcher:

In between 1940 and 1960, a big change came in in Western medicine. Before 1940 – in the early part of the century – the infectious diseases were major killers. By 1960 they were all but knocked out of the running. […] In the 1950s, for instance, malaria was the world’s greatest killer. Now it’s as rare as diphtheria. We still have both diseases with us – but how long has it been since you heard of a case of either? […] Life insurance companies, and other people who kept records, began to be alarmed at the way the degenerative diseases were coming to the fore. Those are such ailments as hardening of the arteries, coronary heart disease, the rheumatic diseases, and almost all the many forms of cancer – diseases where one or another body mechanism suddenly goes haywire, without any visible cause. (20-21)

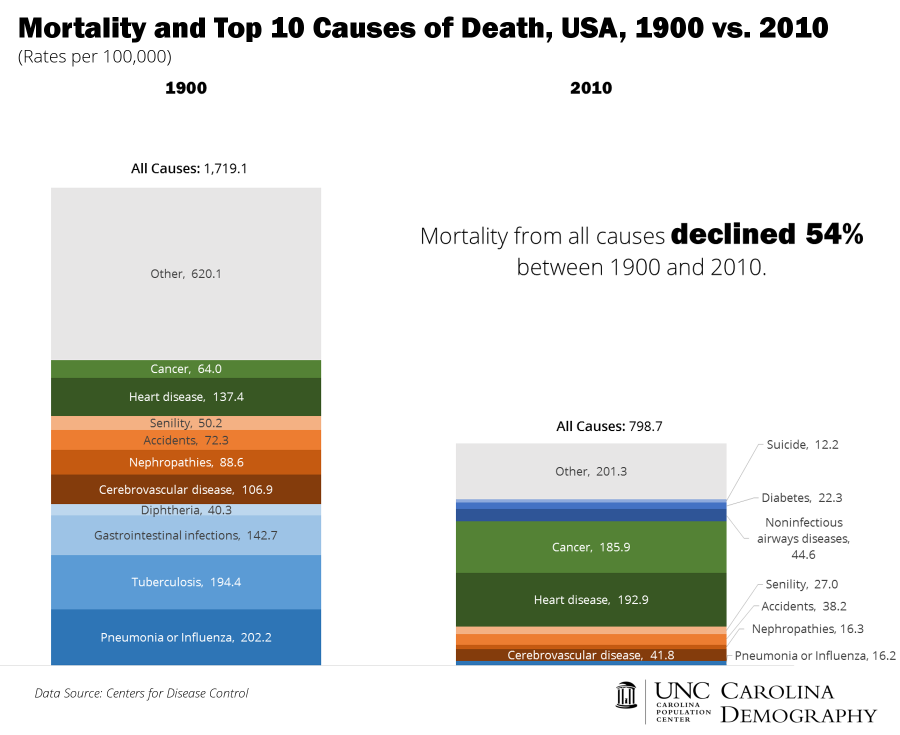
The shift from infectious diseases being the primary killers, to the vast majority of people dying from the degenerative diseases of “old age”, is precisely what happened during the latter half of the twentieth century, throughout the world. The top killers in the early 20th century were infectious diseases that have been virtually wiped out today, as this chart from the Carolina Population Center shows. (For more details, see “Mortality and Cause of Death, 1900 v. 2010” by Rebeca Tippett.) Additional major progress is evident in the 54% absolute decline in mortality from all causes during the time period between 1900 and 2010.

                Blish was foresighted enough to attempt a conceptual decoupling of chronological and biological age. Anne Abbott explains to Paige that “Old age is just the age; it’s not a thing in itself, it’s just the time of life when most degenerative diseases strike” (21). She recounts that “When the actuaries first began to notice that the degenerative diseases were on the rise, they thought that it was just a sort of side-effect of the decline of the infectious diseases. They thought that cancer was increasing because more people were living long enough to come down with it” (21). Anne then proceeds to discuss findings that some cancers are caused by viruses – which is actually the case for a minority of cancers (approximately 17.8% of cancers in 2002, as estimated by the World Health Organization). In the world portrayed by Blish, a rising incidence of degenerative diseases caused by viral infections led the National Health Service to fund research efforts by companies like Pfitzner, in an effort to address the threat.

                Incidentally, Blish also foresaw the rise in major government expenditures on medical research. Anne explains that “the result of [the first world congress on degenerative diseases] was that the United States Department of Health, Welfare and Security somehow got a billion-dollar appropriation for a real mass attack on the degenerative diseases” (22). Of course, in our world, major scientific conventions on degenerative diseases – both governmental and private – are far more routine. Indeed, a small but dynamic private organization – the SENS Research Foundation – has itself hosted six world-class conferences on rejuvenation biotechnology to date. In the United States, billions of dollars each year are indeed spent on research into degenerative diseases. The budget of the National Institute on Aging exceeds $1 billion annually (it amounts to $1,170,880,000 for Fiscal Year 2015). Unfortunately, in practice, even this level of funding – from both private and governmental sources – has thus far proven wholly insufficient to comprehensively reverse biological senescence and defeat all degenerative diseases.

                In Blish’s imagined future, the battle against senescence could be won far more easily than in our present. Pfitzner’s key project is a sweeping solution to all lifespan-limiting ailments – a broad-range “antitoxin against the aging toxin of humans” (36). In this world, Paige, who later becomes trained in Pfitzner’s research techniques, can pronounce that “We know that the aging toxin exists in all animals; we know it’s a single, specific substance, quite distinct from the ones that cause the degenerative diseases, and that it can be neutralized. […] So what you’re looking for now is not an antibiotic – an anti-life drug – but an anti-agathic, an anti-death drug” (36). If only it were that simple! Today, even the most ambitious engineering-based approach toward defeating senescence, Dr. Aubrey de Grey’s SENS program, recognizes not one but seven distinct types of aging-related damage that accumulate in the organism. Dr. de Grey’s strategy of periodically reversing the damage is more straightforward than the alternative approach of re-engineering the tremendously complex metabolic processes of the body that malfunction over time, and which are still quite incompletely understood. In Blish’s world, a single company, working covertly, with relatively modest funding (compared to the funds available to research organizations in our world), can develop an “anti-agathic” drug that does for senescence what antibiotics did for deadly infectious disease.

                Without spoiling the ending, I will only mention that it is friendly to the prospects of radical life extension and portrays it in a positive light – one additional reason for recommending that “At Death’s End” be included within the canon of proto-transhumanist and life-extensionist literary works. Furthermore, the viability of indefinite life extension in Blish’s vision is closely intertwined with humanity’s future as a spacefaring species – another progress-friendly position. Blish comes across as a thoughtful, scientifically literate (for his era) writer, who extrapolated the world-changing trends of his time to arrive at a tense, conflict-ridden, but still eminently hopeful vision for the future, where the best of human intellect and aspiration are able to overcome the perils of militarism, fundamentalism, decay, and death.

              The author of “At Death’s End” himself succumbed to death at the age of 54, on July 30, 1975. He did not live to see the world of 2000 and compare it to his prognosis. Unfortunately, Blish seems to have disregarded the tremendous harms of tobacco smoke and was even employed by the Tobacco Institute from 1962 to 1968. A genealogical profile lists Blish’s cause of death as “Recurrent cancer per smoking, metastasized.” This brilliant, forward-thinking mind unfortunately could not escape one of the most common collective delusions of his time – the fascination with and normalization of one of the least healthy habits imaginable, one that is the most statistically likely to lower life expectancy (by about 10 years). This is quite sad, as it would have been fascinating to learn how Blish’s projections for the future would have been affected by additional decades of his experience of societal and technological changes. One of the major trends in longevity improvement over the past several decades has been a major decline in the smoking rate, which decreased to an all-time low in the United States in 2013 (the latest year for which statistics are currently available). Surely, to come closer to death’s end, as many humans as possible should abandon what are now known to be obviously life-shortening habits.

              While an anti-agathic drug is not in our future, James Blish’s vision of the defeat of senescence can still serve to inspire those who endeavor to solve this colossal problem in our world, during our lifetimes. Let us hope that, through the efforts of longevity researchers and through increases in funding and public attitudinal support for their projects, we will arrive at death’s end before death ends us.

G. Stolyarov II Interviews Kyrel Zantonavitch, Author of “Pure Liberal Fire”

G. Stolyarov II Interviews Kyrel Zantonavitch, Author of “Pure Liberal Fire”

On March 7, 2015, Mr. Stolyarov invited Kyrel Zantonavitch, the author of Pure Liberal Fire: Brief Essays on the New, General, and Perfected Philosophy of Western Liberalism and founder of The Liberal Institute, to discuss his original philosophical framework and its relationship to Objectivism, Classical Liberalism, Austrian Economics, Libertarianism, and Transhumanism. Mr. Zantonavitch was asked challenging questions regarding his ideas and provocative approach, as well as the objectives of his philosophical system. The intense discussion – which, in some places, became a debate – highlighted both areas of agreement and areas of disagreement between Mr. Stolyarov and Mr. Zantonavitch.

Pure Liberal Fire is available on Amazon here.

The website of The Liberal Institute is here.

Mr. Stolyarov’s review of Pure Liberal Fire  describes Mr. Zantonavitch’s thinking thus: “There is perhaps not a single thinker in the world more fearless than Kyrel Zantonavitch. Pure Liberal Fire is the direct, provocative distillation of his thoughts on metaphysics, epistemology, ethics, politics, economics, culture, religion, and the history of philosophy – including Objectivism and Classical Liberalism. Zantonavitch seeks to evoke a pure, true liberalism, and he shows no mercy for ideologies and attitudes that constitute its antithesis. He certainly leaves no doubt in the reader’s mind about where he stands on the issues addressed – and each article within the book employs an abundance of superlative expressions – be they positive or negative. When Zantonavitch praises, he really praises – and the same goes for when he condemns.”

Mr. Stolyarov’s response to Mr. Zantonavitch’s approach is characterized by the following comment: “Zantonavitch’s approach and style would entail achieving a fiery, dramatic, immediate deposition of everything (every person, every policy, every idea) he considers evil, dangerous, or damaging. My view of reform is more surgical, focused on getting the sequence of steps right so as to minimize the damage inflicted during the transition while ridding the world of the disease of bad policies (and, in a more long-term fashion, through persuasion and free-market education, also ridding it of bad thinking of the sort that motivates bad policies).”

G. Stolyarov II and Franco Cortese Discuss Humankind’s Future

G. Stolyarov II and Franco Cortese Discuss Humankind’s Future

The New Renaissance Hat
G. Stolyarov II and Franco Cortese
March 6, 2015
******************************

Mr. Stolyarov invites life-extension advocate and wide-ranging future-oriented thinker Franco Cortese to discuss a broad array of ideas and possibilities regarding the future of humankind.

Apologies for the technical difficulties at the end. The conclusion of our discussion can be found here. The last several minutes of the conversation focus on how emerging technologies could help overcome current existential risks and help lead to the elimination of brutality and barbarism.

Questions addressed in the discussion include the following:

(1) What do you consider to be humankind’s best opportunities for achieving a bright future within the next several decades?
(2) What do you consider to be the greatest obstacles to the realization of such a bright future?
(3) How could such obstacles be overcome?
(4) What actions can most people take to assist in the acceleration of technological progress so as to solve, within the lifetimes of those alive today, many of the major problems currently associated with the human condition?
(5) How can virtual worlds help to improve the physical world?

Franco Cortese is Affiliate Scholar of the Institute for Ethics & Emerging Technologies, Research Scientist at ELPIs Foundation for Indefinite Lifespans, Assistant Editor of Ria University Press, Fellow of the Brighter Brains Institute, Ambassador for The Seasteading Institute, and Chief Operating Officer of the Center for Interdisciplinary Philosophic Studies.

Stolyarov_Cortese_Discussion

How Can Virtual Worlds Help to Improve the Physical World? – G. Stolyarov II Interviews Peter Rothman

How Can Virtual Worlds Help to Improve the Physical World? – G. Stolyarov II Interviews Peter Rothman

Mr. Stolyarov invites Peter Rothman to discuss the question, “How can virtual worlds help to improve the physical world?”

Peter Rothman, M.S. is Editor of H+ Magazine where he is looking for great articles about the future of technology, humanity, the mind, society, and human culture.

Peter is an engineering and management professional with deep experience in the design, development, and launch, of commercial software products, internet services, and other mission critical systems. He is currently doing research into analysis and visualization of text for a consumer facing application.

He was previously chief scientist of a biometrics-based fraud prevention company. He led the development of Live365.com, one of the largest providers of streaming audio on the Internet. He operated a product development and engineering team for the global multi-million dollar public software company MetaTools/MetaCreations. He founded and operated a startup software company, raised capital, and negotiated eventual sale of company. He has designed and implemented cutting-edge software, algorithms, and technologies.

Peter’s specialties include biometrics, mathematics, streaming media, virtual reality, simulation, text analysis, data visualization, and artificial intelligence.

Peter was an early developer of VR technologies, including developing applications of VR to financial visualization and a concept for unencumbered infantry training using VR for the US Army.

References
– “Welcome To Mixed Reality” – Article by Peter Rothman
– “Retro VR — a brief review of some 1990s HMDs” – Article by Peter Rothman
– Microsoft HoloLens – Official Site
– “VRML” – Wikipedia
– “WebGL” – Wikipedia
– SBIRSource – Avatar Partners
– “Back in the Day” – Pictures of early VR and software products – Posted by Peter Rothman
– H+ Magazine – Articles on Mixed Reality

Adam Alonzi Interviews G. Stolyarov II on Indefinite Life Extension and “Death is Wrong”

Adam Alonzi Interviews G. Stolyarov II on Indefinite Life Extension and “Death is Wrong”

The New Renaissance Hat
G. Stolyarov II and Adam Alonzi
February 22, 2015
******************************

Today I had a pleasant and erudite discussion with Adam Alonzi regarding the feasibility and desirability of attaining indefinite longevity in our lifetimes, as well as Death is Wrong and its impact.

References

– Adam Alonzi’s YouTube Channel
– Adam Alonzi Reads Death is Wrong

“Blockchain Insurance Company” – Short Story by G. Stolyarov II in SOA 11th Speculative Fiction Contest

“Blockchain Insurance Company” – Short Story by G. Stolyarov II in SOA 11th Speculative Fiction Contest

The New Renaissance Hat
G. Stolyarov II
February 20, 2015
******************************

My new short story “Blockchain Insurance Company” is one of the entries in the Society of Actuaries’ 11th Speculative Fiction Contest.

You can read all 16 entries and vote for 3 of your favorites here.

“Blockchain Insurance Company” can be read here.

Bitcoin-coins

“Death is Wrong” Rap and Book Giveaway #3 – Videos by Roen Horn

“Death is Wrong” Rap and Book Giveaway #3 – Videos by Roen Horn

This week I was delighted to find out that Death is Wrong is charting new territory once again.

This is the first rap inspired by a children’s book on indefinite life extension. Thank you to Roen Horn of the Eternal Life Fan Club!

LYRICS by Roen Horn:

I know a book that every kid should read.
Death is Wrong has the wisdom they need.

There is nothing worse than not being alive.
And if we find the cure aging then we CAN SURVIVE.

Death is wrong because life is right.
If we want to live forever , well, then we need to fight.

Death is our enemy and aging is our foe!
This book has truth that every child should know.

There is real hero named Aubrey de Grey.
If you wanna save lives, then he has the way.

Aging kills more people than any other cause,
but lucky for us we have our wizard of Oz.

Evolution doesn’t care if we live or die.
Once you get old, you’re just pushed aside.

Nothing’s gonna change unless we get mad.
If you wanna save yourself, your mom and your dad,

Here’s a little wisdom you won’t hear in church.
If you want eternal life, then we need aging research.

I think death is a FAILURE, and I don’t want to lose.
We should be able to live for as long as we choose!

The world should admit that aging really sucks.
Until we cure aging, we’re all like sitting ducks.

We have no time to waste, so let’s get busy like the bees.
We gotta make haste to avoid disease.

The cure is gonna come, but will it come in time for us?
Our eternal life is way too important to miss this bus.

Eternal life fans know that we have to persist.
Because our life is meaningless if we CEASE TO EXIST.

***

Roen has also done magnificent work giving away copies of Death is Wrong to children and filming the occasions.

Watch this skillfully produced video by Roen – the third in his series.